Rental Property Valuation Pricing: How Income Properties Are Priced
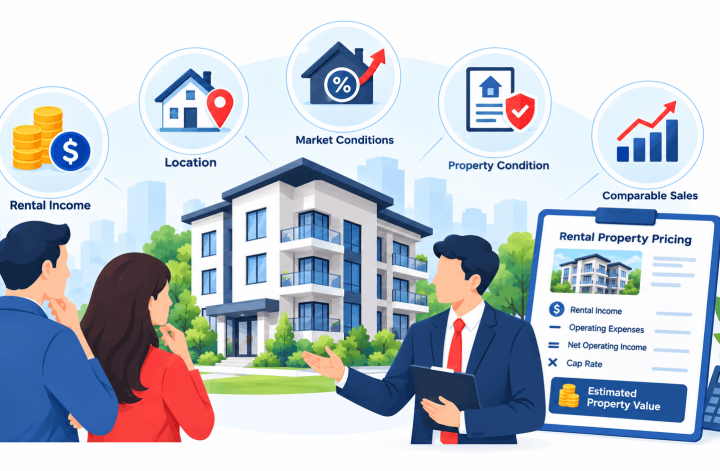
Rental property valuation pricing is the process of determining what an income-producing property is worth based on the money it earns, the risks involved in earning it, and the prices buyers are paying for similar assets in the same market. Unlike a primary residence, which buyers often value for comfort and neighborhood appeal, a rental is primarily a financial instrument. Its price should reflect the cash flow it generates, the stability of its tenants, and the expenses required to keep it operating.
This guide explains how investors, owners, and pricing professionals approach income property valuation, which methods carry the most weight, and where common mistakes lead to overpaying or underpricing. Whether you are considering a purchase, preparing to sell, or setting a rent that supports a fair asset value, the principles below will help you think more clearly about the numbers.
Why Rental Properties Are Valued Differently
Most homes are valued largely by comparing them to similar homes that recently sold. That approach, known as the sales comparison method, still matters for rentals. However, income properties add a second lens: what the property earns. A duplex in a strong rental market might sell for a price that looks high compared to a similar house in the same neighborhood, simply because the duplex produces more rent.
The Three Main Valuation Approaches
Professionals typically use three approaches, sometimes in combination:
- Sales comparison approach: Compares the property to recently sold properties with similar size, condition, location, and features.
- Income approach: Estimates value based on the income the property produces, most commonly through capitalization rates.
- Cost approach: Estimates what it would cost to rebuild the structure today, minus depreciation, plus the land value. This is most useful for newer construction or unusual properties.
For most residential rentals, the income approach and the sales comparison approach carry the most weight, with the cost approach serving as a sanity check.
Understanding Cap Rate Analysis
Cap rate analysis is central to income property valuation. The capitalization rate expresses the relationship between a property’s annual net operating income (NOI) and its value.
The Basic Formula
Cap Rate = Net Operating Income ÷ Property Value
Rearranged to solve for value:
Property Value = Net Operating Income ÷ Cap Rate
Suppose a property produces $24,000 in net operating income per year, and comparable properties in the area trade at a 6 percent cap rate. The estimated value would be $24,000 ÷ 0.06, or $400,000.
What Counts as Net Operating Income
NOI is gross rental income minus operating expenses. It does not include mortgage payments, income taxes, or capital expenditures such as a new roof.
Typical operating expenses include:
- Property taxes
- Insurance
- Property management fees
- Routine maintenance and repairs
- Utilities paid by the owner
- Vacancy and credit loss allowances
- Landscaping, snow removal, and similar services
- Reserves for future replacements (depending on the method used)
A common mistake is overstating NOI by ignoring vacancy. A property that rents at $2,000 per month does not produce $24,000 per year in practice if it sits empty for a month or two between tenants. Most experienced analysts apply a vacancy factor, often between 5 and 10 percent depending on the market.
How Cap Rates Are Determined
Cap rates are not set by formula. They are derived from market evidence. Analysts examine recent sales of similar properties, divide each sale’s NOI by its price, and look at the range of results. Cap rates tend to be lower in markets with strong growth, stable tenants, and low risk, and higher in markets with weaker demand, older housing stock, or greater volatility.
A cap rate reflects the return a buyer expects. A lower cap rate usually signals higher confidence, higher prices, and lower immediate yield. A higher cap rate suggests more risk or a higher required return, which generally means a lower price for the same income.
Gross Rent Multiplier: A Quick Screening Tool
The gross rent multiplier (GRM) is a simpler metric used for initial screening. It divides the property price by its gross annual rent.
GRM = Property Price ÷ Gross Annual Rent
If a property sells for $300,000 and generates $30,000 in gross annual rent, its GRM is 10. GRM is useful for comparing properties quickly, but it ignores operating expenses, so it should not be the final word on value. Two properties with identical GRMs can have very different expense profiles and returns.
Cap Rate Analysis: A Comparison Example
Consider two duplexes in the same city, both listed at $500,000.
| Factor | Property A | Property B |
| Annual gross rent | $42,000 | $42,000 |
| Operating expenses | $12,000 | $18,000 |
| Net operating income | $30,000 | $24,000 |
| Implied cap rate at asking price | 6.0% | 4.8% |
| Condition | Updated | Needs repairs |
| Tenant history | Long-term | High turnover |
Property A produces more income and carries a stronger implied return at the same price. Property B’s lower return may reflect higher expenses, deferred maintenance, or tenant turnover. A buyer comparing these two should ask why the expenses differ and whether the gap can be closed. If Property B’s repairs and turnover costs are temporary, its value could improve. If they are structural, the asking price may be too high.
Comparable Rents and Market Rent Analysis
Rental income is the foundation of the income approach, so accurate rent estimation matters enormously. Analysts look at:
- Current leases at the subject property
- Rents for similar units in the same building or neighborhood
- Listed rents and recently leased rents for comparable properties
- Local rent trends over the past 6 to 12 months
- Concessions, such as free months or reduced deposits, which can distort effective rent
Market rent is not always the rent a property is currently achieving. An owner who has held a tenant for many years at a below-market rate may have a property whose value is understated by the income approach, while a property with an above-market rent that is about to expire may be overstated. Good valuation accounts for both the current lease terms and the likely rent once the lease ends.
Operating Expenses: Where Valuations Often Go Wrong
Expense assumptions can make or break a rental valuation. Several errors appear frequently:
- Using seller-provided expenses without verification. Sellers sometimes omit costs such as management fees or reserves to make NOI look better.
- Ignoring capital reserves. Roofs, water heaters, HVAC systems, and appliances all wear out. Experienced investors set aside money each year for these replacements.
- Underestimating property taxes after a sale. In some jurisdictions, a sale triggers reassessment, which can raise the tax bill substantially.
- Assuming zero vacancy. As noted earlier, even well-managed properties experience turnover.
- Forgetting insurance increases. Insurance costs have risen in many regions, and a buyer’s premium may differ from the seller’s.
A thorough valuation requests historical operating statements, tax records, utility bills, and maintenance logs, then compares them against market norms.
How to Estimate a Rental Property’s Value Step by Step
Here is a practical sequence for working through an income property valuation:
- Gather the income data. Collect current rent rolls, lease terms, deposits, and any other income such as parking, laundry, or storage fees.
- Establish market rent. Compare the property’s rent to recent leases of similar units nearby.
- Calculate gross potential income. Multiply each unit’s market or contract rent by 12 months, then add other income.
- Apply a vacancy and credit loss allowance. Subtract an estimated percentage to arrive at effective gross income.
- Subtract operating expenses. Include taxes, insurance, management, maintenance, utilities, and reserves to find net operating income.
- Identify market cap rates. Review recent sales of comparable income properties and calculate their cap rates.
- Estimate value. Divide NOI by the appropriate cap rate.
- Cross-check with sales comparables. Confirm that the income-based value is consistent with the price per unit, price per square foot, or other metrics for similar properties.
- Adjust for condition and risk. Account for deferred maintenance, lease risk, neighborhood trajectory, and financing terms.
If the income approach and the sales comparison approach produce very different numbers, investigate before choosing one. The gap often reveals an assumption that needs correction.
Pricing a Rental for Sale Versus Pricing for Purchase
Owners preparing to sell an income property often face a different question than buyers. The seller wants a price that reflects the property’s income while also appealing to investors who will run their own numbers.
Sellers benefit from presenting clean, documented financials. A property with verified rent rolls, recent tax bills, and transparent expense history tends to attract more confident offers. Buyers who see unexplained figures often discount the price to account for uncertainty, which can make a property sit longer on the market.
Buyers, meanwhile, should resist anchoring on the asking price. A listing price is a starting point for negotiation, not a verified value. Running an independent income analysis and comparing the result against recent sales helps buyers avoid paying for income that may not materialize.
Common Mistakes in Rental Property Valuation
Even experienced investors fall into predictable traps:
- Relying on a single method. An income-only view can miss neighborhood factors, while a comparable-sales view can miss the income potential of an underused property.
- Using a cap rate from a different market. A 5 percent cap rate in a major metro area is not comparable to a 5 percent rate in a secondary city with different risk profiles.
- Treating appreciation as guaranteed. Projected price growth should not be the primary justification for paying above what the income supports.
- Confusing gross and net figures. Quoting gross rent as though it were profit inflates perceived value.
- Ignoring financing. Leverage affects returns, but the property’s value should be assessed independently of the buyer’s loan terms.
- Skipping professional review for complex properties. Multi-unit buildings, mixed-use properties, and properties with unusual leases benefit from experienced analysis.
Practical Examples of Rental Valuation
Example 1: A Four-Unit Building
An investor evaluates a four-unit building where each unit rents for $1,400 per month. Gross potential income is $67,200 per year. Applying a 7 percent vacancy allowance reduces effective gross income to about $62,500. Operating expenses total $22,000, leaving NOI of about $40,500. In a market where similar buildings trade at a 6.5 percent cap rate, the estimated value is roughly $623,000.
If the seller is asking $700,000, the investor can see that the price implies a cap rate near 5.8 percent. That gap does not automatically make the deal bad, but it signals that the buyer would need to believe in rent growth or expense reductions to justify the premium.
Example 2: A Single-Family Rental
A single-family rental producing $1,800 per month in rent generates $21,600 annually. After taxes, insurance, management, and reserves totaling $7,000, NOI is $14,600. With a market cap rate of 5 percent, the estimated value is $292,000. Here, the sales comparison approach might be more informative, since single-family rentals often trade at prices driven heavily by neighborhood comparables.
Actionable Steps for Owners and Investors
- Maintain organized records of rents, expenses, and maintenance for at least three years.
- Review your rents against the market every 12 months, and understand the legal limits on increases where you operate.
- Budget for capital reserves annually, even if no major repairs are imminent.
- Obtain a professional valuation before listing or making a major purchase.
- Request full operating statements and verify them independently before relying on seller figures.
- Compare cap rates across at least five to ten recent comparable sales, not just one or two.
Working With a Professional Valuation
A credible valuation combines local market knowledge, documented data, and a consistent method. Certified pricing professionals, such as those who hold the C-REPS designation through the National Association of BPO Professionals (NABPOP), are trained to apply these methods to real market evidence. Because C-REPS professionals are licensed agents or brokers rather than appraisers, they bring a sales and market perspective to pricing, which can be especially useful when you need to understand what buyers in your area are currently paying.
When evaluating any valuation provider, ask how they arrived at their figures, which comparables they used, how they treated expenses and vacancy, and whether they can explain the assumptions behind a cap rate. A transparent answer is a good sign.
Frequently Asked Questions
What is rental property valuation pricing?
Rental property valuation pricing is the process of estimating an income-producing property’s worth using its rental income, operating expenses, market cap rates, and comparable sales. It differs from residential home pricing because income performance is a central factor.
What is a good cap rate for a rental property?
There is no single good cap rate. Acceptable rates vary by market, property type, and risk. Lower cap rates are common in strong, stable markets, while higher rates are typical in areas with more uncertainty. Compare the target property to recent local sales.
How do you calculate the value of a rental property?
Divide the property’s annual net operating income by the market cap rate. For example, $30,000 in NOI at a 6 percent cap rate implies a value of $500,000. Cross-check the result against comparable sales.
What expenses should be included in NOI?
Include property taxes, insurance, management fees, routine maintenance, owner-paid utilities, vacancy allowances, and reserves for future replacements. Exclude mortgage payments, income taxes, and major capital improvements.
Is the gross rent multiplier reliable?
The gross rent multiplier is useful for quick screening but should not be the sole basis for a decision. It ignores operating expenses, which can vary widely between properties.
Why does my rental property’s value depend on the income?
Investors buy income properties for the cash flow and returns they generate. A property’s value is closely tied to how much income it produces relative to the return investors require in its market.
How often should I revalue a rental property?
Many owners revisit valuations annually or when market conditions change, when considering refinancing, or before a sale. A fresh valuation helps you spot changes in rents, expenses, or local cap rates.
Can a professional valuation help before I sell?
Yes. A professional valuation helps you set a realistic listing price, identify issues that may concern buyers, and understand how your property compares to recent sales and current investor expectations.
Investment Property Valuation ROI: How C-REPS Professionals Assess Return Potential
Buying an investment property is one of the largest financial decisions many people make. The purchase price is only the starting point. Whether a property will actually earn a good return depends on how accurately it was valued, what it can realistically produce in rent, what it will cost to hold, and where the local market is heading. This is where investment property valuation ROI analysis comes in, and it is the discipline that separates thoughtful investors from speculators.
This guide explains how investment property valuation works, how return on investment is calculated and interpreted, and how certified professionals approach the process. It is written for property investors, first-time landlords, and anyone who wants to understand what a sound valuation looks like before committing capital.
Why Investment Property Valuation Differs From Home Valuation
A home buyer usually values a property based on whether it suits their life: the schools, the commute, the kitchen. An investor values it based on cash flow and appreciation. The same three-bedroom house can be a poor investment at one price and an excellent one at another, even though its physical features never change.
This difference matters because an investment valuation must answer a different question. Instead of asking “What is this home worth to me?” it asks “What will this asset earn, and what will it be worth later?” That shift changes which data matters most.
The Core Inputs
Every sound investment property valuation draws on several categories of information:
- Comparable sales: Recent sales of similar properties nearby, adjusted for differences in size, condition, and features.
- Rental market data: Current rents for comparable units, vacancy rates, and typical lease terms.
- Operating costs: Property taxes, insurance, maintenance, management fees, and utilities the owner pays.
- Financing terms: Interest rate, loan amount, and loan structure, which affect the true cost of ownership.
- Market direction: Employment trends, population movement, new construction, and infrastructure plans.
Understanding ROI: The Metrics That Matter
Return on investment is not a single number. Investors use several measures, and each reveals something different about a property.
Gross Rent Multiplier
The gross rent multiplier (GRM) is a quick screening tool. Divide the purchase price by the annual gross rental income. A lower number generally suggests the property is priced more favorably relative to the rent it produces. GRM is useful for comparing many properties quickly, but it ignores expenses, so it should never be the final word.
Capitalization Rate
The capitalization rate, or cap rate, divides net operating income (rental income minus operating expenses, before financing costs) by the property’s price. A property with $24,000 in annual net operating income priced at $400,000 has a cap rate of 6 percent. Cap rate lets investors compare properties on a like-for-like basis, though what counts as an acceptable cap rate varies by market and property type.
Cash-on-Cash Return
Cash-on-cash return measures the annual pre-tax cash flow against the actual cash invested, including the down payment and closing costs. It reflects the financing structure, which makes it especially relevant for leveraged purchases. A property can have a modest cap rate and still deliver a strong cash-on-cash return if financing is favorable, and the reverse is also true.
Total Return
Total return combines cash flow with appreciation and the effect of loan paydown over the holding period. It gives the fullest picture but depends heavily on assumptions about future prices and rents, so it should be stress-tested rather than taken at face value.
How Certified Professionals Approach the Analysis
Pricing professionals who hold recognized certifications tend to follow a disciplined process. The specifics vary, but the general approach looks like this.
Step 1: Establish a Defensible Market Value
Before any return can be calculated, the investor needs to know what the property is realistically worth. Certified professionals begin with recent comparable sales and adjust for real differences: square footage, lot position, condition, age, and renovation quality. The aim is a value grounded in what buyers are actually paying in that specific neighborhood now, not what sellers hope to get or what an automated estimate suggests.
This is where local market knowledge becomes essential. Two streets apart, a property can sell for noticeably different amounts because of school zones, noise, flood exposure, or simply which blocks have been well maintained. Professionals who work a local market regularly tend to recognize these patterns faster than data models alone.
Step 2: Estimate Achievable Rent
Rent is the engine of investment return, so it deserves careful study. Professionals look at what comparable units are renting for, not what the owner would like to charge. They also consider the condition of the unit, the amenities it offers, and seasonal demand patterns. A realistic rent estimate is often lower than optimistic projections, and building the analysis around a conservative figure protects the investor.
Step 3: Build a Complete Expense Picture
Many weak investments fail on expenses rather than on price. A thorough analysis includes property taxes, insurance, routine maintenance, capital reserves for major replacements such as roofs and HVAC systems, property management fees if applicable, and vacancy allowances. Experienced investors typically budget for vacancy and repairs even in strong markets, because assuming a unit will always be occupied and never need work is one of the most common valuation mistakes.
Step 4: Calculate and Compare Return Metrics
With market value, rent, and expenses established, the professional calculates the relevant ROI measures. The most useful comparison is between the subject property and other opportunities in the same market, since return expectations shift with interest rates and local conditions.
Step 5: Stress-Test the Assumptions
A valuation is only as reliable as its assumptions. Good analysis asks what happens if rents fall by 10 percent, if vacancy doubles, if interest rates rise, or if a major repair arrives in year two. A property that still performs acceptably under several adverse scenarios carries far less risk than one that depends on everything going right.
A Practical Example
Consider a two-bedroom condominium listed at $300,000. Comparable sales in the building and nearby suggest its fair market value is closer to $285,000, since the unit needs updated flooring and the kitchen is dated. Comparable rentals support a monthly rent of $1,900, or $22,800 per year.
Annual operating costs include $3,600 in association fees, $1,800 in property taxes, $600 in insurance, and $1,500 for maintenance and reserves. Allowing 5 percent for vacancy, effective gross income is about $21,660. Subtracting operating costs of $7,500 leaves net operating income of roughly $14,160. Against the $285,000 valuation, that produces a cap rate of about 5 percent.
If the investor puts 25 percent down, plus closing costs, and the mortgage payments total around $12,000 per year in interest and principal, annual cash flow is modest. The cash-on-cash return will depend on the exact cash invested, but the example illustrates an important lesson: a property can look attractive on gross rent alone and still deliver thin returns once costs and financing are included.
The professional’s job in this scenario is not to declare the property good or bad. It is to show the investor the realistic range of outcomes and the assumptions that drive them, so the decision is informed.
Common Valuation Mistakes to Avoid
Several errors appear repeatedly in investment analysis:
- Using asking price instead of market value as the basis for return calculations.
- Ignoring capital expenditures, since roofs, water heaters, and HVAC systems eventually need replacement.
- Assuming full occupancy with no allowance for turnover or vacancy.
- Overestimating rent based on the best-case listing rather than typical comparable units.
- Relying on a single metric, such as gross rent multiplier alone.
- Forgetting taxes on the return, including depreciation recapture and capital gains where applicable.
Working With a Certified Professional
Investors who want a second opinion on valuation can benefit from working with a certified pricing professional. Certification programs typically require training, examinations, and continuing education, which helps ensure that the person has a structured method for analysis rather than relying on instinct alone.
When evaluating any professional, ask how they arrived at their value, which comparable sales they used, and how they treated expenses and vacancy. A trustworthy advisor will explain their reasoning clearly and will be comfortable showing where the assumptions could be wrong.
C-REPS (Certified Real Estate Pricing Specialists) is a network of licensed agents and brokers who have completed specialized training through the National Association of BPO Professionals (NABPOP) certification program. Its members are active real estate professionals rather than appraisers, and they combine systematic training with deep local market knowledge. Because members work as part of a collaborative network, investors can benefit from a broader market perspective than a single agent might offer alone. Investors can review the program’s requirements and find a member through the official C-REPS website.
Frequently Asked Questions
What is investment property valuation ROI?
Investment property valuation ROI refers to the process of estimating a property’s market value and then measuring the return it is likely to produce. It combines an accurate price estimate with projections of rental income, operating costs, financing, and appreciation.
How do you calculate ROI on an investment property?
The simplest approach divides annual net profit by the total cash invested. More precise measures include cap rate (net operating income divided by property value) and cash-on-cash return (annual pre-tax cash flow divided by cash invested). Each answers a slightly different question.
What is a good cap rate for an investment property?
There is no universal answer. Acceptable cap rates vary by market, property type, interest rates, and expected growth. Investors should compare a property’s cap rate against similar properties in the same area rather than against a fixed benchmark.
Why does the purchase price matter less than the rent?
Purchase price matters, but the income a property generates determines whether it is a good investment. A property bought at a fair price that produces strong, reliable rent can outperform one bought cheaply but generating weak income.
How much should I budget for vacancy and repairs?
Many investors plan for a vacancy allowance and set aside a percentage of rent for maintenance and capital reserves. The right figures depend on the property’s age, condition, and location, so local data and professional input are the best guides.
Can I rely on an online estimate for investment decisions?
Automated estimates can be a useful starting point, but they often miss condition, local nuance, and the specific features that drive value. For an investment decision, it is wise to verify any automated figure with recent comparable sales and a professional analysis.
Do I need a certified professional to value an investment property?
You are not required to hire one, but a certified professional can add structure and local expertise, especially for first-time investors or those buying in unfamiliar markets.
Is investment property valuation the same as appraisal?
Not quite. An appraisal is typically performed by a licensed appraiser for lending purposes and follows specific standards. Pricing and investment analysis may be performed by agents or advisors to guide buying, selling, or return assessment decisions.
Common Pricing Mistakes Home Sellers Make (And How to Avoid Them)
Most home sellers approach pricing with more hope than strategy. They anchor on emotional attachments, rely on outdated internet estimates, or follow aggressive agent promises without examining underlying methodology. The result: systematic mispricing that costs thousands in lost equity or extended market time.
The mistakes sellers make tend to cluster into recognizable patterns. Some owners overestimate their home’s value based on personal investment or emotional attachment. Others anchor on their purchase price, ignoring market evolution. Still others delegate pricing entirely to agents without understanding the methodology or questioning recommendations.
What separates successful sellers from frustrated ones isn’t luck. It’s understanding common pricing pitfalls and implementing systematic approaches that prioritize data over emotion, market reality over wishful thinking, and professional expertise over casual estimates.
This guide walks through the most costly pricing mistakes home sellers make, explains the financial and strategic consequences of each error, and provides concrete strategies to avoid them. Whether you’re preparing your home for market or evaluating a pricing recommendation from an agent, understanding these mistakes helps you make decisions grounded in market reality rather than speculation.
Mistake 1: Overpricing Based on Emotional Attachment
The most common and costly pricing mistake stems directly from emotion. Home sellers frequently overvalue what they’ve invested in their property, what they paid for it, or what they believe it deserves in an imaginary market.
Why Emotional Attachment Distorts Pricing
You’ve lived in your home for years. You’ve invested money into renovations, maintained the property, created memories, and formed attachment. Naturally, you believe your home is worth more than comparable properties because you know its quality intimately.
This emotional lens creates systematic overpricing. You remember every repair you’ve made, every upgrade you’ve invested in, and every care you’ve provided. Buyers, by contrast, see a property competing against alternatives in their actual budget range. They lack your emotional investment and historical context.
The kitchen renovation you funded because you love cooking might represent $40,000 of your investment but add only $25,000 of buyer value. The landscaping you’ve maintained meticulously because it brings you joy has little relevance to buyers who primarily want low-maintenance outdoor space.
The Financial Consequence
Overpricing by just 5% on a $500,000 home means listing at $525,000 when market value is $500,000. What happens next is predictable:
First week: Minimal showings. Buyers searching the market immediately recognize that comparable homes sell for 495,000-510,000, making your $525,000 asking price unrealistic.
Weeks 2-4: Extended showings without offers. Your home competes against similar properties correctly priced. Buyer interest shifts to properly priced alternatives.
Weeks 5-8: Price reduction to $510,000, acknowledging that overpricing failed. But buyers have already noticed the extended market time and assume problems exist.
Week 12: Final sale at $485,000 after market exposure reveals buyer resistance.
Financial impact: You listed at $525,000, finally sold for $485,000 (nearly 8% below what accurate pricing would have achieved), wasted three months of carrying costs (roughly 3,000-5,000 in mortgage interest, taxes, utilities, and opportunity cost), and faced buyer psychology that you’re desperate.
The emotional attachment that led to overpricing ultimately cost you $20,000+ in lost equity plus additional carrying costs and psychological disadvantage during negotiation.
How to Avoid Emotional Overpricing
Separate your emotional value from market value. What you paid for your home, what you’ve invested in it, and what it means to you personally is irrelevant to what buyers will pay. This separation is uncomfortable but necessary.
Get a professional valuation from a certified specialist who has no emotional investment in your home and no incentive to overestimate value. Require that specialists show their work: comparable properties used, adjustments made, market conditions considered.
If your emotional valuation significantly exceeds professional recommendations, acknowledge the gap. It signals that your emotional attachment is distorting judgment. Professional valuations exist precisely to counteract this bias.
Trust the market data more than your intuition. Comparable homes that sold in your neighborhood for $500,000 represent actual buyer behavior and willingness to pay. Your belief that your home deserves $525,000 represents hope, not market reality.
Mistake 2: Anchoring on Purchase Price
A surprisingly common pricing mistake involves anchoring on what you paid for your home years ago. “I bought it for $450,000, so it must be worth at least that now,” sellers think, ignoring that markets change dramatically over time.
How Purchase Price Becomes a Pricing Anchor
Your purchase price is irrelevant to current market value. Markets appreciate or depreciate based on supply and demand, interest rates, neighborhood conditions, and economic factors completely unrelated to what any individual paid.
Yet sellers consistently use purchase price as a pricing floor, assuming appreciation over time. This reasoning fails when markets depreciate or appreciate less than expected. A $450,000 purchase five years ago might support a $520,000 current value (appreciating 3.1% annually, compounded). Alternatively, that same home might support only $425,000 in a market that appreciated only 0.5% annually.
Using purchase price as a pricing anchor causes systematic overpricing in depreciating markets and missed opportunity in strongly appreciating markets.
The Market Reality
Markets evolve. Interest rates fluctuate. Employment patterns shift. Neighborhood conditions change. New developments or highway noise might reduce buyer demand. Conversely, new transit access or corporate relocation might increase demand dramatically.
A home’s purchase price is historical information with zero relevance to current value. Skilled buyers and their agents immediately recognize overpricing anchored to old purchase prices and adjust offers accordingly.
How to Avoid Anchor Bias
Explicitly reject your purchase price as a pricing reference point. Acknowledge what you paid, but recognize that it’s historical information unrelated to current value.
Focus exclusively on comparable sales of similar properties in similar conditions selling during similar timeframes. Recent market activity reveals actual buyer behavior and current value far more accurately than your purchase price.
If you paid $450,000 five years ago and that same home currently sells for $420,000, accepting this reality (while emotionally difficult) beats the alternative: overpricing at $450,000, experiencing extended market time, and eventually selling for $415,000 after months of carrying costs.
The market has spoken through comparable sales. Your purchase price is irrelevant.
Mistake 3: Dismissing Professional Guidance in Favor of Internet Estimates
Zillow Zestimates, Realtor.com estimates, and similar automated tools provide rough value ranges but consistently fail to match professional valuations. Yet many sellers trust these algorithms more than experienced specialists.
Why Automated Estimates Miss the Mark
Online valuation tools use algorithms trained on historical data without incorporating current market conditions, neighborhood-specific dynamics, or property-specific details. They might include recent renovations in the algorithm but can’t evaluate renovation quality or buyer preferences in your specific market.
These tools also lack real-time market intelligence. They don’t know that inventory surged last month, changing pricing power. They don’t account for a new employer opening in your area, creating a demand surge. They don’t recognize that your neighborhood is appreciating faster than surrounding areas.
For a rough range, automated estimates provide value. For actual pricing decisions affecting your most valuable asset, they’re dangerously inaccurate.
The Cost of Relying on Automated Estimates
A Zestimate showing $500,000 might represent actual market value of $475,000 or $525,000, depending on market conditions and property specifics. Listing based on the estimate alone means you’re essentially guessing.
The professional specialists you’re dismissing have seen hundreds of comparable sales, know current buyer demand patterns, understand inventory levels, and recognize emerging market trends. Their valuations reflect this expertise.
How to Avoid Misplacing Trust in Automation
Use online estimates as one data point, not the primary pricing source. If a Zestimate conflicts with professional valuation, investigate why. Ask your specialist to explain the difference and show their supporting analysis.
Demand professional analysis from someone with market expertise and no incentive to inflate your home’s value to make a sale seem easier. C-REPS certified specialists prioritize accuracy over optimistic promises.
Compare multiple professional valuations if significant amounts of money are at stake. Specialists using systematic methodology should produce similar values. Large discrepancies warrant investigation.
Mistake 4: Overlooking Current Market Conditions
The same home priced appropriately in a balanced market might be overpriced in a buyers’ market or underpriced in a sellers’ market. Yet many sellers fail to adjust for current inventory levels, buyer demand, and market velocity.
Market Conditions That Change Pricing
Inventory levels dramatically influence pricing power. In balanced markets (4-6 months of inventory at current sales pace), pricing remains relatively stable. In buyers’ markets (8+ months of inventory), prices soften as buyer competition diminishes. In sellers’ markets (under 2 months’ inventory), prices strengthen as buyer competition intensifies.
Days on market for comparable properties reveal market velocity. If comparable homes sold in 10 days last year but require 25 days currently, market conditions have shifted downward. Pricing needs adjustment.
Seasonal patterns matter. Spring markets typically move faster than winter markets. Year-end holidays reduce buyer activity. Professional specialists adjust pricing recommendations for the season.
Interest rates significantly influence affordability and buyer demand. When rates spike, buyer purchasing power declines. Prices typically adjust downward to maintain affordability at lower income levels.
Sellers’ Common Mistake
Sellers frequently price based on market conditions from 6-12 months ago without recognizing how conditions have shifted. “A comparable sold for $500,000 last May,” they think, ignoring that May’s market differed substantially from December’s market.
This creates systematic overpricing when markets shift downward and systematic underpricing when markets shift upward.
How to Avoid Market Condition Missteps
Get current market data, not historical data. Ask your specialist about today’s inventory levels, average days on market for current listings, and recent pricing trends.
Request analysis of both recent comparable sales (within 60 days) and current comparable listings. Recent sales show what buyers actually paid. Current listings show current asking prices (which typically exceed selling prices by 2-5%).
Understand whether current market conditions favor buyers or sellers. This fundamental reality should influence pricing positioning.
Recognize that market conditions change continuously. A home priced correctly in January might need adjustment by March as conditions shift. Quality specialists monitor conditions and recommend adjustments when warranted.
Mistake 5: Overinvesting in Renovations Without Market Validation
Home sellers frequently invest in major renovations expecting dollar-for-dollar return on investment. Yet many renovations fail to deliver proportional value increases. Some actually reduce buyer appeal by creating homes that are highly personalized or over-improved for their market segment.
Renovation ROI Reality
Kitchen renovations typically return 60-80% of investment. Bathroom updates often return 50-75%. Roof replacement and HVAC updates (addressing deferred maintenance) typically return 60-100%. Luxury upgrades, high-end finishes, and personalized installations often recover only 20-40% of costs.
A $60,000 luxury kitchen renovation might add only 35,000-45,000 to your home’s value. That’s money spent from your equity perspective.
Worse, over-improved homes sometimes alienate buyers. A luxury kitchen in a neighborhood of modest homes might actually reduce buyer appeal. Highly personalized spaces (custom theaters, elaborate landscaping, unusual color schemes) appeal to fewer buyers than neutral, flexible spaces.
The Personalization Problem
Renovations based on your preferences rather than market preferences frequently fail to return investment. You invested in the spaces you personally valued. Buyers value different things.
Sellers also frequently complete renovations immediately before selling, expecting full value recovery. But sophisticated buyers recognize new renovations as signs that the previous owner finally addressed deferred maintenance or attempted to disguise problems.
How to Avoid Poor Renovation Decisions
Before investing in major renovations, consult with pricing specialists about which improvements your market values most. Don’t assume all renovations are equally valuable.
Research typical ROI for renovations in your price segment and neighborhood. Some neighborhoods support luxury upgrades; others don’t.
Consider that market conditions affect renovation value. In slowly moving markets, buyer preferences matter less. In competitive markets, neutral finishes appeal to more buyers than highly personalized spaces.
If you’ve already invested in renovations that don’t align with market preferences, accept that you won’t recover full investment. Adjust pricing accordingly rather than expecting buyers to reward your personalization.
The best renovation strategy: address deferred maintenance, update key areas (kitchen, bathrooms) to current but not luxury standards, and maintain neutral finishes that appeal broadly.
Mistake 6: Failing to Adjust for Property Condition Differences
Comparable properties used for pricing rarely match your home perfectly. Professionals adjust prices for differences. Sellers frequently fail to make these adjustments, leading to mispricing.
What Adjustments Matter
Recent major system replacements (roof, HVAC, electrical, plumbing) might warrant 1-3% price adjustments. Significant deferred maintenance (aging HVAC, roof damage, foundation concerns) requires downward adjustments of similar magnitude.
Renovation quality matters. Professionally completed renovations support higher adjustments than DIY work. Custom built-ins and professional design warrant higher value than basic updates.
Lot size differences affect value. Larger lots in suburban areas support higher prices. In urban areas, land value matters less than location walkability.
Common Mistake
Sellers compare their home to nicest properties in their neighborhood, ignoring condition differences. Your home with original systems, average condition, and outdated finishes should price below similar homes with recent renovations and excellent condition.
Yet many sellers price as if their home deserves “best comparable” pricing without acknowledging condition gaps.
How to Adjust Appropriately
Ask specialists to explain adjustments they make between comparable properties and your home. Understand whether your home is better or worse positioned than comparables and by how much.
Be honest about your home’s condition. If your HVAC system is 18 years old and comparable properties have 5-year-old systems, your home warrants downward adjustment.
Focus pricing on properties truly comparable in condition, not on aspirational comparables that look better than your actual property.
Mistake 7: Ignoring Buyer Perception and Market Psychology
Pricing influences buyer psychology in ways sellers frequently overlook. List price anchors buyer perception. Extended market time signals problems. Psychological price points matter more than their numerical difference suggests.
The List Price Anchor Effect
Your initial list price influences buyer perception throughout the selling process. List at $500,000, then reduce to $475,000, and buyers anchor to the original $500,000. They perceive the reduction as a concession rather than an accurate correction.
List at $475,000 from the start, and buyers accept this as market price without perception of overpricing or desperation.
This psychological effect means first-impression pricing matters enormously. Overpricing initially creates lasting perception problems even after price corrections.
Days on Market Signal
Markets recognize extended market time as a signal that something is wrong. Either the price is too high, the property has issues, or both. Once a home is perceived as problematic, recovering from that perception proves difficult.
A home selling after 10 days seems appropriately priced. A home selling after 60 days seems problematic, even if the final price is strong. Buyer psychology matters.
Psychological Price Points
Homes listed at $499,000 receive different buyer attention than homes listed at $505,000, despite a $6,000 price difference. Pricing just below round numbers (hundred-thousand markers, million markers) triggers different buyer search behavior and perception.
However, psychological pricing only works when the underlying price is accurate. It can’t overcome fundamental mispricing.
How to Avoid Perception Mistakes
Price accurately at market entry to capture maximum attention during the critical first 7-14 days. This positions your home for a quick sale at a strong price rather than extended marketing followed by price reduction.
Recognize that initial list price creates lasting perception. Don’t overestimate to create negotiation room. Price correctly from the start.
Use psychological price points (just below round numbers) but only when the price is actually accurate. Psychological pricing isn’t a license to inflate prices arbitrarily.
Mistake 8: Underpricing in Hopes of Quick Sale
Some sellers deliberately underprice their homes, hoping to generate buyer competition and a quick sale. “Price it low, and we’ll get multiple offers,” they think. This strategy frequently backfires.
The Underpricing Strategy Failure
Underpricing sometimes generates quick sales because multiple buyers recognize the value and compete. But this competition for an underpriced property means multiple buyers want to negotiate down further.
Even with multiple offers, an underpriced home sells for less than accurate pricing would have achieved. You trade time for equity.
Additionally, underpricing sometimes fails to generate competition. If your home is underpriced in a slow market, it still sells slowly despite low price. The underpricing provided no benefit.
When Underpricing Makes Sense
Strategic underpricing makes sense in specific situations: you need a rapid sale for relocation or emergency reasons, your home has specific appeal issues that require aggressive pricing, or your market is moving so slowly that only aggressive positioning generates offers.
In these situations, underpricing is a tactical response to market reality, not a strategic choice.
How to Avoid Careless Underpricing
Don’t underprice simply because you’re impatient. Patient pricing captures full market value. Impatient pricing leaves equity on the table.
Consider your specific situation. Do you genuinely need a rapid sale? Or are you creating artificial urgency? Only genuine time constraints justify significant underpricing.
If you choose strategic underpricing, do so intentionally after consulting with specialists who understand your market. Don’t underprice by accident through casual or emotional decisions.
Mistake 9: Trusting Generic Agent Promises Over Data
Many sellers select agents based on aggressive promises about home value rather than careful analysis and market data. “I can sell your home for $550,000,” an optimistic agent claims. Sellers choose this agent, then experience reality when the home won’t sell at $550,000.
This happens repeatedly because sellers want to believe optimistic promises and agents know this. Aggressive value overestimates win listings (and commissions) even though they rarely result in optimal outcomes for sellers.
The Promise Versus Reality Gap
Agents sometimes overestimate home values to win listing agreements, planning to reduce prices after market exposure reveals reality. From the agent’s perspective, they earn commission either way. From your perspective, overpricing costs thousands in lost equity and months of extended market time.
Red Flags for Overestimating Agents
Agents who provide valuations significantly above multiple professional estimates are typically overestimating to secure your listing.
Agents who resist providing detailed comparable analysis or market condition explanation often lack confidence in their valuations.
Agents who promise specific sale prices without detailed methodology or market analysis are making promises they can’t control. Market conditions determine outcomes, not agent promises.
How to Evaluate Agent Recommendations
Request detailed analysis from any agent recommending pricing. They should explain comparable properties used, adjustments made for differences, and current market conditions considered.
Compare multiple agent recommendations. Consistency between recommendations builds confidence. Large discrepancies warrant investigation.
Ask agents to commit recommendations in writing with supporting analysis attached. Agents confident in their recommendations typically accept written commitments.
Trust systematic methodology more than aggressive promises. C-REPS certified specialists prioritize accurate analysis over optimistic promises designed to win listings.
Mistake 10: Failing to Monitor Market Conditions During Marketing
Markets change continuously. A home priced accurately at market entry might need adjustment if conditions shift significantly. Yet many sellers refuse to adjust pricing despite market changes.
When Market Conditions Warrant Price Adjustment
If your home enters the market with 3 months’ inventory and shifts to 6 months’ inventory, pricing needs downward adjustment to maintain competitiveness.
If new inventory surges in your neighborhood, pricing needs adjustment to remain compelling.
If buyer demand indicators shift (job losses, interest rate increases, economic concerns), pricing typically needs adjustment.
If comparable properties recently reduced prices, your pricing likely needs adjustment.
The Stubbornness Problem
Many sellers resist price adjustments, viewing them as personal failure or admission that initial pricing was wrong. But markets change. Intelligent pricing adjustment is a response to market evolution, not failure.
Homes that refuse price adjustments despite market shifts typically experience extended market time and eventual price reduction deeper than strategic early adjustment would have required.
How to Adjust Intelligently
Commit to monitoring your market continuously. If conditions shift after listing, discuss adjustments with your specialist.
Establish trigger points for price adjustment. “If comparable homes’ average selling price decreases by 2%, we’ll adjust our price accordingly.” Having predetermined triggers prevents emotional resistance when adjustment becomes necessary.
Remember that small early adjustments prevent larger late adjustments. Price reduction from $495,000 to $485,000 mid-month signals market adjustment. Price reduction from $500,000 to $475,000 after 90 days signals desperation.
Expert Insights: What Pricing Specialists Know
Professional pricing specialists recognize patterns that sellers frequently miss.
Pattern Recognition from Experience
Specialists who’ve priced hundreds of homes recognize which homes will sell quickly at asking price, which will sell with modest negotiation, and which will require significant price reduction to generate offers.
This pattern recognition comes from experience and market data analysis, not intuition. Sellers lack this pattern recognition simply because they price homes infrequently.
Buyer Behavior Intelligence
Specialists understand actual buyer behavior in your specific market. They know what price point triggers showing requests. They know which features generate disproportionate buyer response. They know whether your market attracts investors, families, or move-up buyers.
Generic pricing advice ignores these market-specific realities.
Negotiation Dynamics
Professionals understand how pricing influences negotiation. Correctly priced homes generate multiple offers with minimal negotiation. Overpriced homes experience seller desperation during negotiation. Underpriced homes generate buyer confidence and aggressive final offers.
The Cost of Mispricing
Specialists quantify the actual cost of mispricing to help sellers understand the stakes involved. “Overpricing by $25,000 typically costs sellers $35,000 once carrying costs and psychological disadvantage are included.” Quantifying costs motivates accurate pricing.
Conclusion
Pricing mistakes cost home sellers thousands in lost equity, extended market time, and negotiation disadvantage. Yet these mistakes cluster into recognizable patterns that sellers can learn to avoid.
Emotional attachment, purchase price anchoring, dismissal of professional analysis, failure to account for market conditions, poor renovation decisions, condition assessment problems, pricing psychology oversight, strategic underpricing, misplaced trust in aggressive agent promises, and failure to adjust as markets shift represent the most costly errors.
Each mistake has a solution: systematic analysis, professional expertise, market data focus, continuous monitoring, and commitment to data-driven decision-making rather than hope-based speculation.
The home sellers who achieve optimal results implement these solutions. They seek professional valuations from certified specialists, demand detailed analysis and methodology, compare multiple perspectives, monitor market conditions continuously, and adjust positioning as reality dictates.
C-REPS certified professionals specialize in exactly these practices. Their training, market expertise, and commitment to systematic methodology help sellers avoid costly mistakes, achieve accurate pricing, sell efficiently, and capture appropriate market value.
Your home’s pricing determines your financial outcome and your selling timeline. These stakes justify investing time in understanding common mistakes and implementing systematic approaches that protect your interests.
The difference between casual pricing and strategic positioning often proves as simple as avoiding these ten common mistakes and working with professionals who prioritize accuracy over aggressive promises.
Frequently Asked Questions
How do I know if my agent’s pricing is accurate?
Request written analysis showing comparable properties, adjustments made for differences, and market conditions considered. Ask about current inventory levels, average days on market, and recent pricing trends. Compare multiple agent recommendations; consistency between recommendations builds confidence. Large discrepancies warrant investigation or obtaining professional valuations. Ask your agent to defend their pricing against comparable sales data, not against your emotional expectations.
What if an appraiser values my home lower than I expected?
If an appraisal comes in below expected value, understand why before accepting it. Request a detailed appraisal explanation. Sometimes appraisers miss recent renovations or fail to recognize neighborhood improvements. Sometimes appraisers are simply conservative. If the appraisal seems inaccurate, request reconsideration with additional comparable data. But if multiple valuations converge on similar value, accept that this represents realistic market value regardless of your expectations.
Can I price my home above market if I’m willing to wait?
You can list at any price you choose, but results follow predictable patterns. Overpriced homes experience extended market time without offers, eventually requiring price reductions deeper than accurate initial pricing would have required. The patience strategy typically fails because buyers recognize overpricing quickly and focus on properly priced alternatives. Time costs money through carrying expenses. Strategic patience makes sense only when market conditions genuinely support waiting.
How much should I invest in staging before selling?
Staging costs typically range from 1,500-5,000 depending on the extent. Well-staged homes often sell faster and for higher prices than unstaged homes, but staging doesn’t change underlying market value. Invest in staging when it helps buyers envision themselves in your home. Don’t expect staging to overcome fundamental pricing problems. Stage properties accurately priced at market entry; don’t use staging to justify overpricing.
What if I receive an offer that seems low?
Evaluate offers against comparable sales data and recent market activity, not against your emotional expectations. If comparable homes sold for $475,000 and you receive an offer for $465,000, that’s only 2% below recent comparable. Demanding $500,000 based on emotional attachment isn’t realistic negotiation. Reasonable offers warrant serious consideration. Unrealistic demands based on overpricing guarantee extended market time.
How often should I adjust my price if my home isn’t selling?
Monitor comparable sales and market activity weekly. If several comparable homes reduce prices or your competitive set shifts, evaluate whether adjustment makes sense. Pricing adjustment after 7-10 days of minimal activity makes sense. Waiting 30+ days before adjusting pricing signals poor initial pricing decisions. Small adjustments early typically work better than large adjustments late.
Should I price based on what I owe on my mortgage?
Your mortgage balance is irrelevant to your home’s market value. You might owe $400,000 on a home worth $425,000 or $375,000. Market value reflects what buyers will actually pay today, not what you owe or what you need to receive. Pricing based on mortgage balance causes systematic overpricing for sellers with small balances and underpricing for sellers with large balances.
What if comparable homes have sold at prices significantly higher than today’s market?
Past sales, even recent ones, represent historical data. Current market value reflects current conditions. If comparable homes sold for $500,000 six months ago but current comparable homes are selling for $475,000, your pricing should reflect current market conditions. Markets change. Historical prices don’t determine current value.
How do seasonal factors affect pricing?
Spring markets typically move faster than winter markets. Seasonal timing influences buyer activity and pricing power. If you’re selling in December (slow season), pricing might need adjustment from spring pricing to attract limited winter buyers. Conversely, spring pricing authority lets you maintain higher prices. Specialists adjust recommendations for the season.
Can I negotiate commission based on high home value?
Agent commission percentage rarely changes based on home price. Standard commissions range from 5-6% regardless of whether your home sells for $400,000 or $800,000. However, you can negotiate commission in competitive markets or when using discounted brokerages. Commission negotiation shouldn’t drive pricing decisions. Price for market reality; negotiate commission separately.
Pricing Your Home Right: The Science Behind Accurate Valuations
Your home is likely the most valuable asset you’ll ever own. Yet most home sellers approach pricing with surprising uncertainty, relying on gut feelings, internet estimates, or agent promises rather than systematic valuation methodology.
The consequences of mispricing are substantial. Overprice by just 5-10%, and your home sits on the market for months while other properties sell. Underprice by the same margin, and you leave tens of thousands of dollars on the table. In either case, you sacrifice time, money, and opportunity.
The difference between guesswork and accuracy lies in understanding the science behind home valuation. Professional pricing combines data analysis, market expertise, and systematic methodology to determine what buyers are genuinely willing to pay in your specific market, right now.
This guide explores the framework that certified real estate professionals use to price homes accurately. Whether you’re a home seller preparing for market entry, a buyer seeking to understand property values, or a homeowner curious about your property’s worth, understanding valuation science helps you make better decisions about your most important asset.
Why Accurate Pricing Matters More Than You Think
Pricing a home isn’t an art form. It’s a calculation grounded in data, comparable properties, market conditions, and buyer psychology. Yet countless homes are mispriced because owners and even agents prioritize wishful thinking over methodical analysis.
The Cost of Overpricing
List your home 10% above market value, and you’ll likely discover that no buyers match your expectations. What happens next varies: aggressive price reductions after months on the market (signaling desperation to savvy buyers), withdrawn listings (damaging future sale prospects), or eventual sales at discounts deeper than your original overpricing mistake.
Overpriced homes experience extended market time, which creates psychological perception problems. Buyers and agents notice when properties linger. Extended listings suggest problems: either the owner is unreasonable about price, the property has hidden issues, or both.
During this extended marketing period, your home competes against newly listed inventory. Properties priced correctly sell. Your overpriced property gets overlooked. The longer this continues, the more negotiating power shifts toward buyers.
The Cost of Underpricing
Conversely, underprice your home, and you lose money directly. List 10% below market value, and you’ll sell quickly. But quick sales mean you’ve given away equity that should have been yours.
Consider this concretely: underpricing a $500,000 home by 10% leaves you $50,000 short. That’s not a small rounding error. That’s real wealth transfer from you to a buyer who recognized the deal.
Underpricing particularly frustrates sellers because it often feels safer psychologically. “Better to sell fast than wait,” many think. Yet this reasoning ignores that accurate pricing also sells relatively quickly while capturing full market value.
The Window Between Purchase and Sale
Homes sell fastest when priced correctly at market entry. This period (first 7-14 days on market) generates maximum buyer attention and competition. Mispriced homes miss this critical window, then require price reductions to attract attention later. By that point, you’ve lost both time and leverage.
Accurate pricing maximizes your position by attracting buyer competition, generating multiple offers, and creating upward price pressure at the point when you have maximum negotiating power.
The Science of Home Valuation
Professional pricing relies on a systematic methodology that removes emotion and prioritizes data. While appraisers (used primarily for mortgage lending) focus on property condition and comparable sales, market pricing specialists also factor in current buyer demand, days-on-market for comparables, and real-time market velocity.
Comparative Market Analysis (CMA)
The foundation of professional pricing is Comparative Market Analysis. Rather than picking random comparable properties, CMA identifies homes that truly parallel your property in meaningful ways.
Key comparables include:
Recently sold properties in your immediate neighborhood or comparable areas (usually within the last 3-6 months)
Properties currently on the market at similar price points (representing active competition)
Properties that failed to sell or were delisted (understanding market resistance levels)
Properties that sold substantially above or below list price (revealing market strength or weakness)
Quality CMA analysis examines at least 8-12 comparable properties, analyzing what makes them similar to and different from your home. An agent claiming they based pricing on three random comps hasn’t conducted serious analysis.
Data Points That Drive Valuation
Professional pricing incorporates systematic data analysis across multiple property characteristics:
Location and Neighborhood: Properties in school districts with high ratings command different pricing than districts with lower ratings. Proximity to employment centers, transit, shopping, and parks influences buyer demand. Neighborhood appreciation trends matter: is the area appreciating or depreciating? Growing neighborhoods with strong demand support stronger pricing.
Property Size and Layout: Square footage is foundational, but layout complexity matters. Open-concept homes may appeal more strongly in some markets than homes with compartmentalized rooms. Number of bedrooms versus bathrooms reflects changing buyer preferences and household compositions.
Age and Condition: Newer homes typically command premiums over older properties, though well-maintained historic homes with character sometimes overcome this. Major systems (HVAC, roof, electrical, plumbing) significantly influence value. Recent renovations and updates add value, but only when aligned with market preferences.
Lot Size and Outdoor Space: In some markets, land value comprises substantial home value. Larger lots appeal to buyers wanting privacy and space. In urban areas, lot size matters far less than walkability and density.
Amenities and Features: Quality kitchens and bathrooms influence buyer perception. Energy efficiency, smart home features, outdoor living spaces, and garage configurations all affect value. However, over-customization can limit buyer appeal; homes with unusual layouts or extreme personalization may appeal to fewer buyers.
Market Conditions: Inventory levels determine pricing power. Balanced markets with 4-6 months of inventory at current sales pace support stable pricing. Buyers’ markets with excess inventory (8+ months of inventory) push prices downward as competition intensifies. Sellers’ markets with limited inventory (under 2 months) create upward price pressure.
The Pricing Methodology: From Data to Market Value
Converting data into accurate pricing requires a systematic methodology that professional specialists follow consistently.
Step 1: Identify True Comparable Properties
Start by identifying properties that genuinely parallel your home. Comparables should share fundamental characteristics: similar square footage (within 10-20%), comparable lot size, similar age or condition, matching bedroom and bathroom count, and location in the same or closely adjacent neighborhoods.
Many amateurs make the mistake of using properties that are somewhat similar but miss critical differentiators. A home with a pool isn’t truly comparable to one without if market research shows pools don’t add proportional value in your area. A home recently renovated differs substantially from a home in its original condition.
Professional analysis acknowledges these differences, adjusting comparable prices upward or downward based on how your home compares. This adjustment process converts comparable sales into adjusted values that better reflect your home’s likely market value.
Step 2: Calculate Adjusted Values
For each comparable property, professionals analyze:
Sale price and date (more recent sales weigh more heavily than older sales)
What the property sold for relative to list price (revealing buyer demand: did it sell over list or below?)
Time on market before sale (fast sales suggest proper pricing; long marketing periods suggest overpricing or property issues)
Any unique circumstances (foreclosure sales, estate sales, buyer and seller relationships that might affect pricing)
Adjustments for differences between comparable and subject property (your home)
Adjusted comparable values provide a range rather than a single “right” price. If your home’s adjusted comparable values range from $445,000 to $465,000, your accurate list price likely falls within this range, adjusted slightly for current market conditions.
Step 3: Account for Market Conditions
Current market conditions significantly influence pricing. The same home priced at $500,000 in a balanced market might appropriately list at $475,000 in a buyers’ market or $525,000 in a sellers’ market.
Professional specialists analyze:
Current inventory levels and months of supply
Average days on market for homes in your category
Recent pricing trends (are comparable homes selling for increasing or decreasing prices?)
Buyer demand indicators (are homes receiving multiple offers or sitting?)
Seasonal considerations (some markets shift seasonally; spring markets differ from winter markets)
Economic indicators affecting buyer behavior (interest rates, employment, economic confidence)
Common Valuation Mistakes That Cost Money
Understanding what professionals avoid helps explain why systematic methodology matters.
Mistake 1: Using Only Online Estimates
Zillow Zestimates, realtor.com estimates, and similar automated tools provide general ranges but lack the precision of professional analysis. These tools use algorithms based on historical data without considering current market conditions, neighborhood-specific dynamics, or property-specific details.
Online estimates often miss recent renovations, fail to recognize neighborhood appreciation trends, and don’t account for competitive inventory entering your market. Relying on them for pricing decisions risks substantial mispricing.
Mistake 2: Anchoring on Your Purchase Price
What you paid for your home is irrelevant to its current market value. Markets shift. Your $400,000 purchase five years ago might support a $500,000 sale or a $370,000 sale depending on market conditions. Anchoring on purchase price leads to overpricing if your market appreciated less than expected or underpricing if your market appreciated more substantially.
Professional specialists focus exclusively on current market value, not historical acquisition cost.
Mistake 3: Emotional Attachment to Features
Owners frequently overvalue personal upgrades. That $50,000 custom kitchen renovation might add $30,000 to market value. The high-end landscaping you installed because you love gardens might appeal to relatively few buyers. Personal theaters, custom wine rooms, and other highly specific installations can actually limit buyer appeal.
Professionals evaluate features from a buyer’s perspective: what do actual market participants value, not what the owner values?
Mistake 4: Ignoring Market Velocity
A home priced correctly in a fast-moving market might be overpriced in a slowing market. Professional specialists track not just comparable prices but market velocity. If comparable homes sold in 10 days on average six months ago but are now selling in 25 days, market conditions have shifted. Pricing needs adjustment accordingly.
Mistake 5: Comparing to Aspiration Rather Than Reality
Comparing your home to the nicest homes in your neighborhood provides inflated value perspectives. Accurate analysis compares to homes actually competing for the same buyers: homes similar to yours, selling during similar timeframes, in similar market conditions.
The C-REPS Difference: Why Certification Matters
C-REPS professionals distinguish themselves from typical real estate agents through specialized training, rigorous certification, and commitment to systematic valuation methodology.
Professional Certification and Training
C-REPS designation requires completion of specialized training covering valuation methodology, market analysis, pricing strategy, and professional ethics. Agents must pass certification exams demonstrating competency, then maintain their designation through continuing education and professional standards compliance.
This formalized training distinguishes C-REPS specialists from agents who learned pricing through trial and error or who approach each listing without systematic methodology.
Deep Market Expertise
C-REPS professionals combine their training with extensive local market knowledge. They understand not just what homes sold for, but what current buyers are actually willing to pay in today’s market. They track inventory levels, buyer competition, and market velocity continuously.
This real-time market knowledge prevents the common mistake of relying solely on historical comparable sales without adjusting for current conditions.
Collaborative Network Advantage
When you work with a C-REPS professional, you gain access to an entire network of certified specialists. This collaboration means your listing benefits from multiple perspectives on valuation, broader market insight than any solo agent could provide, and coordinated marketing efforts across a professional network.
Accuracy-Focused Approach
C-REPS professionals are held to higher professional standards regarding pricing accuracy. Rather than optimizing for quick sales or inflated list prices that eventually require reductions, they prioritize accurate positioning that sells homes relatively quickly at strong prices.
How to Work with Pricing Specialists
Understanding the valuation process helps you work effectively with professionals.
Before Meeting with Specialists
Gather information about your home: accurate square footage, lot size, age, major systems, recent renovations, and property features. Document the condition of your home objectively. Collect information about your neighborhood: school district ratings, neighborhood appreciation trends, proximity to amenities.
Understand your timeline and goals. Are you selling quickly to relocate? Do you have flexibility? Are you targeting maximum price regardless of timeline? These factors influence positioning strategy.
During CMA Discussion
Ask your specialist to show you the comparable properties they selected and explain why each was chosen. Understand the adjustments they made for differences between comparables and your home. Ask about current market conditions and how they influenced pricing recommendations.
A quality specialist will show their work, walk you through the analysis, and welcome questions about their methodology.
Pricing Presentation
Your specialist should provide a detailed pricing recommendation with rationale, not just a single number. The recommendation should include a supported price range with explanation for adjustments from comparable sales.
Ask specifically about recent market trends affecting pricing. How many homes in your category are currently on market? What’s the average days on market for recent sales? Are homes selling above, at, or below list prices?
Ongoing Monitoring
Market conditions change. If your home is on the market for 15 days without showings, that’s different from receiving multiple offers. Professional specialists monitor market response and recommend pricing adjustments when market conditions warrant.
Expert Insights: What Market Specialists Know That Others Don’t
Professional pricing specialists understand nuances that casual observers miss.
Buyer Psychography Matters
Homes listed at $499,000 receive different buyer attention than identical homes listed at $505,000, even though the difference is minimal. Pricing just below psychological price points (full million markers, hundred-thousand markers) affects buyer search patterns and perception.
However, this tactical pricing only works when the home is already accurately positioned. Psychological pricing can’t overcome fundamental mispricing.
Seasonal Patterns Are Real
Spring markets typically generate stronger buyer demand and competition. Winter markets move more slowly. Year-end holidays reduce buyer activity. Professional specialists understand these patterns and price accordingly, recognizing that a home selling in January faces different market conditions than an identical home selling in May.
Days on Market Signals More Than You Think
Homes that sell quickly (under 10 days) suggest they were priced correctly or below market. Homes that sell after 30+ days signal potential overpricing or property issues to savvy buyers, even if the property eventually sells.
This creates incentive for accurate pricing at market entry. Once a home is perceived as overpriced (signaled by extended market time), recovering from that perception proves difficult.
Listing Price Anchors Buyer Perception
Your initial list price influences buyer perception throughout the selling process. If you list at $500,000 then reduce to $475,000 six months later, buyers anchor to the original $500,000 and perceive the reduction as concession rather than accurate positioning. Conversely, homes priced accurately at $475,000 from the start generate stronger buyer perception and quicker sales.
The Financial Impact of Accurate Pricing
Consider concrete financial scenarios to understand accurate pricing’s value.
Scenario 1: Overpriced Home
List price: $520,000 (10% above accurate market value of $475,000)
Result: Home sits for 90+ days, receives minimal showings, generates no offers
Price reduction after 60 days: $500,000 (still overpriced)
Final sale price after 120 days: $465,000 (15% below original list price)
Outcome: Extended marketing period, lower final price, increased carrying costs (mortgage, taxes, insurance, utilities during extended ownership), psychological perception of desperation, and opportunity cost of capital tied up in unsold home.
Scenario 2: Accurately Priced Home
List price: $475,000 (market value)
Result: Home generates multiple showings in the first week, generates competing offers by day 7
Final sale price after 14 days: $485,000 (101% of list price)
Outcome: Quick sale, strong price, reduced carrying costs, favorable buyer psychology, opportunity to proceed with next transaction.
Financial comparison: The accurately priced home nets approximately $20,000 more than the overpriced home ($485,000 versus $465,000), accomplishes the sale in 1/8th the time, avoids extended carrying costs, and maintains strong buyer perception.
Conclusion
Pricing your home accurately requires far more than guesswork or generic internet estimates. It demands systematic analysis, professional market expertise, and commitment to data-driven methodology that converts comparable properties, market conditions, and buyer behavior into realistic pricing that captures full market value while selling in reasonable timeframes.
The stakes matter significantly. A pricing error of just 5% on a $500,000 home equals $25,000 in direct financial impact. Beyond direct financial cost, overpricing creates extended market time with all its associated carrying costs and negative perception effects. Underpricing leaves wealth on the table permanently.
C-REPS certified professionals specialize in exactly this challenge. Their training, market expertise, and commitment to systematic valuation methodology help homeowners price accurately, sell successfully, and capture appropriate market value.
Whether you’re preparing to sell your home, evaluating your property’s worth, or simply curious about valuation methodology, understanding the science behind accurate home pricing helps you make better decisions about your most valuable asset.
The difference between casual pricing and professional accuracy often proves as simple as working with someone who understands not just comparable properties, but the systematic methodology that converts comparable data into accurate, defensible pricing that serves your interests and respects market reality.
Frequently Asked Questions
How often should I get my home revalued?
Market conditions change continuously. If you’re selling, get a professional valuation immediately before listing. If you own your home and want to understand current value for refinancing, equity access, or insurance purposes, annual revaluations make sense during active market periods. In stable markets, valuations remain relevant for 6-12 months. In rapidly changing markets, revaluate quarterly. Professional specialists monitor market conditions and recommend revaluation when conditions shift meaningfully.
What’s the difference between a professional valuation and an appraisal?
Appraisals (ordered by lenders for mortgage purposes) focus on property condition and comparable sales to determine lending value. Appraisers follow specific standardized processes and deliver formal appraisal documents. Professional valuations focus on current market value and what buyers will actually pay today. Specialists consider not just comparable sales but current inventory levels, buyer demand, and market conditions. Appraisals typically run $400-600; professional valuations vary widely depending on who provides them (some agents provide free valuations with listing agreements).
How much does home staging affect valuation?
Staging addresses buyer perception and home presentation, not fundamental property value. A well-staged home may show better during showings and influence buying decisions positively, but it doesn’t change the property’s actual market value. Valuation methodology bases pricing on comparable properties’ actual sale prices and current market conditions, not on presentation. That said, strategic staging that helps buyers envision themselves in the home can support achieving full market value by improving showings and buyer confidence.
Can my home’s value differ significantly between appraisers?
Yes, inconsistency between appraisals suggests either different appraisers using different comparable properties or different interpretations of condition and adjustments. Values within 3-5% of each other are typical variation; larger differences warrant investigation. Using multiple specialists (appraisers or professional valuators) to validate pricing makes sense for major decisions. If an appraisal comes in significantly below your expected value, understand why before accepting it.
How do I know if my agent’s pricing recommendation is accurate?
Request that your agent show you the comparable properties they used, explain the adjustments they made, and document their analysis in writing. Ask about current market conditions: inventory levels, average days on market, sales above or below list price. A professional will welcome detailed questions about their pricing methodology. If your agent resists showing their analysis or uses vague pricing justifications, consider getting a second professional opinion.
What happens if my home won’t appraise at the sale price?
If a buyer’s lender appraises your home below the agreed sale price, several options exist: renegotiate the sale price downward to match the appraisal, the buyer provides additional down payment to cover the appraisal shortfall, or the sale terminates. Accurate pricing at market entry minimizes this risk; overpriced homes face appraisal shortfall more frequently. If appraisal issues concern you, get a professional valuation before listing to understand realistic market value and price accordingly.
How much should I invest in renovations before selling?
This depends on your specific home, market, and renovation category. Kitchen and bathroom updates typically offer the best return on investment (60-80% of costs recovered). Roof replacement, HVAC updates, and other deferred maintenance typically recover 60-100%. Luxury upgrades and highly personal renovations often recover less than 30%. Rather than assuming renovations increase value, consult with specialists who understand which improvements your specific market values most. Sometimes strategic staging and cleanup provide better ROI than expensive renovations.
Do I need a C-REPS specialist or can any agent price my home?
Any licensed agent can provide a pricing recommendation, but C-REPS certified specialists bring specialized training and formalized commitment to valuation methodology. If accurate pricing matters to you (and it should), working with certified professionals reduces the risk of mispricing. C-REPS specialists have demonstrated competency through testing and maintain their credentials through continuing education, unlike agents without specialized certification.
How do international buyers and investors affect local home pricing?
In some markets, investor and international buyer activity significantly influences pricing. Cash buyers often compete aggressively for properties, pushing prices upward. Investor buyers sometimes focus on cash flow and rental income rather than value, influencing investment property pricing differently than owner-occupant pricing. Professional specialists understand buyer composition in your market and how it affects pricing dynamics.
Home Seller’s Guide: What to Expect During a Professional Property Valuation
When you first decide to explore selling your home, one of the earliest and most important steps is getting a professional property valuation. Yet many home sellers approach this process with uncertainty. What exactly happens during a valuation? What should you prepare? How long does it take? What will the professional evaluate? What questions should you ask?
Professional property valuations are fundamentally different from casual online estimates or your personal attachment to your home’s worth. A valuation conducted by a trained, certified professional provides an objective assessment grounded in market data, comparable properties, and systematic analysis. Understanding what happens during this process reduces anxiety and helps you make confident decisions about selling.
This guide walks home sellers through the complete property valuation experience. We’ll explain what to expect before, during, and after the valuation, how professionals approach their work, what factors they evaluate, and how to position yourself for the most accurate and favorable assessment possible.
What Is a Professional Property Valuation?
A professional property valuation is a systematic evaluation of your home’s market value conducted by a trained real estate professional. Unlike casual estimates or online tools, professional valuations combine comparable sales data, property condition assessment, market analysis, and expert judgment to determine what your home is worth in today’s market.
It’s important to understand what a valuation is not. A professional valuation is not an appraisal. Appraisals are ordered by lenders and follow strict federal standards. Valuations are more flexible assessments conducted for various purposes, including pricing guidance, refinancing decisions, investment analysis, or simply understanding your home’s value.
C-REPS professionals conduct valuations as trained, certified real estate agents and brokers. They’re not appraisers, but they are extensively trained in valuation methodology through the National Association of BPO Professionals (NABPOP) certification program. This training distinguishes them from typical agents who may rely more on intuition than systematic analysis.
The purpose of a valuation is straightforward: to provide an accurate, defensible estimate of what your home is worth based on current market conditions, comparable properties, and property-specific factors.
Why Professional Valuations Matter
In an industry where pricing accuracy directly affects financial outcomes, professional valuations serve several important functions for home sellers.
Pricing guidance for sale. If you’re listing your home, an accurate valuation establishes the foundation for an appropriate listing price. Overpricing by even 5-10% can dramatically reduce buyer interest and extend your time on market. Accurate pricing attracts buyers and generates momentum.
Refinancing decisions. Understanding your home’s current market value helps you make intelligent refinancing decisions. If your home has appreciated, you may have sufficient equity to refinance or access equity through a cash-out refinance.
Estate or divorce planning. When homes are part of estate settlements or divorce agreements, an objective valuation by a certified professional prevents disputes and ensures fair division of assets.
Investment analysis. If you’re considering investment properties, professional valuations provide the market-based data needed for sound investment decisions.
Insurance coverage verification. Understanding your home’s current market value helps ensure your insurance coverage is adequate for replacement value.
The common thread: professional valuations transform guesswork into data-driven decision-making. For a transaction involving your most valuable asset, the cost of professional valuation is trivial compared to the financial consequences of mispricing.
Before the Valuation: What Sellers Should Know
Professional valuations typically require scheduling in advance. When you contact a C-REPS professional or other certified valuation specialist, be prepared to provide basic information about your property.
Property basics include your home’s address, type (single-family, condo, multi-unit), age, size (square footage), number of bedrooms and bathrooms, lot size, and any major improvements or renovations.
Timeline flexibility matters. Most valuations can be scheduled within a few days, but professionals appreciate advance notice when possible. If you need a valuation urgently, communicate that when requesting the appointment.
Access requirements should be clarified. The valuation professional will need access to all areas of the property, including the attic, basement or crawl space, garage, and exterior. Ensure that any security systems are disabled or that you’ll be present to grant access.
Availability preferences help schedule efficiently. Professionals often have preferred times for valuations. Morning or midday appointments typically work better than early evening, as professionals want adequate light for exterior evaluation and photography.
Recent improvements or repairs should be noted when scheduling. If you’ve recently replaced the roof, updated the kitchen, or completed other significant work, mention this. The professional will ask detailed questions about these improvements.
Known issues or concerns can be mentioned upfront, though professionals will identify these themselves during the evaluation. If there’s a history of roof leaks, foundation concerns, or other issues, this context can be helpful.
When the appointment is scheduled, the professional will likely confirm the appointment date and time, sometimes providing guidance on how to prepare the home.
Preparing Your Home for Valuation
While professionals conduct valuations for properties in various conditions, preparing thoughtfully helps ensure the valuation is accurate and favorable. Preparation is not about deception; it’s about allowing the professional to see your home clearly.
Deep cleaning throughout makes the most significant difference. A thoroughly clean home presents better and allows professionals to assess condition rather than be distracted by clutter or dirt. Pay special attention to kitchens, bathrooms, and high-traffic areas.
Declutter to show space. Remove excess furniture, personal items, and clutter that obscures room size and layout. A home that looks spacious and organized presents better than one packed with belongings.
Address obvious maintenance issues. Fix leaky faucets, replace burned-out light bulbs, repair broken cabinet doors, and address other visible maintenance problems. These signal poor care and create negative impressions.
Ensure good lighting. Open curtains and blinds to maximize natural light. Replace any burned-out bulbs in interior fixtures. Good lighting makes spaces look larger and more inviting.
Organize accessibly. If the professional requests to see the attic or basement, have these spaces as organized as possible. This creates a favorable impression about overall home maintenance.
Prepare documentation. Gather receipts or records for major improvements, roof replacement, HVAC servicing, electrical or plumbing updates, or other significant work. Having this information readily available helps the professional understand your home’s condition and investment in maintenance.
Secure pets. Arrange to have pets confined or boarded during the valuation. Pets create distractions and potential liability concerns for the professional.
Ensure access. If you have security systems, gate locks, or other access restrictions, have these ready to grant the professional entry. Difficult access can complicate the valuation process.
The goal is straightforward: help the professional see your home’s best features without obstacles or distractions.
During the Valuation: What Happens
Most residential property valuations require 30 minutes to an hour, depending on the property’s size and complexity. Understanding the typical process reduces surprises.
Initial walkthrough. The professional typically begins with an exterior evaluation, examining the property’s curb appeal, roof condition, siding, windows, doors, landscaping, and overall maintenance. They’ll photograph or note significant features and condition.
Interior systematic evaluation. Moving inside, the professional systematically evaluates each room, noting size, condition, flooring, walls, ceilings, lighting, and fixtures. They’ll take measurements of major living spaces and note architectural features, windows, and condition issues.
Kitchen and bathroom focus. Kitchens and bathrooms receive particular attention because they significantly impact value. Professionals note appliance age and condition, cabinet quality, countertop materials, plumbing fixtures, and layout functionality.
Systems inspection. The professional evaluates visible evidence of major systems, including HVAC (furnace, air conditioning), electrical panel (updated or outdated), plumbing (evidence of leaks or corrosion), water heater age, and roof condition. They’re not conducting detailed inspections, but they note obvious issues.
Condition assessment. Throughout the walkthrough, the professional evaluates overall condition, noting deferred maintenance, recent updates, cosmetic condition, and any obvious problems like water damage, foundation cracks, or pest evidence.
Measurement and documentation. The professional takes measurements of major rooms and living areas, photographs the exterior and key interior spaces, and documents significant features, improvements, or condition issues.
Exterior and site evaluation. They examine the lot size, landscaping, driveway condition, drainage, and any site-specific factors affecting value. For multi-level homes, they note the number of stories and any unusual architectural features.
Comparable sales analysis. While some of this occurs in the office, the professional may discuss comparable properties they’re aware of in the local market, asking questions about your home’s positioning relative to recent sales.
Seller communication. The professional will likely ask you questions about your home, recent improvements, maintenance history, neighborhood changes, and your understanding of the market. They’re gathering context that helps refine their valuation.
Throughout this process, professional valuators maintain objectivity. They’re evaluating your property systematically against comparable properties and market data, not making personal judgments about your home or its features.
What Professionals Evaluate: Key Factors
Understanding what professionals focus on helps you recognize the factors that truly drive valuation and where preparation matters most.
Property condition ranks high in valuation factors. Homes in excellent condition command premiums. Properties requiring deferred maintenance see value reduction. Condition is visible and directly impacts what buyers will pay.
Square footage and layout affect value significantly. Larger homes generally command higher prices, but unusual layouts or low ceilings can reduce value per square foot.
Bedroom and bathroom count matters, particularly for residential properties. Homes with fewer bedrooms than comparable properties sell at a discount. Additional bathrooms add value disproportionate to their cost.
Lot size affects value based on market preferences and local norms. Larger lots may be valued highly in some markets; they’re irrelevant or undesirable in others.
Age and construction quality influence valuation. Newer homes typically command premiums, though well-built older homes may hold value. Materials and construction methods affect assessed value.
Location and neighborhood are critical. Homes in desirable locations with good schools, walkability, or commute access command premiums. Neighborhood trends affect value trajectory.
Recent improvements and updates can add value. A new roof, HVAC, plumbing, electrical updates, kitchen renovation, or bathroom updates all contribute to higher valuation if completed professionally.
Energy efficiency increasingly matters to buyers. Homes with energy-efficient windows, insulation, HVAC systems, or solar power may command premiums.
Parking and garage factors vary by market but significantly affect value in urban areas or places with limited parking.
Special features like waterfront access, views, architectural significance, or exceptional lot characteristics may justify premium pricing.
The valuation professional weighs these factors systematically, comparing your home to recent comparable sales and adjusting for differences. The result is a valuation grounded in comparable sales analysis, current market conditions, and professional expertise.
Understanding the Valuation Report
After completing the valuation, the professional prepares a detailed report. Understanding what this report contains helps you evaluate its accuracy and use it effectively.
The executive summary typically includes the property address, valuation date, property type, and the appraiser’s or valuer’s conclusion about market value.
Property description documents the subject property’s characteristics, including age, size, bedroom and bathroom count, construction quality, special features, and current condition.
Comparable sales analysis shows the properties used to establish market value, including sale prices, adjustments for differences, and the valuation conclusion drawn from comparable sales.
Condition assessment documents visible condition issues, recent improvements, and maintenance level. This section supports the concluded value by explaining how condition factors into the valuation.
Market analysis provides context about local market conditions, absorption rates, inventory levels, and market trends affecting the property.
Detailed breakdown often shows how the professional arrived at the valuation, including what factors supported value and what factors reduced value.
Photographs document the property’s condition, exterior appearance, key interior spaces, and notable features or issues.
The report’s level of detail varies depending on the valuation’s purpose and the professional’s methodology. Professional C-REPS valuations typically provide comprehensive detail supporting the concluded value.
Common Questions Sellers Ask During Valuations
Home sellers often have questions during the valuation process. Professional valuators welcome reasonable questions that help them understand the property and your goals.
How does my home compare to similar properties? This is reasonable to ask. Professionals can explain how recent comparable sales inform the valuation and how your home’s condition, features, and location compare to properties used for comparison.
What improvements would add most value? Professionals can offer perspective on which improvements might increase value most efficiently, though they’re typically not providing renovation consulting.
Is this valuation for listing purposes? Understanding the valuation’s intended use helps professionals interpret your question. Valuations for sale pricing may differ slightly from valuations for refinancing, as they may account for market-specific positioning.
What’s your assessment of the local market? Professionals typically offer perspective on whether the market is strong or weak, inventory levels, and demand characteristics.
How long should the home take to sell at this value? This is reasonable to discuss. Market conditions, competition, and positioning all affect time-on-market estimates.
Are there obvious issues that would concern buyers? This is an important question. Professionals can highlight condition issues that inspectors will certainly identify and that buyers will use in negotiations.
Questions to avoid include asking the professional to deliberately inflate or deflate the valuation, asking them to suggest illegal pricing strategies, or testing their objectivity with biased scenarios. Professional valuators maintain objectivity and won’t be swayed by seller pressure to adjust valuations beyond what market data supports.
After the Valuation: Using the Report Effectively
Once you receive the valuation report, several important next steps follow.
Understand the valuation. Read through the report carefully, understanding not just the concluded value but the reasoning behind it. Ask the professional to clarify anything unclear.
Compare to your expectations. If the valuation differs significantly from your expectations, discuss this with the professional. What factors caused the difference? Are you missing context about recent comparable sales or market conditions?
Use the valuation for strategic decision-making. If you’re selling, the valuation informs your listing price. If you’re refinancing, it determines your available equity. Use the professional’s analysis to make informed decisions.
Keep documentation. Store the valuation report securely. You may need it for refinancing, tax purposes, insurance considerations, or future reference.
Discuss pricing strategy. If you’re listing, work with your real estate professional to translate the valuation into an appropriate listing price. Market positioning, marketing strategy, and condition all factor into the final listing price decision.
Share with relevant parties. If you’re in a divorce or estate settlement, the valuation provides an objective basis for discussions about asset division.
Update your insurance. If the valuation significantly exceeds your home’s insured value, contact your insurance agent to ensure adequate coverage.
Valuation vs. Appraisal: Understanding the Difference
Many home sellers confuse valuations with appraisals. Understanding the distinction helps you recognize which service you need.
Appraisals are ordered by lenders and follow strict federal standards (USPAP, Uniform Standards of Professional Appraisal Practice). Appraisers are licensed and regulated. Appraisals are required for mortgage lending and provide the value the lender will use to determine loan-to-value ratios.
Valuations are conducted by trained real estate professionals using systematic methodology but without the rigid federal standards governing appraisals. Valuations are more flexible and used for various purposes, including pricing guidance, investment analysis, and refinancing decisions.
For home sellers, valuations are typically more relevant than appraisals. Valuations provide accurate market pricing information and help determine appropriate listing prices. Appraisals become relevant when you’re refinancing or dealing with mortgage lenders.
A C-REPS professional provides valuations trained in systematic methodology and market analysis. This is distinct from an appraisal but provides a professional, defensible assessment of market value.
Choosing a Professional Valuation Provider
Not all professionals providing valuations are equally qualified. Understanding what distinguishes quality valuation providers helps you select someone you can trust.
Certification matters. C-REPS professionals complete training and certification through NABPOP, demonstrating commitment to professional standards and systematic methodology. Certified professionals have passed exams and maintain continuing education requirements.
Local market knowledge is essential. A professional who understands your specific market, recent comparable sales, local trends, and neighborhood characteristics provides more valuable guidance than someone unfamiliar with your area.
Experience counts. Professionals who have valued hundreds or thousands of properties bring pattern recognition and expertise that newer professionals lack.
Professional reputation is important. References from past clients, online reviews, and recommendations from real estate professionals all signal quality and reliability.
Transparent methodology helps. Professionals willing to explain their approach, show the comparables they used, and discuss their reasoning inspire confidence.
No pressure or bias. Trustworthy professionals provide objective valuations regardless of whether you want them higher or lower. Professionals pushing toward predetermined conclusions are prioritizing something other than accuracy.
When seeking a valuation, ask about the professional’s qualifications, experience, and methodology. Don’t simply accept the first estimate; compare perspectives from multiple qualified professionals if the stakes are high.
Common Valuation Mistakes and How to Avoid Them
Several common mistakes can compromise valuation accuracy or create problems for sellers later.
Failing to disclose known issues undermines the valuation’s reliability. If you know about roof problems, foundation concerns, or other issues, full disclosure helps professionals conduct accurate valuations and prevents surprises during buyer inspections.
Overstating recent improvements without documentation weakens the valuation. Professional-quality work with receipts and permits carries more weight than claimed improvements without evidence.
Expecting valuations to match emotional attachment. A home may feel worth a certain amount to you, but market value is determined by comparable sales, not personal attachment. Objective assessment requires acknowledging market reality.
Neglecting home presentation. A dirty, cluttered home creates unfavorable impressions affecting valuation. Preparation costs nothing compared to potential impact on assessed value.
Arguing with the professional. If you disagree with a valuation, ask questions and understand the reasoning. Arguing won’t change the professional’s assessment if it’s grounded in market data.
Using outdated valuations. Market conditions change. A valuation from a year ago may not reflect current conditions. Get current valuations when market conditions have shifted significantly.
Assuming online tools replace professional valuations. Online estimates provide ballpark figures but lack the detailed analysis and market knowledge of professional valuations.
Avoiding these mistakes ensures that your valuation is accurate, defensible, and useful for decision-making.
Frequently Asked Questions
How long does a property valuation take?
Most residential property valuations require 30 minutes to an hour on-site. The professional may need additional time in the office to prepare the report, typically one to three business days. From scheduling to receiving the report, expect a one-to-two-week turnaround.
How much does a professional property valuation cost?
Valuation fees vary by location and professional, typically ranging from $300 to $500 for residential properties. Some professionals provide free consultations or pricing opinions. C-REPS professionals’ fees reflect their training and certification. Compare fees but prioritize professional qualification over price alone.
Can I get a free valuation instead of paying for a professional one?
Buyer’s agents sometimes provide free “comparative market analyses” to encourage listing with them. These have value for pricing guidance but lack the objectivity and detailed analysis of independent professional valuations. For significant financial decisions, professional valuation fees are worthwhile investments.
Do I need to be home during the valuation?
Being present is helpful, as the professional may ask questions about improvements, maintenance history, or the home’s features. However, some professionals prefer clients not be present to avoid bias. Confirm the preference when scheduling.
Will the valuation affect my property taxes?
No. Property valuations for sale pricing or refinancing decisions are separate from property tax assessments. Your local assessor determines property values for tax purposes through different methodologies, typically on a multiyear cycle.
What if I disagree with the valuation?
Discuss your concerns with the professional. They can explain their reasoning, show comparable sales used, and discuss factors affecting the valuation. If you still disagree, you can obtain a second valuation for comparison. However, if multiple qualified professionals reach similar conclusions, the market is likely telling you something about your home’s value.
Is a valuation the same as what my home will sell for?
A valuation estimates market value based on current conditions and comparables. The actual sale price depends on buyer demand, market conditions, listing pricing, marketing effectiveness, and negotiations. The valuation provides a baseline; the actual price may be higher or lower depending on these factors.
How do I know if a valuation is accurate?
Accurate valuations are grounded in recent comparable sales, systematic analysis, and current market conditions. If the valuation significantly exceeds all recent comparable sales without justification, it’s likely optimistic. If it’s significantly below comparable sales, it’s likely conservative. The most accurate valuations typically fall within the range of recent comparable sales with appropriate adjustments.
Should I get a valuation before listing my home?
Yes. A pre-listing valuation helps determine an appropriate listing price, positions you for a faster sale, and prevents overpricing that extends your time on market. The valuation’s cost is trivial compared to the expense of holding an overpriced property.
Can I use an appraisal from a refinance instead of getting a separate valuation?
Possibly, but appraisals are conducted for lender purposes and may not align perfectly with market pricing for sale purposes. The lender’s appraisal is designed to protect the lender, not to establish optimal listing prices. A current valuation specifically for sale pricing is preferable if you’re planning to sell soon.
Selling Your Home During Market Downturns: Accurate Pricing Strategy
Market downturns create anxiety for home sellers. When property values are declining, inventory is rising, and buyer interest seems to be shrinking, the pressure to make the right decision intensifies. Yet this is precisely when accurate pricing becomes not just important, but critical to your success.
The fundamental truth about selling during market downturns is simple: pricing accuracy matters more than ever. An overpriced home sits unsold while the market continues to soften. An underpriced home sells quickly, but you leave money on the table. Finding the precise middle ground requires more than intuition or guesswork. It requires professional market expertise grounded in current data and systematic analysis.
This guide walks you through intelligent pricing strategies for selling your home during market downturns. We’ll explore how to think about value during uncertain conditions, how to work with professionals who understand today’s actual market, and how to position your home competitively while protecting your financial interests.
Understanding Market Downturns and Property Values
A market downturn doesn’t mean all properties lose equal value. It doesn’t mean your home is suddenly worth less than you paid. It means the market is shifting, buyer demand is changing, and the pricing dynamics that worked last year may not work this year.
During downturns, several factors converge:
Reduced buyer demand means fewer active buyers competing for properties. Homes that would have attracted multiple offers in a hot market now face a more selective audience.
Longer time on market becomes the norm. Properties that sold in days now take weeks or months to find the right buyer at the right price.
Increased inventory means sellers are competing against more alternatives. Buyers have choices, which shifts negotiating power in their favor.
Changing buyer priorities emerge as financing becomes tighter and buyers focus more carefully on true value. A home’s condition, location, and functionality become more important than speculative appreciation potential.
Price pressure on similar properties creates a new price ceiling. What sold for $450,000 a year ago may now realistically sell for $420,000, depending on market conditions and the specific property.
These realities don’t mean catastrophe. They mean adaptation. Sellers who price accurately and position their homes strategically still sell successfully during downturns. Those who cling to aspirational pricing or outdated comparables get trapped in the market, holding unsold properties while conditions continue to shift.
Why Accurate Pricing Is Your Most Powerful Tool
During strong seller’s markets, pricing mistakes are often forgiven. Underpricing slightly? Your home sells fast anyway, and you kick yourself. Overpricing moderately? Multiple offers bring the price up regardless. The market forgives imprecision.
Market downturns have zero tolerance for pricing mistakes. Your pricing decision determines whether your home attracts serious buyer interest or sits ignored.
Accurate pricing during downturns accomplishes multiple objectives simultaneously:
Attracts qualified buyer attention. Homes priced realistically get viewed by active buyers. Overpriced homes accumulate dust.
Generates negotiating momentum. When a property is priced right, buyers see value and negotiate from a position of genuine interest rather than skepticism about the asking price.
Accelerates sales timeline. Realistic pricing means your home is competing with other accurate properties. You’re fighting for attention based on condition and location rather than battling a pricing disadvantage.
Protects your equity. Yes, prices are declining. But accepting realistic valuation protects you from being trapped in a long, expensive holding period while you wait for a buyer willing to overpay.
Positions you for multiple offers. Even in downturns, homes priced right can generate multiple offers. Multiple offers even at lower prices create negotiating leverage you wouldn’t have with a single lowball offer on an overpriced property.
The core insight: accurate pricing is not settling for less. It’s understanding the real market and positioning your home to achieve the highest realistic price in current conditions.
How Market Downturns Change Valuation Methodology
During strong markets, comparable sales methodology works straightforwardly. You look at what similar homes sold for recently and adjust for minor differences. Comparable sales typically cluster tightly around recent prices.
Market downturns scatter comparable sales. Recent sales made at higher prices become historical curiosities. Current listings haven’t sold yet. Pending sales may not close. The question becomes: what are homes actually selling for today in current market conditions?
This is where C-REPS professionals’ training and certification become invaluable. Standard real estate agents may rely on outdated comparables or personal hunches. C-REPS professionals are trained in systematic valuation methodology designed specifically to address market complexity and uncertainty.
Current market analysis becomes crucial. C-REPS professionals focus on what homes are actually selling for in current conditions, not what they sold for six months ago.
Seasonal adjustments matter more. Summer sales may differ significantly from winter sales. Professional analysis accounts for seasonal factors systematically.
Market absorption rate informs pricing. How many homes are selling per month? How long is the average time on market? These data points inform realistic pricing expectations.
How to Choose a Real Estate Agent: Why C-REPS Certification Matters
Choosing a real estate agent is one of the most important decisions a homeowner can make, yet most people approach it with remarkably little diligence. They might ask a friend for a recommendation, search for an agent online, or meet with whoever answers the phone first. This casual approach frequently results in working with someone who is primarily focused on closing a deal quickly rather than serving the client’s genuine interests.
The reality is that real estate agents operate with varying levels of expertise, professionalism, and commitment to accuracy. A real estate license ensures someone has passed a basic exam and met minimum requirements. But the license says nothing about an agent’s skill at pricing a home, understanding market conditions, or prioritizing client welfare over commission speed.
This is where professional certification becomes essential. When you choose a real estate agent, you should be looking for someone who has gone beyond basic licensing to demonstrate specialized expertise and commitment to professional excellence. C-REPS certification is one meaningful way to identify that level of professional commitment.
This guide walks you through what to look for when selecting an agent, how to evaluate credentials, why C-REPS certification matters, and what questions to ask before making your decision.h
Why Agent Selection Matters So Much
The agent you select influences nearly every aspect of your real estate transaction. They recommend a price for your home (which affects your final proceeds), they market your property to potential buyers, they negotiate on your behalf, and they shepherd the transaction through closing. An excellent agent can add significant value. A mediocre agent can cost you money and time.
Consider pricing alone. If an agent overprices your home by 5 percent to 10 percent to win your listing, that overpricing frequently results in the home sitting unsold, requiring price reductions, and ultimately selling for less than it would have sold for at the correct price from day one. The financial damage easily exceeds any commission difference between agents. Similarly, if an agent underprices your home out of excessive caution or incomplete market analysis, you lose money on the sale.
Beyond pricing, your agent’s negotiating skill, communication style, and follow-through on details affect the outcome. A professional agent catches issues during inspections that others miss, including paint considerations that may affect a property’s condition and perceived value. They identify contingencies that matter for your situation.
They communicate clearly with buyers and handle conflicts professionally.
Choosing well matters. Choosing poorly is expensive.
Understanding Agent Credentials: More Than Just a License
A real estate license is a minimum credential, not a professional achievement. Think of it like a driver’s license. Having one proves you passed a test and understand basic rules. It does not make someone a professional driver, a skilled negotiator, or an expert in any specific area of real estate.
Professional certifications go further. They indicate that someone has completed specialized training, passed more rigorous exams, committed to continuing education, and agreed to professional standards beyond basic licensing requirements.
Real Estate License: The Baseline
A real estate license is necessary but not sufficient. All agents must hold one to practice. Requirements vary slightly by state, but typically include coursework covering property law, contracts, ethics, and local regulations, plus passing a state exam.
What a license does not require:
- Specialized knowledge in any area of real estate
- Continuing education after initial licensing (in some states)
- Demonstrated competence in pricing, negotiation, or client service
- Professional accountability beyond basic legal requirements
- Membership in any professional organization
Professional Designations: The Differentiation
Professional designations, by contrast, require ongoing commitment. C-REPS certification through NABPOP is one example. Other examples include Accredited Buyer’s Representative (ABR), Certified International Property Specialist (CIPS), or Seniors Real Estate Specialist (SRES).
These designations all share common characteristics:
- Specialized training beyond basic licensing
- Rigorous examination to verify competency
- Continuing education requirements
- Professional code of ethics
- Accountability and disciplinary procedures
- Membership in a professional organization
When an agent holds one of these designations, they have demonstrated commitment to specialized expertise and agreed to ongoing professional development.
What C-REPS Certification Actually Means
C-REPS certification is specifically focused on one critical competency: accurate property pricing. In an industry where pricing mistakes can cost tens of thousands of dollars, having an agent certified in pricing methodology and market analysis is a significant advantage.
To earn and maintain C-REPS certification, professionals must:
Complete Specialized Training
Coursework goes deep into valuation methodology, comparative market analysis, market trend analysis, and the psychological and ethical dimensions of pricing recommendations. This is not generic real estate education. It is focused specifically on the skills and knowledge required to price properties accurately.
Pass Rigorous Examinations
After training, candidates face comprehensive written exams testing their understanding of pricing principles, methodology, and professional standards. These exams are designed to be challenging, not to be easily passed.
Meet Performance Standards
To maintain certification, agents must complete a minimum number of valuations annually and demonstrate accuracy in their pricing. This creates ongoing accountability. An agent cannot simply earn the credential once and coast.
Pursue Continuing Education
Markets change, technology evolves, and professional standards shift. Certified agents are required to complete ongoing professional development to keep their credentials current.
Adhere to Professional Ethics
Members agree to a detailed code of conduct covering honesty in pricing, conflict of interest disclosure, client confidentiality, and fair dealing. Violations can result in removal from the certification program.
What this means in practice: A C-REPS certified agent has invested significantly in developing expertise in accurate pricing. They have demonstrated that expertise through examination. They have agreed to maintain that expertise through ongoing education. And they have accepted accountability to professional standards.
Red Flags: What to Avoid When Choosing an Agent
Before discussing what to look for, understand what warns you away from an agent. These red flags suggest an agent prioritizes speed and commission over client service and accuracy.
“I’ll list it at whatever price you want”
This is perhaps the most dangerous statement an agent can make. Professional agents provide pricing recommendations based on market analysis, not client wishes. If an agent simply agrees with any price you propose, they are not providing professional expertise. They are enabling a potentially costly mistake.
Vague Pricing Methodology
If an agent cannot clearly explain how they arrived at their price recommendation, be concerned. Professional agents can walk you through the comparable properties they selected, the adjustments they applied, and the market conditions they considered. If the explanation is vague or hand-wavy, the analysis probably is too.
No Written Analysis
Any reputable agent should provide a written Comparative Market Analysis (CMA) you can review. If they give you a verbal estimate without documentation, they are not following professional standards.
Reluctance to Share References
Most professionals will provide references from recent clients. If an agent is unwilling or defensive about sharing references, that is a warning sign.
Emphasis on Quick Deals
Language that emphasizes speed (“We’ll get this sold fast”) rather than accuracy (“We’ll price it correctly and find the right buyer”) suggests misaligned priorities. Real estate is not a race. Accuracy and good outcomes matter more than speed.
High Agent Turnover
If you research an agent and find they have been with multiple brokerages in a short time or consistently change teams, this suggests instability or issues with their work.
Lack of Local Market Knowledge
An agent should be able to speak knowledgeably about your specific neighborhood, recent sales, buyer demand, and local conditions. If they seem unfamiliar with your area or default to vague generalizations, they lack the local expertise that matters.
No Professional Affiliations
While not every good agent holds a certification, most professionals belong to industry organizations or hold meaningful credentials. Complete absence of professional involvement suggests a casual approach to the business.
What to Look For: Characteristics of Professional Agents
Now shift to what you should actively seek when evaluating agents.
Professional Credentials Beyond Basic License
Look for designations that demonstrate specialized training and ongoing commitment. C-REPS certification is one example. So are ABR, CRS (Certified Residential Specialist), or other recognized designations. These are not absolute requirements, but they are positive indicators of professional commitment.
Detailed Pricing Analysis
The agent should provide a thorough written Comparative Market Analysis. This document should explain the methodology, list comparable properties with sale prices and adjustment justifications, discuss market conditions, and present a clear price recommendation. You should be able to understand and question every aspect of it.
Local Market Knowledge
A professional agent should be able to discuss your neighborhood with specificity. They should know recent sales, understand buyer demand patterns, and be familiar with the local factors that affect pricing (school boundaries, proximity to amenities, neighborhood trajectory).
Clear Communication
Professional agents explain their reasoning clearly, without jargon, and are willing to answer questions. They do not get defensive about pricing recommendations. They explain both opportunities and risks in your market.
Transparency About Process
They should clearly outline the listing process, explain timelines, discuss marketing plans, and be explicit about what they will and will not do. No surprises or hidden assumptions.
Multiple Sales or Valuations
An agent should have an active portfolio of current clients and recent transactions. This gives them current market knowledge and demonstrates they are actually doing business, not just licensed but inactive.
Professional Affiliations
Membership in the National Association of Realtors (NAR), state real estate associations, and local boards is standard. Additional affiliations with organizations focused on specific competencies suggest deeper professional commitment.
Willingness to Adapt to Your Needs
Different clients have different priorities. A professional agent listens to what matters to you and tailors their approach accordingly, rather than applying a one-size-fits-all process.
Questions to Ask Before Hiring an Agent
Use these questions to evaluate an agent’s professionalism and expertise before you commit to working together.
“Walk me through your pricing methodology. What comparables did you select and why?”
Listen for specificity. Do they explain their comparable selection process clearly? Can they justify why certain properties were chosen? Vague answers suggest vague methodology.
“How do you adjust for differences between comparable properties and mine?”
This tests whether they understand the principle of adjustment and can articulate it clearly. A professional can explain how they value specific features based on actual market data.
“What is your track record on pricing accuracy?”
Ask directly: What percentage of homes you list sell at or very close to the listing price? How often do listings need price reductions? Professional agents track this and can demonstrate a strong accuracy record.
“Are you C-REPS certified, and if not, what specialized training or credentials do you hold in pricing and market analysis?”
This establishes whether they have professional certification and what their qualifications are. C-REPS is one meaningful credential, but other designations are also valuable.
“Can I review a sample CMA you have prepared?”
Ask to see an actual Comparative Market Analysis (with client information removed). This shows you how they work and allows you to evaluate the quality and thoroughness of their analysis.
“What is your marketing plan for my property?”
Professional marketing goes beyond just posting to the MLS. It should include professional photos, virtual tours if appropriate, targeted advertising, and open house strategy. Listen for how they plan to reach potential buyers.
“How often will we communicate, and how will you keep me informed about buyer interest and market conditions?”
A professional agent maintains regular communication. They do not leave clients wondering how their home is performing.
“How long have you been actively practicing real estate, and what has your experience been in my specific market?”
Experience matters, but local market experience matters more. Someone active for five years in your neighborhood is more valuable than someone with twenty years in a different market.
“If I disagree with your pricing recommendation, how would you handle that?”
Listen for whether they stand firm on professional recommendations or simply cave to client pressure. A professional explains their reasoning clearly but ultimately honors your decision, even if they believe it is a mistake.
“What happens if my home does not sell as quickly as expected?”
This reveals their process for monitoring market conditions and adjusting strategy. Do they have a systematic approach, or do they just wait and hope?
“Can you provide references from clients you have worked with in the past year?”
Any professional should be happy to provide references. If they are reluctant or defensive, that is a warning sign.
The C-REPS Advantage: What Certification Delivers
When you work with a C-REPS certified agent, you gain several specific advantages beyond what a typical agent provides.
Systematic Pricing Methodology
Every C-REPS professional follows a trained, tested approach to pricing. This consistency means you receive analysis that follows professional standards, not individual whim or guesswork.
Access to Network Knowledge
C-REPS is a collaborative network. When you hire one certified agent, you gain access to the collective expertise of the entire network. Complex pricing questions benefit from shared knowledge and experience.
Ongoing Professional Development
Certification requires continuing education. This means your agent stays current with market trends, new valuation technology, and evolving best practices. They do not coast on knowledge from five years ago.
Accountability to Professional Standards
Members are accountable to NABPOP and the professional community, not just to individual clients. Professional standards create incentive to do quality work and consequences for cutting corners.
Demonstrated Expertise in Pricing
The certification specifically validates expertise in the area that matters most for sellers and buyers. It is not a general real estate credential. It is focused on the one thing that affects financial outcomes most directly: accurate pricing.
Ethical Commitment
C-REPS members agree to a detailed code of ethics that prioritizes accuracy and client welfare. This creates alignment between their incentives and your interests.
Comparing Agents: A Quick Evaluation Framework
When you are down to interviewing multiple agents, use this simple framework to compare them side by side.
| Factor | Agent A | Agent B | Agent C |
| Years active in local market | |||
| C-REPS certified or other designation | |||
| Percentage homes sold at or near list price | |||
| Can explain pricing methodology clearly | |||
| Provides written CMA | |||
| References available | |||
| Active number of current listings | |||
| Marketing plan detail and sophistication | |||
| Communication frequency and style | |||
| Local market knowledge demonstrated |
This framework helps you evaluate comparable professionals on consistent criteria rather than being swayed by personality or sales pitch.
Making Your Final Decision
After you have evaluated multiple agents, step back and consider the complete picture. The least expensive agent is not necessarily the best value. The most personable agent is not necessarily the most professional. The agent with the most listings is not necessarily the one who will serve you best.
Look for someone who combines:
- Professional credentials and demonstrated expertise
- Clear, systematic methodology you can understand and evaluate
- Local market knowledge specific to your area
- Transparent communication
- Professional accountability
- Alignment between their incentives and your interests
The agent you choose will influence your financial outcome significantly. Invest time in the selection process. Ask tough questions. Verify credentials. Check references. The small investment of diligence in choosing well pays dividends in the execution.
Frequently Asked Questions
What is the most important credential for a real estate agent to have?
While real estate licensing is required, looking for additional professional credentials like C-REPS certification demonstrates specialized expertise and commitment to continuing education. These designations indicate an agent has gone beyond minimum requirements and maintains professional standards.
How do I verify that an agent’s C-REPS certification is legitimate?
You can verify C-REPS certification through NABPOP’s directory or by asking the agent for their certification documentation. Legitimate certifications are publicly verifiable and can be confirmed through the issuing organization.
Is a C-REPS certified agent required, or are there other qualified options?
C-REPS certification is one way to identify expertise in pricing and market analysis, but other professional designations also indicate commitment to professional development. The key is looking for agents who have pursued additional training and maintain professional standards beyond basic licensing.
What should I do if the agent I want to hire does not have professional certification?
If an agent does not have certification, ask them directly about their specialized training, their track record on pricing accuracy, and their methodology. An uncertified agent can still be professional and competent, but you should verify their qualifications carefully.
How much difference does agent selection really make on my real estate outcome?
Agent selection influences pricing accuracy, marketing effectiveness, negotiation skill, and overall transaction management. These factors collectively can easily result in a tens-of-thousands-of-dollars difference in your outcome. Selection matters significantly.
What if my agent’s price recommendation is much higher or lower than I expected?
Ask them to walk through their analysis in detail. Review the comparables they selected and the adjustments they applied. A professional agent can explain and defend their recommendation. However, their market-based analysis should be weighted heavily in your decision.
Should I use an agent who specializes in my neighborhood versus someone with broader market experience?
Hyperlocal specialization is valuable because agents develop deep knowledge of specific neighborhoods. However, broader market experience can also be valuable for perspective. Look for someone with strong knowledge of your specific area specifically, whether that comes from deep specialization or strong general experience in the market.
What red flags should make me immediately stop considering an agent?
Be cautious about agents who agree with any price you propose, cannot explain their methodology clearly, do not provide written analysis, are vague about the process, or seem focused on speed over accuracy. These suggest misaligned priorities.
How long should I commit to working with an agent if the listing is not selling?
Most listing agreements run for 90 days. If your home is not selling as expected, you should have a clear discussion with your agent about why, what market conditions suggest, and whether pricing adjustment makes sense. Evaluate the situation professionally, not emotionally.
Can I change agents mid-process if I am unhappy with performance?
Listing agreements typically allow you to terminate, though you may be bound through a certain date. Review your agreement and discuss with your agent if you have concerns. However, changing agents disrupts the process, so resolve concerns directly with your current agent if possible.
Choosing Your Real Estate Partner
Selecting a real estate agent is not a casual decision. This person will represent you in one of the largest financial transactions of your life. They will provide advice that affects your outcome significantly. They will negotiate on your behalf.
Choose someone who brings professional expertise, systematic methodology, local knowledge, and genuine commitment to your interests. Look for professional credentials like C-REPS certification. Ask tough questions. Verify qualifications. Check references.
The small investment of diligence in agent selection pays substantial dividends in outcome. A professional agent who prioritizes accuracy and client welfare will serve you far better than a well-liked but unaccountable agent who prioritizes quick commission.
Ready to select a real estate partner you can trust? Connect with a C-REPS certified agent who combines professional expertise with commitment to accurate pricing and client partnership.
Market Conditions Impact on Property Pricing: 2026 Insights
The real estate market has never been static, and 2026 is no exception. Property pricing doesn’t exist in a vacuum: it’s shaped by economic forces, interest rates, housing supply, buyer demand, and broader financial conditions that shift like weather patterns. Understanding these dynamics is critical whether you’re selling a home, buying investment property, or simply trying to understand what your home is actually worth today.
This guide explores how current market conditions are influencing property pricing in 2026, providing the insights you need to make informed decisions about your real estate decisions. C-REPS professionals, certified real estate pricing specialists, use this kind of market analysis every day to deliver accurate pricing for their clients.
What Are Market Conditions?
Market conditions represent the aggregate of economic, financial, and local factors that influence buyer behavior, seller motivation, and ultimately, property values. They’re not abstract concepts: they directly impact the price buyers are willing to pay for homes in your neighborhood today.
Key market condition factors include:
- Interest rates and mortgage availability
- Housing inventory levels
- Job growth and economic activity
- Population migration patterns
- Days on market and buyer competition
- Loan approval rates and lending standards
- Consumer confidence and economic outlook
- New construction rates and development activity
When you hire a C-REPS professional to price your home, they’re not just looking at comparable sales from six months ago. They’re analyzing these real-time conditions to determine what buyers in your actual market will pay right now.
How Interest Rates Shape Property Values
Interest rates remain one of the most powerful forces in real estate pricing. When mortgage rates rise, buying power decreases: a buyer approved for a $400,000 home at 4% interest may only qualify for a $320,000 home at 6% interest. The property hasn’t changed, but the market’s ability to absorb it at high prices has shifted dramatically.
In 2026, interest rate movements continue to create pricing volatility. Higher rates reduce demand, which can pressure prices downward in some markets. Lower rates stimulate demand and can accelerate price growth. C-REPS professionals monitor these shifts constantly because they directly affect their clients’ bottom lines.
Mortgage Rate Sensitivity
Properties are most vulnerable to rate-driven price adjustments in the first 3-6 months after rate increases. Initial buyers price in the higher borrowing costs, but sellers often lag in adjusting their expectations. This creates a pricing gap where homes remain overpriced relative to what buyers can actually afford.
CREPS pricing specialists bridge this gap by helping sellers understand that their home’s value today isn’t what a buyer could have paid in a lower-rate environment. It’s what they’ll pay in the current market.
Housing Inventory and Pricing Dynamics
The relationship between supply and demand drives nearly every market dynamic. Low inventory with high demand creates seller’s markets where prices tend to rise. High inventory with moderate demand creates buyer’s markets where pricing becomes more competitive.
Current Inventory Landscape
Many markets entering 2026 continue to experience inventory challenges, though this varies significantly by geography. Coastal markets and major metro areas face persistent housing shortages, while some secondary markets have seen inventory normalization. This geographic variation means property pricing isn’t national; it’s hyperlocal.
A C-REPS professional in your market knows whether your neighborhood has 2.5 months of inventory or 8 months of inventory. That knowledge determines whether your home is priced in a competitive or negotiable market. It matters.
Economic Conditions and Buyer Confidence
Strong employment, wage growth, and consumer optimism support higher property valuations. Conversely, economic uncertainty, job market softening, or recession concerns can compress prices across most property types. Buyers become more selective and cautious when economic headwinds appear.
In 2026, economic conditions vary regionally. Markets with strong job creation and wage growth typically support stable or appreciating property values. Markets experiencing workforce uncertainty or industry disruption often see pricing pressure.
Local Economic Drivers
- Tech sector health and major employer announcements
- Unemployment rates relative to national average
- Wage growth and cost-of-living increases
- Population migration into or out of the region
- New business formation and startup activity
Population Migration and Demographic Shifts
Migration patterns reshape property pricing faster than almost any other factor. Regions attracting young professionals, families, or remote workers experience rising demand and typically upward price pressure. Regions experiencing outmigration face opposite dynamics.
The pandemic accelerated remote work adoption, changing where people choose to live. Some of these patterns have stabilized into new normal patterns, while others continue to evolve. A home’s value is shaped partly by whether it’s in an “attracting” or “declining” region.
Days on Market and Pricing Reality
Days on market (DOM) is one of the most honest pricing indicators. Properties that sell quickly suggest underpricing. Properties that linger on the market for 60+ days often indicate overpricing or market resistance.
C-REPS professionals use DOM data strategically. If comparable homes in your neighborhood average 25 days on market but are priced 5% higher than your home, that pricing difference reflects genuine market demand. If homes are averaging 45 days on market, sellers often need to adjust expectations downward.
Real Estate Pricing Trends in 2026
Appreciation Patterns
Property appreciation rates have moderated significantly from pandemic-era extremes. Instead of 15-25% annual appreciation, many markets are seeing 2-5% annual changes, with some experiencing flat or declining values. This normalization actually creates opportunity for educated buyers and more realistic markets for sellers.
Price Differentiation
Properties are increasingly differentiated based on specific attributes:
- Energy efficiency and sustainability features
- Layout and home office suitability
- Proximity to quality schools and amenities
- Move-in readiness versus renovation requirements
- Lot size and outdoor space
- HOA costs and community features
A home that “checks boxes” commands pricing premiums. One with significant drawbacks faces pricing discounts.
Regional Performance Variation
Sunbelt markets continue attracting migration and typically support higher pricing growth. Midwest and secondary market properties often appreciate more slowly. Coastal markets face affordability challenges that can cap price appreciation even with strong demand.
How C-REPS Pricing Specialists Analyze Market Conditions
C-REPS professionals use systematic approaches to translate market conditions into accurate property pricing:
Market Data Analysis: Analyzing 30-90 days of comparable sales within specific geographic boundaries, adjusting for property differences systematically.
Trend Identification: Identifying whether the market is appreciating, depreciating, or stable over rolling periods.
Buyer Motivation Assessment: Understanding whether comparable sales represent true market value or distressed sales that skew the pricing picture.
Days on Market Adjustment: Accounting for selling speed when evaluating comparable properties, since quick sales often indicate underpricing.
Seasonal Adjustment: Recognizing that spring market pricing differs from winter market pricing and adjusting analysis accordingly.
Economic Correlation: Connecting local economic conditions, employment data, and demographic trends to pricing trajectories.
This systematic approach distinguishes C-REPS professionals from agents who simply run an automated valuation model and hope for accuracy.
Factors Affecting Pricing in Different Market Conditions
Seller’s Markets (Low Inventory, High Demand)
In seller’s markets, pricing power increases for sellers. Properties often sell above asking, appreciate faster, and attract multiple offers. However, overpricing still occurs: sellers sometimes confuse strong market conditions with permission to price unrealistically.
Buyer’s Markets (High Inventory, Moderate Demand)
Buyer’s markets reward realistic pricing. Homes priced competitively attract more interest, showings, and offers. Overpriced homes stagnate, creating the “days on market penalty” that actually reduces net proceeds for sellers.
Balanced Markets (Normalized Inventory and Demand)
Balanced markets are increasingly common in 2026. These markets reward pricing accuracy most obviously, correct pricing leads to quick sales and reasonable net proceeds, while incorrect pricing creates friction.
Impact on Home Sellers
Accurate market condition assessment is essential for sellers because pricing determines:
- How quickly the property sells
- How many showings and offers you receive
- Whether you negotiate from strength or weakness
- Net proceeds after commissions and costs
- Psychological impact of living with an overpriced listing
An overpriced home sitting on the market for 60 days doesn’t just cost time: it creates stigma. New buyers wonder why previous showings didn’t result in offers. The home becomes less attractive even as price reductions occur. Professional market analysis from a C-REPS specialist prevents this dynamic.
Impact on Home Buyers
Buyers benefit from understanding market conditions because this knowledge:
- Reveals whether negotiation room exists
- Identifies underpriced properties before competition discovers them
- Indicates whether it’s wise to act quickly or wait for more selection
- Suggests likely future appreciation or depreciation trends
- Highlights whether current pricing supports long-term wealth building
A buyer who understands that their target market has 7 months of inventory knows they can wait for a better property rather than bid against other buyers.
Investment Property Pricing in 2026
Investment property pricing diverges from primary residence pricing in important ways. Investors price based on cash flow, cap rates, and return metrics rather than emotion or personal preference. In 2026, cap rate compression has created challenges for some investors while opportunities exist for cash-flowing properties in emerging markets.
C-REPS professionals who specialize in investment property bring specific expertise in analyzing rental markets, expense ratios, and return calculations that owner-occupied property specialists may not emphasize.
Forecasting Property Pricing
Predicting future property pricing requires analyzing:
- Current economic trajectory and interest rate expectations
- Housing supply pipeline (new construction rates)
- Migration patterns and population projections
- Employment growth forecasts
- Demographic trends (millennial household formation, Gen Z homebuying)
These factors suggest different pricing trajectories for different markets. Some markets likely appreciate 3-5% annually. Others may appreciate 0-2% or potentially experience slight depreciation if economic conditions shift.
Important caveat: No one accurately predicts property pricing over multi-year periods. However, understanding current conditions and trajectories helps buyers and sellers make better decisions within a 1-3 year timeframe.
The C-REPS Advantage in Pricing Accuracy
C-REPS professionals bring distinct advantages to property pricing:
Professional Certification: Training and testing ensure knowledge of pricing methodology, not just local market observation.
Systematic Approach: Using structured analysis rather than intuition reduces pricing bias.
Market Access: Working with real buyers and sellers daily, C-REPS professionals know what buyers actually pay today, not what prices existed months ago.
Network Collaboration: Access to other C-REPS professionals in adjacent markets provides comparative pricing context.
Professional Standards: Ethical standards and continuing education requirements ensure ongoing competence.
Accuracy Accountability: C-REPS designation creates professional accountability that matters when your largest financial decision is on the line.
Practical Recommendations
For Home Sellers
- Price based on today’s market conditions, not emotional valuations or aspirational pricing
- Focus on properties sold in the last 30-45 days, not older comparables
- Adjust for days on market, quick sales indicate underpricing
- Consider market absorption rate when timing your listing
- Hire a C-REPS professional who understands your local market deeply
For Home Buyers
- Understand whether you’re in a buyer’s or seller’s market before negotiating
- Get pre-approved so you know your actual buying power at current rates
- Focus on intrinsic property value, not emotional appeal
- Negotiate more aggressively in buyer’s markets, move faster in seller’s markets
- Consider future appreciation potential when evaluating long-term value
For Investors
- Analyze current cap rates and cash flow potential, not speculative appreciation
- Consider whether current pricing reflects sustainable fundamentals
- Evaluate markets with strong employment and population growth
- Account for interest rate changes in cash-on-cash return calculations
- Work with C-REPS professionals who understand investment property metrics
Frequently Asked Questions
How do rising interest rates affect property values?
Rising interest rates reduce buyer purchasing power directly. A buyer’s $400,000 affordability at 4% interest drops to approximately $320,000 at 6% interest. This reduced demand typically pressures prices downward, especially in the first 3-6 months after rate increases. However, the impact varies by market, some markets see smaller declines if inventory constraints support prices.
What is days on market and why does it matter for pricing?
Days on market (DOM) measures how long a property remains listed before going under contract. DOM indicates pricing accuracy. Properties selling in 10-15 days often suggest underpricing or strong demand. Properties selling in 45+ days typically indicate overpricing or market resistance. C-REPS professionals use DOM data to calibrate pricing expectations based on what comparable properties actually achieve.
How do I know if I’m in a buyer’s or seller’s market?
Markets are typically classified by inventory levels. Less than 4 months of inventory usually indicates a seller’s market. 4-6 months suggests a balanced market. More than 6 months suggests a buyer’s market. You can calculate this by dividing total active inventory by average monthly sales volume. Your C-REPS professional can provide exact calculations for your specific neighborhood.
What percentage appreciation can I expect in 2026?
Appreciation rates vary dramatically by market. Strong economic regions with population growth might see 3-5% appreciation. Balanced markets might see 0-3%. Markets facing economic headwinds might experience flat performance or 2-3% depreciation. Long-term appreciation assumes proper timing and market selection, individual property performance varies based on condition, updates, and specific attributes.
How do local economic conditions impact property pricing?
Strong local employment, wage growth, and business formation drive demand and typically support higher property values. Conversely, major employer relocations, industry disruption, or job market softening creates pricing pressure. Migration patterns amplify these effects, regions attracting young professionals and families appreciate faster than regions experiencing outmigration.
Should I price my home based on what I paid for it?
No. Purchase price is historical data, not a pricing indicator. Your home’s value today is determined by current market conditions, not what you paid. This is a common pricing mistake, sellers often believe their home “should” be worth more because they invested significantly or hold emotional attachment. Market conditions, not your investment, determine value.
What makes C-REPS professionals different from other real estate agents?
C-REPS professionals complete specialized training, pass certification exams, meet performance requirements, and follow enhanced professional standards through the NABPOP certification program. This distinguishes them from agents who rely primarily on experience or software valuation models. C-REPS certification indicates professional commitment to accurate pricing and client education.
How does new construction affect existing home pricing?
New construction can pressure existing home pricing if inventory increases significantly. However, new homes target specific buyer demographics, typically move-in-ready buyers willing to pay premiums for new features. Existing homes often appeal to buyers seeking value or established neighborhoods. The impact on existing home pricing depends on local dynamics, not a universal rule.
Is now a good time to sell or buy?
This depends on market conditions in your specific area and your individual situation. Buyer’s markets reward prepared buyers who can negotiate aggressively. Seller’s markets reward sellers with realistic pricing who can capitalize on demand. Balanced markets reward patience from buyers and competitiveness from sellers. Your C-REPS professional can analyze your specific situation relative to current conditions.
How should I use market condition information when pricing my investment property?
Investment properties should be priced based on cash flow and return metrics (cap rate, cash-on-cash returns), not speculative appreciation potential. Current market conditions affect achievable rents and operating expenses. Strong local employment supports rents. Competitive rental markets might compress rent growth. Your investment analysis should incorporate these conditions as they affect actual returns.
Conclusion: Making Informed Decisions in 2026’s Market
Property pricing in 2026 reflects an increasingly sophisticated market where outdated approaches yield predictable results, overpriced homes that linger, underpriced homes that leave money on the table, and buyers who miss opportunities or overpay.
Understanding market conditions removes guesswork from real estate decisions. Interest rates, inventory levels, economic health, and migration patterns aren’t abstract concepts, they directly determine what buyers will pay for your home today and what properties represent value for your purchase.
C-REPS professionals turn market condition analysis into actionable pricing strategies. Whether you’re selling, buying, or investing, working with a certified professional who understands your local market conditions delivers measurable value through accurate pricing, smarter negotiations, and better financial outcomes.
The real estate market rewards informed decisions made by people who understand current conditions. If you’re making a significant property decision in 2026, that understanding starts with connecting with a C-REPS professional who can analyze your specific situation within your actual market conditions.
How C-REPS Training Makes Agents Better at Pricing Your Home
When you’re selling your home, one decision towers above all others: the list price. Price it too high, and your home sits on the market, losing buyer interest daily. Price it too low, and you leave significant money on the table. This is where professional training separates exceptional agents from the rest.
Certified Real Estate Pricing Specialists, known as C-REPS professionals, undergo rigorous training and certification to master the science and art of home pricing. This specialized expertise doesn’t just help agents impress clients; it fundamentally changes how homes are valued and sold.
Let me show you why this training matters for your bottom line and how certified agents approach pricing differently.
Understanding C-REPS Certification
C-REPS professionals hold a credential earned through the National Association of BPO Professionals (NABPOP), which represents one of the most comprehensive professional designations in real estate today. But this certification means far more than a credential hanging on an office wall.
What C-REPS Training Covers
C-REPS training programs require agents to master multiple interconnected skills:
Market Analysis Methodology: Agents learn systematic approaches to analyzing comparable sales, understanding absorption rates, tracking days-on-market trends, and interpreting buyer behavior patterns specific to local markets.
Valuation Techniques: Rather than relying on intuition, C-REPS agents employ professional valuation methods borrowed from appraisers and market analysts, then adapt these methods with real-time buyer feedback.
Technology and Data: Certified agents receive extensive training in MLS data interpretation, predictive pricing software, market trend analysis tools, and how to extract actionable insights from raw data.
Professional Ethics and Standards: The certification requires adherence to a professional code of ethics that explicitly prioritizes client interests, prevents overpricing schemes, and emphasizes honest market assessment.
Continuing Education: C-REPS professionals must maintain their certification through ongoing education, staying current with market shifts, regulatory changes, and evolving best practices.
The certification process isn’t quick. Agents must complete specialized training, pass rigorous exams, meet performance requirements, maintain active membership, and participate in continuing education. This creates a meaningful distinction between C-REPS agents and agents with only basic real estate licenses.
Why Home Pricing Accuracy Matters More Than You Think
Accurate home pricing isn’t just about maximizing profit, though that matters. It’s about market efficiency and your peace of mind.
Overpriced homes face real consequences: Extended time on market (lingering homes receive fewer showings), buyer perception problems (long-listed homes are often perceived as having unrecognized defects), and eventual price reductions (which signal market weakness to remaining buyers and accelerate further price declines).
Underpriced homes create different problems: You miss significant equity, leaving money in the transaction for buyers to capture. One study found that 78% of homes receiving multiple offers were actually underpriced initially.
Accurate pricing activates several benefits: Competitive market situations develop, creating genuine buyer competition that drives prices higher. Homes sell faster, reducing carrying costs and market exposure risks. Buyers perceive properly priced homes as legitimate opportunities, not bargains or overreach attempts.
This is where C-REPS training creates measurable value. Certified agents use professional methodology rather than guesswork.
How C-REPS Agents Approach Home Pricing Strategy
Standard real estate training teaches agents to pull comparable properties, average their prices, and adjust up or down based on property differences. C-REPS agents operate from a more sophisticated framework.
The Systematic Approach
C-REPS pricing starts with market segmentation. Rather than looking at all homes in a zip code, certified agents break markets into specific neighborhoods, price ranges, and buyer types. A $300,000 home in an emerging neighborhood faces completely different market dynamics than a $300,000 home in an established area.
Comparable Property Selection becomes far more rigorous. C-REPS agents don’t just pull the most recent sales. They analyze:
- Properties sold in similar market conditions (rising market versus declining market creates entirely different pricing dynamics)
- Homes sold to the target buyer demographic (downsizers, first-time buyers, investors, and families face different neighborhoods and price points)
- Sales completed within appropriate time windows (market conditions shift faster in some seasons than others)
- Properties with similar days-on-market patterns (a home that sold in 3 days reflects different pricing than one requiring 45 days)
Market Trend Analysis incorporates quantitative data about buyer behavior, inventory levels, and absorption rates rather than relying on “the market feels strong right now” sentiment.
Real Buyer Feedback Integration
This is where C-REPS training reveals its practical power. Certified agents have professional networks connecting them with other agents, market data, and actual buyer responses. When a home receives feedback like “perfect neighborhood, but the price is 8% above market value,” that’s actionable intelligence that refines pricing precision.
Average agents might miss or dismiss this feedback. C-REPS agents systematise it, aggregating buyer response data to identify where market resistance points actually exist.
Technology-Enhanced Valuation
Modern C-REPS agents combine professional training with sophisticated pricing software that identifies patterns humans miss. These tools analyze hundreds of variables simultaneously: architectural features, lot characteristics, proximity factors, buyer demographic trends, and market timing effects.
The agent’s professional training teaches them how to interpret this data intelligently rather than accepting algorithmic output blindly.
The Professional Real Estate Agent Training Advantage
What separates C-REPS professionals from standard agents?
Professional Accountability: C-REPS certification comes with professional standards and ethics requirements. An agent misrepresenting a home’s market value faces professional consequences beyond client dissatisfaction, creating real incentives for honest assessment.
Deeper Market Knowledge: C-REPS agents invest in understanding their markets at professional levels. They attend market analysis meetings, review detailed data regularly, and stay current with trends that affect property values. This isn’t casual knowledge; it’s systematic expertise.
Specialized Training Beyond Licensing: A real estate license demonstrates compliance with state requirements. C-REPS certification indicates commitment to excellence beyond minimum standards. The difference parallels how a board-certified physician differs from a minimally-credentialed practitioner.
Collaborative Networks: C-REPS agents tap into professional networks where pricing insights, market intelligence, and buyer information are shared systematically. This collaborative approach reveals patterns that isolated agents never discover.
Continuous Skill Development: C-REPS requirements mandate ongoing education, ensuring certification holders stay current with market shifts and evolving practices rather than relying on outdated training.
What Actually Affects Home Price: A Professional Breakdown
Understanding what truly drives home prices helps you evaluate your agent’s pricing approach.
Quantifiable Price Drivers
Location Metrics: Proximity to employment centers, quality-rated schools, public transportation, and commercial amenities creates measurable price premiums. C-REPS agents quantify these effects rather than simply noting “great location.”
Property Characteristics: Square footage, bedroom count, bathroom configuration, and year built establish baseline pricing. However, trained agents recognize that 2,000 square feet of well-laid-out space commands different pricing than cramped 2,000 square feet.
Structural Condition: Foundation, roof condition, HVAC systems, and electrical systems represent major price factors. Professional valuation distinguishes between cosmetic updates and structural improvements.
Market Conditions: Whether inventory is rising or falling, whether days-on-market are increasing or decreasing, and whether buyer demand is strengthening or weakening creates pricing context. Markets rising 3% annually price differently than declining markets.
Harder-to-Quantify Factors
Professional agents trained through C-REPS certification understand that some price factors resist simple mathematical models.
Buyer perception and emotional appeal matter. Homes with natural light, open flow, and inviting presentation command premiums over functionally identical homes in dated configurations.
Seller motivation affects pricing psychology. Professional agents distinguish between “must sell quickly” pricing and “premium market opportunity” pricing for identical properties.
Micromarket dynamics create variations that broader data doesn’t capture. One street in a neighborhood might appreciate differently than another street three blocks away based on school district boundaries, HOA structures, or development patterns.
Getting a Fair Price When Selling: The C-REPS Advantage
When you work with a C-REPS agent, several things happen differently in your pricing process.
Comprehensive Market Analysis: Rather than a quick computer-generated valuation, expect detailed written analysis explaining pricing rationale. You should receive documentation showing comparable properties, market trend data, and specific reasoning for the recommended list price.
Documented Adjustment Methodology: Professional agents show their work. If your home is 10% above a comparable property in price, the agent should document what specific factors justify that premium.
Realistic Timeline Expectations: C-REPS trained agents provide honest assessments about how long homes typically sell at various price points in your market. They’ll explain why pricing at $375,000 might result in a sale in 18 days, while $385,000 might extend that to 45 days based on market absorption rates.
Feedback Integration Process: Throughout marketing, professional agents systematically track buyer feedback and adjust pricing strategy accordingly. If properties are receiving zero offers at the current price, data-driven agents recognize when market correction is necessary.
Competitive Positioning Strategy: Rather than just pricing your home, C-REPS agents help you understand how to position your property competitively. Should you price at market value or slightly below to generate competitive situations? The answer depends on inventory levels, buyer demographics, and market psychology.
How Professional Home Valuation Differs from DIY Estimates
Many homeowners consult online valuation tools before hiring agents. Understanding the limitations of DIY approaches reveals why professional training matters.
Automated valuation models rely on historical data and algorithmic analysis. They can’t see your home’s recent updates, current condition, or market-specific buyer preferences. Zestimate and Zillow estimates often miss by 5-15% in individual cases, even if they’re accurate on average across markets.
Professional appraisals serve lenders but follow different valuation approaches than marketing strategy. An appraiser’s value might differ from market pricing because appraisals emphasize conservative, defensible valuations that lenders will accept, while market pricing reflects what actual buyers will pay today.
Real estate agent pricing combines appraisal methodology, comparable sales analysis, buyer behavior data, and market timing. C-REPS agents bring professional expertise to this combination, using systematic approaches rather than intuition.
The Certification Testing Process Explained
Understanding what C-REPS agents must master provides confidence in their expertise.
The certification process requires comprehensive examination of pricing principles, market analysis techniques, valuation methodologies, and professional standards. Agents must demonstrate mastery across multiple domains:
- Comparable property analysis and statistical adjustment methodology
- Market trend identification and interpretation
- Buyer behavior and market psychology
- Technology platforms and data interpretation
- Professional ethics and client representation standards
- Professional standards enforcement and compliance
This isn’t a weekend seminar or online course. The testing reflects professional-level expertise in applied pricing science.
Real-World Example: How Pricing Training Changes Outcomes
Consider a 2,200 square foot colonial home in a suburban market. A standard agent might look at three comparable sales averaging $425,000, add a small adjustment for this home’s slightly better condition, and recommend $432,000.
A C-REPS trained agent would analyze substantially more data:
Comparable property selection would expand to 12-15 homes, looking across multiple submarkets to understand true market value patterns
Market trend analysis would show whether recent comparable sales represented a rising, stable, or declining market
Days-on-market data would reveal how long similar homes typically sell at various price points
Buyer demographic analysis would show whether this neighborhood attracts families, empty nesters, or first-time buyers, affecting which comps are truly comparable
Local feedback systems would include recent buyer comments: “loved this neighborhood but price is 3% high” or “strong demand, multiple showings within 48 hours”
This analysis might recommend $428,000 instead of $432,000. That $4,000 difference might generate multiple offers instead of extended market time, ultimately netting higher prices through competitive market dynamics.
Factors Affecting Home Price: The Professional Perspective
Beyond obvious factors like square footage and condition, what really moves pricing?
Buyer Pool Characteristics: Markets with strong professional employment centers price differently than markets with retirees or blue-collar workers. Buyers with different employment circumstances value features differently.
Inventory Levels and Absorption: When inventory is low and homes sell within weeks, pricing can hold firm. When inventory rises 30% year-over-year, market psychology shifts and pricing must adjust accordingly.
Seasonality and Timing: Spring markets typically see more buyer competition than winter markets. C-REPS agents understand these patterns and price strategically within seasonal contexts.
Neighborhood Trajectory: Is the neighborhood established and stable, emerging and appreciated, or declining? Each trajectory justifies different pricing approaches.
Marketing Effectiveness: Well-marketed homes at correct prices generate competition. Poorly-marketed homes or misprice homes languish regardless of actual value.
Professional agents understand these factors systematically rather than vaguely sensing that “something feels right.”
How to Evaluate Your Agent’s Pricing Expertise
If you’re considering hiring an agent, assessing their pricing sophistication matters.
Ask about their pricing methodology: Do they have a documented approach to pricing analysis, or is it intuition-based? Professional agents can explain their process in detail.
Request a detailed pricing opinion: Before hiring, ask for a written market analysis supporting their recommended list price. The depth and documentation quality reveals their professional approach.
Inquire about professional credentials: C-REPS certification or similar professional designations indicate training commitment beyond minimum licensing requirements.
Check their track record: Ask what percentage of their listings sell within the first 30 days. Ask about price-to-list-price ratios for their sales. Strong track records suggest accurate pricing.
Understand their market analysis approach: Do they pull three comps and average them, or do they conduct systematic market analysis? The sophistication of their approach matters.
Evaluate their technology and tools: Professional agents use modern data analysis tools, market trend software, and systematic feedback collection. Basic agents use spreadsheets and gut feelings.
Avoiding Common Pricing Mistakes
C-REPS trained agents help clients avoid these frequent errors.
Overpricing based on emotional attachment: Homeowners often believe their homes are worth more than market value. Professional agents deliver honest assessments grounded in data rather than emotion.
Failing to account for market conditions: Markets shift constantly. A home worth $400,000 in a rising market might be worth $380,000 six months later in a declining market. Professional agents adjust pricing for market timing.
Ignoring buyer feedback: When homes receive consistent feedback that they’re 5% overpriced, professional agents treat this as actionable data rather than negotiating noise.
Neglecting ongoing price adjustment: Markets change monthly. Professional agents monitor absorption rates and adjust pricing strategy for sustained market conditions.
Underestimating the competition: Every home competes with substitutes. Pricing must account for what competing homes offer at their price points.
The C-REPS Professional Network Advantage
One distinctive benefit of working with C-REPS agents involves network access. The professional network creates information advantages.
When you hire a C-REPS agent, you gain access not just to one professional, but to an entire network of certified specialists. This network shares market intelligence, coordinates knowledge about buyer demand patterns, and collectively maintains deeper market insight than isolated practitioners can develop.
This collaborative advantage means your agent has access to more market data, broader buyer networks, and deeper community knowledge than agents operating independently.
Key Takeaways: Why Professional Training Improves Pricing
Strong pricing relies on three elements: systematic methodology, current market data, and professional expertise in interpretation.
C-REPS training ensures agents master methodology. They follow documented processes rather than relying on intuition.
Professional networks and requirements ensure agents maintain current data. They’re incentivized to stay informed about market conditions through certification maintenance requirements.
Professional training develops expertise in interpretation. They understand not just what the data says, but what it means for pricing strategy and market positioning.
This combination produces better outcomes: homes price accurately, attract appropriate buyer pools, sell efficiently, and achieve fair market value.
Frequently Asked Questions
What does C-REPS certification actually mean?
C-REPS stands for Certified Real Estate Pricing Specialists. Agents holding this credential have completed specialized training through the National Association of BPO Professionals (NABPOP), passed comprehensive exams, met performance standards, and committed to continuing education. It distinguishes agents who specialize in accurate pricing from agents with only basic real estate licenses.
How much does C-REPS training improve pricing accuracy?
Studies indicate that C-REPS trained agents achieve significantly better price-to-list-price ratios (typically 96-98% of list price versus 92-95% for untrained agents) and reduce days-on-market by 20-30% on average. Accuracy improves because systematic methodology outperforms intuition-based approaches.
How often should homes be repriced during a listing?
Professional agents monitor market conditions continuously and adjust pricing when market data suggests change. Most systematic approaches recommend pricing review every two to four weeks when market conditions shift (inventory changes, absorption rates shift, or buyer feedback patterns change). Homes sitting without offers for 30+ days often need price correction.
What’s the difference between an appraisal and a professional market opinion from an agent?
Appraisals serve lender requirements and emphasize conservative, defensible valuations. Professional pricing opinions focus on what actual buyers will pay in current market conditions. C-REPS agents consider appraisal methodology but apply it for market pricing rather than lending standards, often resulting in different recommendations.
Can technology replace professional pricing expertise?
Pricing software provides valuable data, but interpretation requires professional judgment. Technology identifies patterns; professionals understand what those patterns mean for pricing strategy. The best results combine technology-generated insights with professional interpretation.
How should I respond if my agent recommends pricing below my expectations?
Professional agents ground pricing recommendations in documented market data. If your agent recommends lower pricing than you expected, request detailed analysis showing comparable properties, market trends, and buyer feedback supporting the recommendation. Data-driven recommendations, even if unwelcome, typically produce better outcomes than inflated pricing.
Does neighborhood reputation affect pricing beyond measurable factors?
Yes. Buyer perception of neighborhoods creates pricing effects beyond school ratings and income statistics. Some neighborhoods have strong buyer demand that supports premium pricing; others face perception challenges that suppress prices below statistical models predict. C-REPS agents understand these micromarket dynamics through local market knowledge.
What role does marketing play in achieving top prices?
Professional pricing assumes proper marketing. Excellent marketing generates qualified buyer traffic, which justifies competitive pricing. Poor marketing requires aggressive pricing to generate any buyer interest. Your agent should explain how their marketing strategy connects to pricing recommendations.
What C-REPS Certification Means for Real Estate Professionals
When you’re buying or selling a home, few decisions matter more than choosing the right agent. But how do you know which professionals truly have the expertise to guide your most important financial transaction? That’s where professional credentials like C-REPS come in.
The real estate industry attracts professionals across a wide spectrum of experience and commitment. While anyone with a license can call themselves a real estate agent, certified professionals who hold specialized credentials demonstrate a measurable commitment to expertise, market knowledge, and ethical practice. Understanding what these credentials represent helps you make more informed decisions about who to trust with your property.
C-REPS (Certified Real Estate Pricing Specialists) represents one of the most significant professional certifications in the industry, particularly for sellers and buyers who need accurate, data-driven pricing strategies. But what exactly does this certification mean, and why should it matter to you?
What is C-REPS Certification?
C-REPS stands for Certified Real Estate Pricing Specialists. It’s a professional designation earned by real estate agents and brokers who have completed specialized training, passed rigorous certification exams, and committed to ongoing professional development and ethical standards.
The certification is administered through the National Association of BPO Professionals (NABPOP), a recognized credentialing body that sets standards for real estate professionals focused on pricing accuracy and market expertise. Unlike a simple real estate license, which is a legal requirement to practice, C-REPS certification is a voluntary professional achievement that signals additional expertise and dedication.
Professionals who earn C-REPS credentials are not appraisers. Instead, they’re active real estate agents and brokers who combine systematic professional training with practical, on-the-ground market knowledge. They understand what buyers are actually willing to pay today in their specific local markets, not just historical data or theoretical values.
The Certification Process
Earning C-REPS designation involves several significant steps:
- Specialized Training: Candidates complete comprehensive coursework focused on property pricing methodologies, market analysis, and valuation principles specific to real estate transactions.
- Certification Exams: Professionals must pass rigorous tests demonstrating mastery of pricing concepts and market analysis techniques.
- Performance Requirements: Ongoing performance standards ensure certified agents maintain the highest levels of service and accuracy.
- Membership Maintenance: C-REPS professionals must maintain active membership and participate in continuing education to keep their credentials current.
- Professional Code of Ethics: All C-REPS professionals commit to a strict code of ethics that goes beyond standard licensing requirements.
This multi-layered process means that agents holding C-REPS credentials have invested significant time, effort, and resources into their professional development. It’s not an easy designation to earn or maintain, which is precisely why it carries meaningful weight.
Why Real Estate Agent Credentials Matter
The real estate industry faces a unique credibility challenge. While licensing requirements exist to protect the public, they establish only a minimum baseline. A licensed agent might have been practicing for one month or twenty years. They might specialize in luxury residential properties, commercial real estate, or both. They might work in a highly competitive urban market or a quieter rural area.
Professional credentials like C-REPS bridge this gap by providing a standardized measure of expertise and commitment. When you work with a credentialed professional, you know several things beyond the legal minimum:
- They’ve proven their knowledge: Certification exams aren’t formalities. They’re rigorous assessments that measure actual competency in specialized areas.
- They’ve committed to continuing education: Markets change, technologies evolve, and best practices improve. Certified professionals stay current with ongoing training.
- They’ve accepted accountability: Professional codes of ethics create accountability structures that go beyond what licensing alone provides.
- They’ve invested in their reputation: Professionals who pursue advanced credentials are signaling that their reputation matters to them, which means they have real skin in the game.
For home sellers especially, credentials matter enormously. An inaccurate price listing costs money. Price too high, and your property sits on the market while comparable homes sell. Price too low, and you leave significant equity on the table. Professional pricing expertise can mean tens of thousands of dollars in transaction outcomes.
What Makes C-REPS Different From Average Agents
The real estate market includes professionals across a spectrum of commitment and expertise. C-REPS professionals distinguish themselves in several critical ways:
Professional Certification vs. Licensing Alone
Any agent can be licensed. C-REPS professionals have voluntarily pursued advanced certification, which means they’ve invested additional time, money, and effort beyond minimum legal requirements. This signals genuine professional commitment.
Deep Local Market Knowledge With Systematic Training
Some agents develop strong market knowledge through years of experience. Others rely on technology and data without deep community understanding. C-REPS professionals combine both: systematic, professional training plus practical knowledge of what actually sells in their specific markets today.
Many agents look backward at historical data. C-REPS specialists focus on current market conditions and what contemporary buyers are actually willing to pay in real-world transactions, not theoretical models.
Network and Collaboration
When you hire a single C-REPS professional, you don’t get just one agent. You gain access to an entire network of certified professionals who collaborate and share market intelligence. This network effect amplifies the value you receive.
Accuracy and Rigor
C-REPS professionals apply a rigorous, systematic approach to pricing that combines professional training principles with real-market expertise. This methodology reduces the guesswork and emotion that sometimes cloud pricing decisions.
Professional Commitment
In an industry sometimes characterized by quick-commission seeking and “fly-by-night” operators who disappear after closing, C-REPS professionals signal genuine, long-term commitment to the profession and their clients’ outcomes.
Who Benefits Most From Working With C-REPS Professionals?
Home Sellers
If you’re selling a property, pricing accuracy directly impacts your financial outcome. C-REPS professionals excel at competitive market analysis, helping you understand the exact price point that attracts serious buyers while maximizing your net proceeds. For many sellers, the difference between a C-REPS professional and an average agent translates to thousands of dollars.
Home Buyers
Buyers benefit from C-REPS professionals’ deep understanding of fair market value. They can help you recognize when a property is priced reasonably and when a seller is asking too much. This expertise helps you avoid overpaying and make confident offers that reflect true market conditions.
Homeowners and Investors
Property owners considering refinancing, investment decisions, or estate planning often need professional valuations for their property holdings. C-REPS professionals provide the credentialed expertise needed to support important financial decisions.
Anyone Seeking Professional Guidance
If you’re navigating any significant real estate transaction and want to work with truly credentialed, professional experts rather than average agents, C-REPS professionals represent genuine professional excellence.
How C-REPS Professionals Approach Pricing
The methodology C-REPS professionals use differs fundamentally from simplistic approaches some agents use. Here’s what sets their process apart:
Comparative Market Analysis
C-REPS professionals conduct thorough comparative market analyses (CMAs) that examine recent sales of truly comparable properties, not just any homes in the area. They understand which property characteristics drive value and can adjust for legitimate differences.
Current Market Conditions
Rather than averaging sales over a long historical period, C-REPS professionals focus on current market conditions. In a market shifting from seller’s to buyer’s market, this distinction matters significantly.
Buyer Psychology and Real-World Pricing
C-REPS professionals understand how property characteristics can influence market value, including condition, improvements, location, and house safety considerations. They don’t rely solely on formulas or algorithms; they combine data analysis with practical knowledge of genuine buyer preferences in their market.
Regular Updates and Adjustments
Markets move quickly. C-REPS professionals continuously monitor market conditions and adjust their analyses as new data emerges. A price recommendation from three months ago might not reflect current conditions.
Professional Documentation
Every C-REPS pricing analysis includes detailed documentation of the methodology, comparable properties used, adjustments made, and reasoning. This transparency helps clients understand the basis for recommendations.
The Ethical Standards C-REPS Professionals Maintain
Professional credentials carry responsibilities. C-REPS professionals must adhere to a comprehensive code of ethics that typically includes:
- Honest and Accurate Representations: Providing truthful information about properties and markets, never misleading clients for commission benefit.
- Conflict of Interest Disclosure: Clearly disclosing any situations where interests might conflict.
- Client Confidentiality: Protecting confidential client information and transaction details.
- Fair Dealing: Treating all parties to a transaction fairly and honestly.
- Professional Competence: Only taking on work within their area of expertise and maintaining necessary skills.
- Continuing Education: Staying current with market changes, legal developments, and professional best practices.
These standards create accountability mechanisms beyond what basic licensing provides. Violations can result in losing the credential, which creates meaningful incentive to maintain the highest professional standards.
How to Find and Work With C-REPS Professionals
If you’re ready to work with a C-REPS professional, here’s how to find one:
Search Directories
Start with NABPOP’s official directory of certified C-REPS professionals. This ensures you’re working with someone who has actually earned and maintained the credential.
Verify Credentials
When an agent claims C-REPS certification, verify it directly through NABPOP rather than simply accepting their word. Legitimate professionals expect credential verification.
Ask About Experience
C-REPS certification is relatively specialized. Ask how long the agent has held the credential and how many transactions they’ve completed using C-REPS methodologies.
Review Market Knowledge
During initial consultations, assess their depth of local market knowledge. Do they understand the specific neighborhoods you’re interested in? Can they speak knowledgeably about recent market trends?
Evaluate Communication
Work with professionals who explain their methodology and reasoning clearly. You should understand why they’re recommending specific strategies and pricing points.
Check References
Ask for references from recent clients, particularly those in situations similar to yours. What did previous clients appreciate about working with this professional?
C-REPS Certification in Your Real Estate Transaction
When it’s time to buy or sell a property, you’re making a decision that affects your financial future. Choosing to work with a C-REPS professional is choosing expertise, accountability, and professional excellence.
For sellers, this choice often means the difference between maximizing your proceeds and leaving money on the table. For buyers, it means working with someone who truly understands fair market value and can guide you to wise decisions.
The real estate professionals who pursue C-REPS certification are signaling something important: they take their profession seriously, they’ve invested in expertise beyond minimum requirements, and they’re committed to professional excellence and ethical practice.
In an industry sometimes characterized by varying levels of professionalism, that commitment makes a measurable difference.
Frequently Asked Questions
What is the difference between C-REPS certification and a real estate license?
A real estate license is a legal requirement to practice as an agent or broker. It establishes minimum competency for basic real estate transactions. C-REPS certification is a voluntary professional credential that demonstrates specialized expertise in property pricing and market analysis. Think of licensing as the baseline requirement and C-REPS as evidence of advanced professional development and commitment to excellence.
How long does it take to earn C-REPS certification?
The timeline varies based on individual circumstances, but most professionals can complete the training and certification process within several months. This includes completing specialized coursework, studying for exams, and passing all required tests. The exact timeframe depends on your existing experience and how intensively you pursue the credential.
Is C-REPS certification required to practice real estate?
No. C-REPS certification is completely voluntary. Any licensed real estate agent can practice without it. However, professionals who pursue the certification signal additional expertise and commitment to professional excellence. It’s a differentiator that helps them attract clients seeking specialized knowledge.
How much does C-REPS certification cost?
Costs vary but typically include training course fees, exam fees, and ongoing membership dues. These costs are modest compared to the potential value professionals gain from the credential. If you’re considering working with a C-REPS professional, you can ask them directly about any additional costs their clients might incur for their specialized services.
How often do C-REPS professionals need to renew their certification?
C-REPS professionals must maintain their certification through ongoing membership and continuing education requirements. Most programs require annual renewal along with documented completion of continuing education hours. This ensures certified professionals stay current with market changes and best practices.
Will hiring a C-REPS professional cost me more?
Many C-REPS professionals charge the same commission rates as other agents. The value they provide isn’t in higher costs but in better outcomes. For sellers especially, improved pricing accuracy often means significantly better net proceeds. For buyers, it means better decision-making that prevents overpaying. The investment in professional expertise typically pays for itself many times over.
Can I trust that a C-REPS professional will charge fair prices?
C-REPS professionals commit to ethical standards that specifically address fair dealing and honest representations. Additionally, their credential creates accountability; violations of professional standards can result in losing the certification. This accountability structure creates powerful incentive to maintain highest ethical standards. That said, any professional relationship works best when based on clear communication and mutual understanding of expectations.
Are C-REPS professionals appraisers?
No. C-REPS professionals are real estate agents and brokers, not appraisers. While appraisers provide formal valuations for lending purposes, C-REPS professionals provide expert pricing guidance for actual market transactions. Their focus is understanding what real buyers will actually pay today in your specific market.
How do I verify someone actually has C-REPS certification?
Check directly with NABPOP (National Association of BPO Professionals), the organization that administers the credential. Their website typically includes a directory of certified professionals. Never simply trust an agent’s claim without independent verification.
Should I only work with C-REPS professionals?
C-REPS certification signals professional expertise, but other excellent agents may have different certifications or simply strong experience and reputations. The credential is one valuable indicator of competence. When evaluating any professional, consider their credentials, experience, local market knowledge, references, and communication style as a complete package.