AI Machine Learning Real Estate Valuation: Future Trends
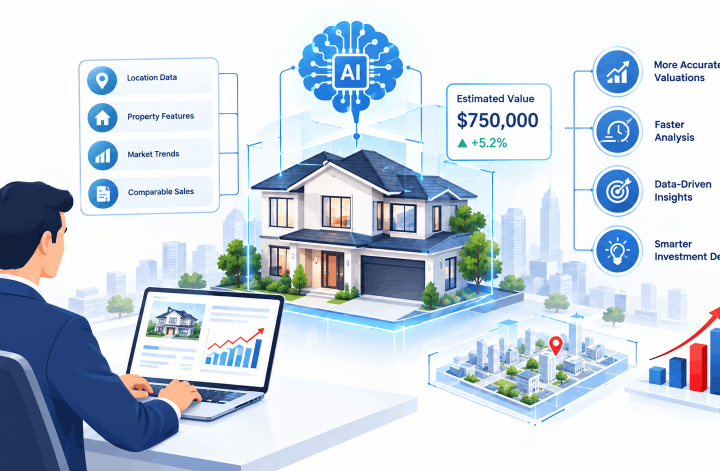
Property valuation has always been part science and part judgment. For decades, that balance rested on comparable sales, appraiser experience, and a feel for the local market. Today, artificial intelligence and machine learning are changing how values are estimated, how quickly they update, and how much data sits behind each number. For homeowners, buyers, and investors, understanding these shifts helps you make better decisions about pricing, financing, and timing.
This guide covers where AI-driven valuation stands, where it is heading, what it still gets wrong, and how to use these tools alongside professional guidance.
How AI Is Changing Real Estate Valuation
Traditional valuation relies on a limited set of recent sales, a visual inspection, and the appraiser’s judgment. AI-based valuation models work differently. They ingest large volumes of data, including past transactions, tax records, listing histories, neighborhood amenities, school boundaries, flood zone maps, and economic indicators, then look for patterns that humans might miss.
The Core Technologies Behind Automated Valuation
Several technologies sit under the umbrella of AI valuation:
- Automated valuation models (AVMs): Statistical and machine learning systems that estimate a property’s value from data without a site visit.
- Gradient boosting and neural networks: Algorithms that learn complex, nonlinear relationships between property features and sale prices.
- Computer vision: Systems that analyze listing photos, satellite imagery, or street-level views to assess condition, curb appeal, and renovation status.
- Natural language processing: Tools that read listing descriptions, inspection reports, and public records to extract details that structured data often misses.
- Time-series forecasting: Models that project how values may move based on interest rates, employment trends, and inventory levels.
Each of these tools adds a different kind of signal. The strongest systems combine several of them.
Why Speed and Scale Matter
One practical advantage of machine learning is frequency. A traditional appraisal is a snapshot taken at one moment. An AI model can update estimates weekly or even daily as new sales and listings enter the market. For a seller deciding when to list, or an investor tracking a portfolio, that refresh rate is valuable.
Where AI Valuation Is Heading
The next several years will likely bring changes in five areas.
1. Hybrid Human and Machine Valuation
The most credible future is not one where algorithms replace professionals. It is one where models do the heavy lifting on data and experts interpret the results. An agent or appraiser can review an automated estimate, flag what the model cannot see (a recent kitchen remodel, a drainage problem, a noisy highway that changed the block), and adjust accordingly.
2. Better Handling of Unique Properties
Early AVMs performed well on standard homes in dense markets with many sales. They struggled with unusual properties, rural land, historic homes, and neighborhoods with few transactions. Newer approaches, including models that borrow strength from similar areas and incorporate more detailed property attributes, are narrowing that gap. Even so, a one-of-a-kind property will usually need human review.
3. Explainable Valuation
Regulators, lenders, and consumers increasingly want to know why a model produced a given number. Explainability tools now show which factors pushed an estimate up or down, such as square footage, recent comparable sales, or proximity to transit. Expect this transparency to become a standard expectation rather than an optional feature.
4. Real-Time Market Signals
Valuation tools are beginning to incorporate faster inputs: mortgage rate changes, days on market, price reductions, and local inventory shifts. This means estimates may move more responsively to conditions, which is useful for sellers pricing in a shifting market but also means a figure from last month may already be outdated.
5. Tighter Data Quality Standards
Machine learning is only as good as its inputs. Incomplete public records, inconsistent property data, and errors in square footage or bedroom counts can all skew results. The industry is moving toward cleaner data pipelines and better verification, which should improve accuracy over time.
What AI Valuation Still Gets Wrong
Understanding limitations is just as important as understanding strengths.
- Condition is hard to see in data. A home with original 1980s wiring and a home with a new roof may look identical in a database.
- Local nuance can be missed. A street that flooded last spring, a planned highway expansion, or a well-regarded school that changed boundaries may not appear in the training data.
- Thin markets produce wide ranges. When few homes sell in an area, models have less to learn from and estimates can swing significantly.
- Bias can creep in. If historical data reflects past discrimination or uneven investment, models can reproduce those patterns unless developers actively test and correct for them.
- Recent changes lag. Renovations, additions, and improvements are often not recorded promptly, so the model may not know about them.
For these reasons, an automated estimate is best treated as a starting point, not a final answer.
Traditional Appraisal vs. AI Valuation vs. Certified Agent Pricing
Each approach serves a different purpose. The table below compares them in general terms.
| Factor | Traditional Appraisal | AI Valuation Model | Certified Agent Pricing (C-REPS) |
| Primary input | Site visit, comparable sales, appraiser judgment | Large datasets, property records, market patterns | Local market activity, buyer behavior, property condition |
| Speed | Days to weeks | Seconds to minutes | Typically days, with ongoing market monitoring |
| Strength | Formal documentation, lender-recognized | Scale, frequency, consistency | Real-market knowledge and negotiation insight |
| Weakness | Can be slow and costly | Struggles with condition and unusual properties | Depends on the individual’s training and ethics |
| Best use | Mortgage and legal requirements | Quick estimates and monitoring | Setting a list price or evaluating an offer |
Note that an appraisal is generally required for mortgage lending, while an agent’s pricing opinion is a marketing and negotiation tool. Each serves a different purpose.
What This Means for Home Sellers
If you are preparing to sell, you will likely encounter several automated estimates before you list. These numbers often appear on property websites and can influence expectations, sometimes significantly.
Here is a practical approach:
- Check several estimates. Different models use different data, so their results may vary.
- Ask why the numbers differ. Recent renovations, lot size, and condition can explain gaps.
- Get a professional opinion. A certified agent can evaluate what buyers in your specific neighborhood are actually willing to pay today.
- Document improvements. Keep receipts and permits for upgrades. Records help both human and automated valuations reflect your home accurately.
- Price for the market, not the algorithm. An estimate is informative, but the sale price is set by what buyers will pay.
Sellers who overprice based on an inflated online estimate often sit on the market longer, which can ultimately lower the final sale price.
What This Means for Home Buyers
Buyers benefit from AI tools when they use them for research. Automated estimates can help you screen listings quickly and spot neighborhoods where prices may be out of line with recent trends.
Keep these points in mind:
- An estimate is not an offer. Use it to frame your research, not to set your maximum bid.
- Lenders typically require a formal appraisal. If the appraisal comes in below the contract price, you may need to renegotiate or cover the gap.
- Ask your agent for a comparative market analysis based on recent local sales and active listings.
- Pay attention to what an estimate cannot see: condition, layout, neighborhood changes, and future development plans.
Practical Examples
Example 1: The renovated bungalow. A homeowner updated the kitchen and bathrooms but did not report the work. The automated estimate used the original floor plan and older condition data, producing a figure well below the home’s market potential. A certified agent reviewed the renovation details, compared recent sales of similarly updated homes, and recommended a list price that reflected the improvements.
Example 2: The buyer’s surprise. A buyer saw a strong online estimate for a townhouse and offered near that number. The lender’s appraisal came in lower because two comparable sales in the complex were much less recent and had been priced differently. The buyer, with agent guidance, negotiated a revised price instead of waiving the appraisal contingency.
Example 3: The rural property. An owner with five acres and a detached workshop received an automated estimate that ignored the acreage and outbuilding. The agent gathered sales of comparable rural properties and adjusted the valuation to account for land and improvements.
Actionable Tips for Getting the Most Accurate Value
- Keep a home improvement log with dates, costs, and contractor details.
- Gather documentation such as permits, warranties, and inspection reports.
- Note recent changes to the neighborhood, like new construction, transit access, or zoning updates.
- Compare at least three sources before drawing conclusions.
- Talk to a local professional who can interpret data in context.
Frequently Asked Questions
How accurate are AI home valuations?
Accuracy varies widely by location, property type, and data quality. Models tend to perform best in active markets with many recent sales and standard homes. Unusual properties and thin markets usually produce wider margins of error, so treat any automated figure as an estimate.
Can AI replace appraisers and real estate agents?
Not in the near term. AI handles data processing well but cannot inspect a property, understand local context in full detail, or negotiate. The most effective approach combines automated tools with trained professionals who can verify and interpret results.
Why do different websites show different home values?
Each platform uses its own data sources, algorithms, and update schedules. Some include off-market data or different property attributes. Differences are normal, and comparing them can reveal useful information about the home.
Will AI valuation make home prices more transparent?
It can improve transparency by making estimates more accessible and explainable. However, transparency depends on data quality and how openly platforms share their methods. Consumers should still verify important numbers with recent local sales.
Are online home estimates reliable enough to set a listing price?
They can inform a pricing discussion but should not be the sole basis for a list price. A comparative market analysis from a certified professional, based on recent local sales and current buyer demand, is more reliable for setting a competitive price.
How often should I check my home’s estimated value?
If you are planning to sell in the next year, checking quarterly can help you track trends. For long-term owners, an annual review is usually enough. Major market shifts or renovations are good reasons to check sooner.
What data should I provide to improve an automated estimate?
Share accurate square footage, a list of recent upgrades with dates, and any known condition issues. Many platforms allow owners to correct property details. More accurate inputs generally lead to more accurate outputs.
Do certified agents use AI tools too?
Many do. Certified professionals often use automated estimates as one input among several. Their added value lies in local market knowledge, property walkthroughs, and the judgment needed to adjust for factors data cannot capture.
Property Tax Assessment Appeal: How Valuation Evidence Can Lower Your Bill
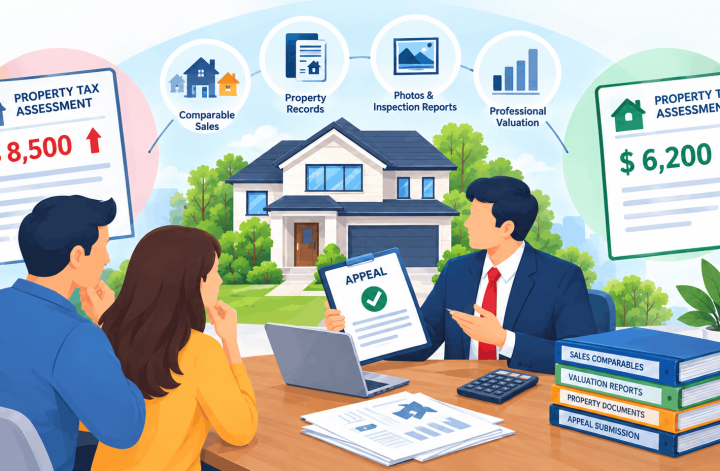
Most homeowners receive a property tax assessment notice once a year and glance at the number without thinking much about it. Yet that figure drives a significant share of the annual housing bill, and it often differs from what the home would realistically sell for. When the assessed value is too high, the owner pays more tax than the law requires, sometimes for years. The good news is that every jurisdiction that levies a property tax provides some process for challenging an assessment, and a well-supported appeal can produce a meaningful reduction.
This guide explains how property tax assessment appeals work, what makes valuation evidence persuasive, how to build a case step by step, and how to present it at a hearing. It also covers the common mistakes that cause appeals to fail and the situations where professional help is worth the cost.
What a Property Tax Assessment Appeal Is
A property tax assessment appeal is a formal request asking a local assessor, review board, or tax tribunal to correct the assessed value placed on a property. The assessment is the value the government uses to calculate tax, usually multiplied by a tax rate or millage rate. Because the tax rate is set separately, a lower assessment reduces the bill directly.
Appeals are based on the idea that assessments should reflect market value as of a specific date, which is often January 1 or another date set by the jurisdiction. Assessors use mass appraisal methods that estimate values for thousands of properties at once. These methods are efficient, but they can miss details that matter for an individual home, such as a failing foundation, an outdated kitchen, a location next to a busy road, or a sale that occurred at a price well below the assessed figure. An appeal gives the owner an opportunity to present those details and the evidence supporting them.
Assessed Value Versus Market Value
Understanding the difference between assessed value and market value is the foundation of any appeal. Market value is the price a willing buyer would pay a willing seller in an open market, with reasonable knowledge of the property and neither party under undue pressure. Assessed value is the figure the assessor assigns for tax purposes. In many places, assessed value is a fixed percentage of market value, and some states use the phrase “taxable value” or “equalized value” instead.
The gap between the two is where most appeals begin. If an assessor values a home at $420,000 but comparable homes on the same street have recently sold for $360,000, the owner has a reasonable basis to question the figure. Assessors are not required to be perfect, but they are expected to be reasonably accurate, and the owner’s job is to show where the assessment departs from the evidence.
Common Grounds for an Appeal
Successful appeals usually rest on one or more recognized grounds. Knowing which ones apply to your property helps you focus the evidence.
The first ground is overvaluation, meaning the assessed value exceeds market value. This is the most common argument, and it is typically supported by recent comparable sales, an independent appraisal, or a market analysis.
The second is factual error. Assessors sometimes record the wrong square footage, count a bedroom that does not exist, list a finished basement that is actually unfinished, or assign a property to the wrong lot. Errors like these can be corrected quickly if documented.
The third is unequal treatment, sometimes called non-uniformity. This argument shows that similar properties in the same area are assessed at a lower ratio of value than yours. Even if your assessment is close to market value, you may be paying a disproportionate share if neighbors are assessed much lower relative to what they would sell for.
The fourth is condition or external factors. Damage from fire or flood, deferred maintenance, functional obsolescence, or negative influences such as a nearby landfill can justify a lower value. These arguments require careful documentation, often including photographs, repair estimates, and inspection reports.
Know Your Deadlines Before You Begin
Appeal deadlines are strict, and missing one usually means waiting another full year. The window often opens when the assessment notice is mailed and closes within a short period, sometimes as little as 30 days, though some jurisdictions allow 45 to 60 days or more. Some states also set separate deadlines for informal review, formal appeal to a local board, and further appeal to a state tribunal or court.
Read your notice carefully. It should state the assessed value, the date, the procedure for appealing, and the deadline. If you cannot find this information, contact the assessor’s office directly and ask for written confirmation of the deadline and the required forms. Mark the date on your calendar as soon as you receive the notice, and aim to file several days early in case of mailing or submission problems.
The Evidence That Makes an Appeal Persuasive
Assessment boards decide appeals based on evidence, not on how strongly an owner feels that the number is too high. The most persuasive evidence is specific, recent, and comparable to the subject property.
Comparable sales are the strongest type of evidence in most cases. Look for three to five recent sales of similar homes within the same neighborhood or a close area. Similar means comparable in size, age, style, condition, lot size, and location. Sales should ideally have occurred within the period the assessor used for valuation, and they should be arm’s-length transactions, meaning sales between unrelated parties without unusual financing or forced circumstances. Foreclosures, estate sales, and transfers between family members may be excluded or adjusted, so note any unusual features when you present them.
An independent appraisal can carry considerable weight, especially when prepared by a licensed or certified appraiser who follows recognized professional standards. A written report should describe the property, the valuation date, the methods used, the comparable sales, the adjustments made for differences, and the final opinion of value. Appraisals cost money, but they can be worth it when the potential tax savings are substantial or when the assessor has relied on a flawed analysis.
A market analysis from a qualified real estate professional offers another useful perspective. A comparative market analysis or broker price opinion reflects recent sales, active listings, and local demand. Boards may give it less weight than a formal appraisal, depending on local practice, but it can still help you understand the market and frame your argument. Certified pricing professionals, such as those trained through the National Association of BPO Professionals (NABPOP) certification program, can provide a disciplined, market-based analysis grounded in local knowledge. It is important to be clear that these professionals are real estate agents and brokers rather than appraisers. Their analysis is most useful as supporting evidence or as a guide to the market, and some boards will accept it while others will require a licensed appraiser’s report.
Photographs, inspection reports, repair invoices, and documentation of errors in the assessor’s property record also strengthen your case. Date-stamped photos showing damage or deterioration are especially helpful when condition is part of the argument.
A Step-by-Step Approach to Building Your Case
Start by reviewing your assessment record. Most assessors make property records available online or by request. Check the square footage, lot size, number of rooms, bathrooms, year built, basement and garage details, and any listed improvements. Correct factual errors first, because they are often the easiest to fix and can reduce the value without a lengthy argument.
Next, research comparable sales. Use public records, multiple listing service data through a licensed professional, or the county recorder’s sales database. Build a simple spreadsheet listing each comparable sale, its date, sale price, size, age, condition, lot size, and any relevant differences. Be honest about differences that favor the assessor, because an evidence package that ignores them will lose credibility.
Then decide what your evidence shows. If comparable sales support a value well below your assessment, you have a strong case. If the evidence is mixed, consider whether a formal appraisal would clarify the picture. If your assessment is close to market value but neighbors are assessed much lower, focus on the equity argument.
Prepare a concise written statement that explains your position in plain language. State the assessed value, the value you believe is correct, the evidence supporting it, and the specific reasons the assessment is inaccurate. Organize exhibits in a logical order and label them so the board can follow your argument.
Finally, file the appeal on time and keep copies of every document. Many jurisdictions require the appeal form to be signed and submitted in a particular way, and some require a filing fee. Confirm the submission method and retain proof of filing.
Presenting Your Case at a Hearing
Many appeals are resolved through paperwork alone, but some move to a hearing. Preparation makes a significant difference.
Keep your presentation short and factual. Boards hear many appeals in a single session and value clarity. Begin with the assessed value you are challenging, the value you are requesting, and the main reason. Then walk through your strongest evidence, starting with the comparable sales or appraisal.
Expect questions and prepare answers. Board members may ask why a particular comparable is similar, why you chose a specific date, or how you adjusted for differences in size or condition. Answer directly. If you do not know something, say so and offer to provide the information in writing.
Be respectful even if you disagree with the assessor. Many assessors are experienced professionals working within constraints, and a cooperative tone often leads to a more productive discussion. If the assessor offers a reasonable adjustment during an informal review, consider accepting it when it is supported by the evidence.
Comparing Your Appeal Options
Owners typically choose among several paths. An informal review with the assessor’s office is the simplest and least expensive. Many errors and some valuation disputes can be resolved through a conversation and a few documents. This approach works best when the problem is a factual error or when the assessment is clearly inconsistent with recent sales.
A formal appeal to a local board of review or equalization is the next step. It requires a written filing and usually a hearing. This option suits cases where informal review fails and the evidence is strong enough to justify a formal presentation.
A further appeal to a state tax tribunal, administrative court, or circuit court is available in many places when the board’s decision is unsatisfactory. These proceedings are more complex, often require legal representation, and carry higher costs, but they can be appropriate for high-value properties or significant legal questions.
Most owners should start with the least formal option that can reasonably achieve their goal and escalate only if needed.
Common Mistakes That Undermine Appeals
Several errors appear repeatedly in unsuccessful appeals. The most common is relying on general statements, such as “my house is worth less than this” or “the market has dropped,” without specific evidence. Boards need concrete data.
Another frequent mistake is choosing comparables that are not truly similar. A home with four bedrooms and an updated kitchen is not a good comparison for a three-bedroom home with an original kitchen, unless adjustments are clearly explained and justified.
Some owners also miss the valuation date. Evidence from years ago or from after the assessment date may not be relevant unless it shows a trend that affects the valuation as of the correct date.
Finally, many appeals fail because the deadline is missed. Owners who wait for a convenient moment often discover that the window has closed. Early preparation is one of the most effective strategies available.
Practical Examples
Consider a homeowner whose assessment rose sharply during a period of rapid local price growth. The assessor valued the home at $380,000. The owner gathered sales records for four nearby homes that sold between $330,000 and $355,000 over the prior six months. Two of the comparables were similar in size and condition, and the others required modest adjustments for garage size. The owner filed a formal appeal with a comparable sales analysis and photographs of an outdated roof. The board reduced the assessment to $352,000, lowering the annual tax by a meaningful amount.
In a second example, a property owner discovered that the assessor’s record listed a finished basement that had never been completed. The basement was unfinished storage space with no heat and no bathroom. The owner provided the original plans, a current photograph, and a letter from a contractor confirming the condition. The assessor corrected the record during informal review, and the assessment dropped substantially without a formal hearing.
A third example involves an investor with several rental properties. Two properties in the same subdivision were assessed at a much higher ratio of market value than the investor’s other holdings. The investor documented the assessment ratios for comparable properties in the area and filed a non-uniformity appeal. The board adjusted the assessments to bring them closer to the common ratio, reducing the tax burden across the portfolio.
Actionable Advice for Homeowners
Check your assessment notice as soon as it arrives and note the appeal deadline immediately. Do not assume the assessor will correct an error on their own.
Review your property record for factual accuracy. Correcting errors is often the quickest path to a lower assessment.
Gather at least three recent comparable sales and compare them carefully to your home. Be honest about differences, and explain any adjustments you make.
Consider a formal appraisal if the potential tax savings are significant or if the evidence is contested. Choose a licensed or certified appraiser with experience in property tax work.
If you want a market-based perspective on your home’s value, a certified pricing professional can prepare a comparative analysis. Ask whether the local board accepts this type of evidence before you rely on it.
Keep every document, note the names of people you speak with, and record the dates of all communications. Good records make the process smoother if the case moves forward.
When to Consider Professional Help
Many homeowners handle informal reviews and simple appeals on their own. Professional help becomes more valuable when the property is high-value or unusual, when the assessment difference is large, when the local process is complex, or when a further appeal to a tribunal or court is likely.
A property tax attorney or consultant can review the assessment, identify legal arguments, and represent you at hearings. Some consultants work on contingency, taking a percentage of the tax savings. Read any fee agreement carefully and understand what is included.
An independent appraiser can provide a report that the board will recognize as authoritative. For many contested cases, this is the single most useful investment.
Frequently Asked Questions
Can I appeal my property tax assessment if I do not think it is wrong?
Yes, but you should have evidence before filing. Boards expect appeals to be supported by specific data showing that the assessment exceeds market value, contains errors, or is inconsistent with similar properties. Without evidence, an appeal is unlikely to succeed and may cost time and fees. Reviewing comparable sales is a good first step to decide whether an appeal is justified.
How long does a property tax appeal take?
The timeline varies by jurisdiction. An informal review may be resolved in a few weeks, while a formal board hearing can take several months from filing to decision. Further appeals to a tribunal or court may take considerably longer. Ask the assessor’s office for the typical schedule in your area.
Do I need a lawyer to appeal my property taxes?
Most homeowners can file an appeal and present their case without a lawyer, especially for residential properties and straightforward issues. Legal help becomes more valuable for complex cases, high-value properties, or appeals beyond the local board. Some jurisdictions also have free or low-cost assistance programs for homeowners.
Will a lower assessment always mean a lower tax bill?
A lower assessment usually reduces the tax bill, but the effect depends on the tax rate, any exemptions or caps, and how the jurisdiction calculates tax. In some places, a reduction in assessed value may be offset by a change in the tax rate, so it is worth asking how the appeal will affect your actual bill.
Can my assessment go up if I file an appeal?
In some jurisdictions, the board has authority to review the property as a whole and could increase the assessment if it finds the original value was too low. This is uncommon but possible. Ask the assessor’s office whether this risk exists in your area before filing.
What evidence carries the most weight with an assessment board?
Recent, arm’s-length comparable sales that closely match the subject property usually carry the most weight. A licensed or certified appraisal prepared under recognized standards is also highly persuasive. Documented factual errors and clear evidence of condition problems can be decisive when they are supported by photographs and third-party records.
Can I appeal every year?
Most jurisdictions allow annual appeals, but the rules vary. Some limit appeals to specific periods, such as reassessment years, while others allow appeals whenever the assessment is significantly inaccurate. Check your local rules before assuming you can file in a given year.
Is a real estate agent’s price opinion accepted in an appeal?
It depends on the jurisdiction and the board. Some boards accept market analyses as supporting evidence, while others require a formal appraisal from a licensed or certified appraiser. A certified pricing professional’s analysis can still be valuable for understanding the market and for building the factual basis of your case, even when it is not the primary evidence.
What happens if I win my appeal?
If the board reduces your assessment, the change is usually applied to the current tax year and may affect future years until the next reassessment. You may receive a revised tax bill or a credit for taxes already paid. Confirm the outcome in writing and keep a copy of the decision for your records.
Estate Settlement Property Valuation: Legal Requirements and Best Practices
When someone dies and leaves real estate behind, the property has to be valued before the estate can be settled. That single number affects how much tax may be owed, how assets are divided among heirs, how the stepped-up basis is calculated for future sales, and whether the family can defend its decisions if a court or taxing authority asks questions later. A rough guess from a neighbor or an online estimate will not hold up under scrutiny, and an error in valuation can cost an estate thousands of dollars or create disputes that drag on for years.
This guide explains what estate settlement property valuation means, which legal rules usually apply, what the executor or administrator must document, and how to work with the right professionals. It also clarifies the difference between a formal legal appraisal and a market-based pricing analysis, because families often confuse the two.
What Is Estate Settlement Property Valuation?
Estate settlement property valuation is the process of determining the fair market value of real estate owned by a person at the time of death. Fair market value is generally defined as the price a willing buyer would pay a willing seller, with neither under pressure to act and both having reasonable knowledge of the relevant facts. That definition appears in federal tax regulations and is echoed in many state probate codes, although the details vary.
The valuation date matters. In most cases, the property is valued as of the date of death. An executor may elect an alternate valuation date six months after death under Internal Revenue Code Section 2032, but only if doing so reduces both the gross estate and the estate tax owed. Choosing the wrong date, or failing to document the one selected, can create problems that are difficult to fix later.
Valuation serves several purposes at once. It establishes the gross estate for federal estate tax purposes when the estate is large enough to require a filing. It sets the cost basis for heirs under the stepped-up basis rule in Section 1014, which can significantly reduce capital gains tax if the property is sold. It also informs the probate inventory, the division of assets among beneficiaries, and any equalization needed when one heir takes the house and others receive other assets.
The Legal Framework Behind Estate Valuation
Federal Estate Tax Rules
For 2026, the federal estate tax exemption is $15 million per person, and it was made permanent by the One Big Beautiful Bill Act signed in July 2025. Estates below that threshold generally do not owe federal estate tax, and many estates will never file a federal estate tax return. However, a return may still be required in certain situations, and the valuation records are important for other reasons, including the basis calculation.
When a federal estate tax return is required, the IRS uses Form 706. Real estate must be reported at fair market value, and the instructions call for supporting documentation, typically a qualified appraisal prepared by a qualified appraiser. The return is generally due nine months after the date of death, with an automatic six-month extension available for filing, though any tax owed must still be paid by the original due date to avoid penalties and interest.
Stepped-Up Basis and Heir Reporting
Under Section 1014, property inherited from a decedent generally receives a new cost basis equal to its fair market value on the date of death. If an heir sells the property shortly afterward for close to that value, little or no capital gain may result. This makes the date-of-death valuation one of the most financially important numbers in the entire estate.
Estates that must file Form 706 are also subject to basis consistency rules. Heirs are generally required to report the basis of inherited property consistently with the value reported on the estate tax return, and in certain cases the executor must file Form 8971 with the IRS and provide basis information to beneficiaries. Even estates that do not file a federal estate tax return should keep a clear record of the valuation, because heirs will need it years later.
State Probate and Court Requirements
Probate rules are set at the state level, and they vary considerably. Many states require the personal representative to prepare an inventory of estate assets within a set period after appointment, listing each asset with its value. Some courts require that real estate be appraised by a court-appointed or licensed appraiser, while others accept a valuation from a qualified professional selected by the executor. In certain jurisdictions, interested parties can object to the inventory values, which can lead to hearings and additional evidence.
Some states also impose their own estate or inheritance taxes, and the exemption thresholds can be far lower than the federal level. Massachusetts, for example, has a state estate tax exemption of about $2 million that is not indexed for inflation. Estates in these states may need valuations that satisfy both federal and state requirements, and the standards are not always identical.
Who Is Responsible for the Valuation?
The personal representative, meaning the executor named in the will or the administrator appointed by the court, is generally responsible for ensuring that property is valued correctly and documented properly. This duty includes selecting qualified professionals, keeping records, and making reasonable efforts to resolve disagreements among heirs. A personal representative who ignores the valuation or relies on informal estimates may face personal liability if the numbers prove inaccurate and harm beneficiaries or creditors.
Appraisal Versus Market Pricing: Understanding the Difference
Many families are unsure whether they need a formal appraisal or whether a real estate agent’s pricing analysis will do. The answer depends on the purpose.
A licensed or certified appraiser produces a written report that follows recognized professional standards, typically the Uniform Standards of Professional Appraisal Practice, and includes the methods, comparable sales, adjustments, and reasoning behind the final opinion. The appraiser must be independent of the parties and must meet education and experience requirements set by state licensing boards. For estate tax returns, court inventories, and most probate proceedings, this type of report is the standard that the IRS and courts expect.
A broker price opinion or a comparative market analysis prepared by a real estate agent serves a different purpose. It reflects what buyers are currently willing to pay in a particular neighborhood, based on recent sales, active listings, and local market conditions. This kind of analysis is valuable for planning a sale, setting a realistic list price, and understanding how the property might perform on the open market. It is generally not a substitute for a formal appraisal when a tax return or court filing requires one.
Certified pricing professionals, including those trained through the National Association of BPO Professionals (NABPOP) certification program, can offer a disciplined, market-based pricing perspective. A C-REPS professional, for example, is an active real estate agent or broker who has completed specialized training, passed certification exams, and agreed to a professional code of ethics. Their work is especially useful when an estate needs to decide whether to sell, how to price the property for a competitive sale, or whether an offer is reasonable. Because they are not appraisers, families should still obtain a formal appraisal when the law requires one, and they can use a pricing analysis alongside it to understand the market.
Step-by-Step: How to Value an Inherited Property
The process works best when it follows a clear sequence. Executors who take these steps early avoid most of the common problems.
First, identify the property and gather basic records. This includes the deed, the property tax assessment, any recent surveys, the mortgage balance, and records of improvements such as a new roof, a renovated kitchen, or an added bedroom. Accurate descriptions help the appraiser and reduce the chance of errors.
Second, determine the valuation date. For most estates, this is the date of death. Consider whether an alternate valuation date might lower the estate tax, but only after confirming that the choice will reduce both the gross estate and the tax owed.
Third, order a formal appraisal from a qualified appraiser. Ask about licensing, experience with estate work, and familiarity with the local probate court. Request that the report be addressed to the estate or the personal representative and that it state the valuation date clearly. Confirm whether the court or the IRS has specific format requirements.
Fourth, obtain a market analysis if the property will be sold. A pricing professional can help set a list price that reflects current buyer demand, which may differ from the appraised value. Keep these two documents separate in the estate file so that each serves its intended purpose.
Fifth, document the decision. Store the appraisal, the market analysis, the correspondence with professionals, and any notes explaining why a particular value was reported. If an heir later questions the figure, these records will be the estate’s best defense.
Sixth, provide heirs with the valuation information they need. Beneficiaries who sell the property later will need the date-of-death value to calculate their basis, so give them a copy of the appraisal and explain its significance.
Common Mistakes That Cause Valuation Problems
Several mistakes appear repeatedly in estate administration. The most costly is relying on the property tax assessment as the fair market value. Assessments are created for taxation purposes, often use mass appraisal methods, and may not reflect the condition of the home or the current market. They can be a useful reference point, but they should not be treated as a legal valuation.
Another frequent error is using an online estimate or a valuation from a casual conversation with an agent who has no written methodology. These figures may look precise, but they rarely include the adjustments and documentation needed to withstand review.
Executors also sometimes wait too long to order an appraisal. Markets change, and an appraisal done years after the date of death may be difficult to reconcile with the valuation date. Acting promptly keeps the evidence fresh and the process orderly.
Finally, families sometimes disagree about the value and let the dispute fester. When heirs have different views, a neutral professional report is often the most efficient way to resolve the question. Some estates also use a second appraisal or a mediator when the difference is significant.
Practical Examples
Consider a family home in a state with no estate tax that is worth about $600,000 at the date of death. The estate is well below the federal exemption, so no federal estate tax return is needed. However, the executor still orders a formal appraisal to support the probate inventory and to establish the stepped-up basis. When two siblings later sell the house for $640,000, their taxable gain is limited to the $40,000 increase above the date-of-death value, rather than the gain measured from the original purchase price decades earlier.
Now consider a second estate in a state with a lower estate tax threshold. The decedent owned a house, a vacation property, and a small business, and the combined estate exceeds the state exemption. The executor needs appraisals of each property that meet both state filing requirements and federal reporting standards. A market analysis of the vacation property helps the family decide whether to sell it quickly or keep it as a rental, while the formal appraisals provide the documentation required by the tax authorities.
In a third scenario, one heir wants to keep the family home and the others want their share in cash. A formal appraisal sets the value used to calculate each beneficiary’s share. The heir who keeps the house may need to arrange financing or use other assets to equalize the division, and a clear valuation makes that negotiation far more transparent.
Actionable Advice for Executors and Heirs
Start by confirming the valuation requirements in your state and whether a federal estate tax return is needed. An estate attorney or certified public accountant can answer these questions quickly and prevent expensive mistakes.
Choose appraisers and pricing professionals with clear credentials, relevant experience, and no conflict of interest. Ask for a fee structure in writing. Avoid arrangements where the professional’s payment depends on the value reported, because that creates an obvious incentive problem.
Keep the appraisal report and the supporting documents organized. Scan them, store copies with the estate attorney, and give beneficiaries access. Good records save time when the estate closes and when heirs eventually sell.
If you are an heir rather than the executor, ask for a copy of the valuation and the date it was determined. Request a written explanation of how the basis will be calculated. If you plan to sell, speak with a tax professional before listing the property.
Comparing Your Options for Valuation Support
Families generally have three paths. A formal appraisal is the most rigorous choice and usually the required one for tax returns and court inventories. It is the best option when the estate must document value for legal purposes, when heirs disagree, or when the property has unusual features that require careful analysis.
A market analysis from a trained agent is the best choice for planning a sale. It answers the question of what the property will likely sell for today, which is different from the question of what it was worth on the date of death. Many estates use both: an appraisal for the legal record and a market analysis for pricing decisions.
An online estimate or property tax assessment can serve as a rough starting point for discussion, but it should not be the final word on value. Treat these figures as preliminary information rather than evidence.
Frequently Asked Questions
Do all estates need a formal property appraisal?
Not every estate needs one by law, but most estates benefit from a formal appraisal. Courts often require an inventory of assets with values, and a federal estate tax return requires supporting documentation for real estate. Even when no filing is mandatory, a professional appraisal establishes the basis heirs will use later, which can prevent disputes and tax surprises.
What is the difference between an appraisal and a comparative market analysis?
An appraisal is a formal opinion of value prepared by a licensed or certified appraiser under recognized professional standards, and it is usually required for legal and tax purposes. A comparative market analysis is a pricing study prepared by a real estate agent that reflects current buyer demand and is most useful for setting a sale price. The two can produce different numbers because they answer different questions.
Can I use the property tax assessment as the value for the estate?
Generally, no. Property tax assessments are designed for taxation and often use mass appraisal methods that may not reflect the home’s condition or current market conditions. Courts and tax authorities usually expect a valuation based on fair market value, supported by a professional report.
What valuation date should an executor use?
For most estates, the date of death is the correct valuation date. An executor may elect an alternate valuation date six months after death under federal law, but only if it reduces both the gross estate and the estate tax. Consult an estate attorney or tax professional before making this election.
How long do I have to file a federal estate tax return?
Form 706 is generally due nine months after the date of death. An automatic six-month extension is available for filing the return, but any estate tax owed is generally still due at the nine-month mark to avoid interest and penalties.
Who pays for the appraisal?
The estate typically pays the cost of the appraisal as an administration expense. The personal representative should keep records of the fee and confirm that the amount is reasonable for the work performed. Some estates pay for multiple valuations, such as one for probate and one for a sale, so it helps to plan the budget early.
What happens if heirs disagree with the appraised value?
Heirs who disagree can raise their concerns with the personal representative and, in many jurisdictions, with the probate court. The estate may obtain a second appraisal, request a review of the original report, or use mediation to reach agreement. Clear documentation and a neutral professional process usually resolve these disputes faster than litigation.
Divorce Property Valuation: How Accurate Values Support a Fair Settlement
Few financial decisions carry more emotional weight than dividing a home during divorce. For many couples, the house is the largest asset they own, and its value shapes everything that follows: who keeps the home, how much cash changes hands, whether one spouse can qualify for a new mortgage, and how the remaining assets are balanced. An inaccurate valuation can quietly tilt a settlement in one direction for years, while a well-documented valuation gives both spouses a shared starting point and reduces the chance of costly disputes.
This guide explains how divorce property valuation works, why the valuation date and property classification matter, which valuation methods are appropriate for different purposes, and how to build a settlement that both parties can accept. It also explains the tax considerations that often go overlooked and the practical steps that help couples reach a fair division.
What Divorce Property Valuation Means
Divorce property valuation is the process of determining the current fair market value of real estate and other property that may be divided in a divorce. Fair market value is generally understood as the price a willing buyer would pay a willing seller, with neither under pressure to act and both reasonably informed about the property. The concept is familiar from estate and tax matters, but divorce adds its own rules about timing, classification, and what counts as a shared asset.
A valuation in divorce does more than produce a number for the home. It establishes the equity available to divide, which is the market value minus the outstanding mortgage and other liens. It supports decisions about whether one spouse should buy out the other, whether the home should be sold, and how the transaction will be reflected in the final decree. Courts and attorneys rely on these numbers, and so do the financial advisors, mediators, and lenders who help couples move forward.
Marital Property and Separate Property
Before a home can be valued for division, the court or the parties must determine whether it is marital property, separate property, or a mix of both. The rules depend on where the couple lives.
Roughly nine states follow community property principles, where most property acquired during the marriage is presumed to belong equally to both spouses. Most other states follow equitable distribution, where the court divides marital property fairly, which does not always mean equally. Each system treats separate property differently, but most agree that property owned before the marriage, received as a gift or inheritance, or excluded by agreement generally remains separate.
A home can be mixed. Suppose one spouse owned a house before marriage, and both spouses later paid the mortgage from a joint account. The portion of the home attributable to the premarital equity may be separate, while the appreciation or principal paid during the marriage may be marital, depending on state law and the facts. Tracing these contributions can require detailed records of mortgage payments, improvements, and the source of funds used, and it is one of the areas where valuation evidence matters most.
Choosing the Right Valuation Date
The valuation date can change the outcome significantly, especially in a rising or falling market. States use different dates, and some courts have discretion to choose the date that produces a fair result. Common options include the date the divorce petition was filed, the date of separation, the date of the final hearing, and the date the decree is entered.
Many states value marital property as of the date of separation or the date of filing, because those points mark when the marital partnership effectively ended. Other states use the date of trial or the date of the decree. The distinction matters because appreciation or depreciation after separation may belong to one spouse or be shared, depending on the rules.
Couples should ask their attorney which date applies in their state and whether any exceptions could change it. Once the date is set, the valuation should be prepared as of that date, even if the home is sold later at a different price. A valuation performed months after the relevant date may need to be adjusted or explained, so timing the appraisal correctly saves time and expense.
Valuation Methods and When Each Makes Sense
Couples often encounter several valuation tools during divorce. Each has a role, but they are not interchangeable.
A certified or licensed appraisal is a formal written opinion of value prepared by a credentialed professional who follows recognized standards, usually the Uniform Standards of Professional Appraisal Practice. The report includes the property description, comparable sales, adjustments, and the reasoning behind the final value. Courts commonly expect this type of report when the parties cannot agree on value or when a buyout depends on the number. Appraisers are generally independent, and their fees are typically shared or allocated by the court.
A comparative market analysis or broker price opinion is prepared by a real estate agent. It reflects recent sales, active listings, and local demand, and it is especially useful for understanding what a home would sell for today. It is often faster and less expensive than an appraisal, and it can help couples decide whether to sell, refinance, or pursue a buyout. However, it is typically not a substitute for an appraisal when a court requires a formal valuation.
Property tax assessments and online estimates can offer a rough reference point. They are usually based on mass appraisal models or automated algorithms and may not reflect interior condition, recent upgrades, or local market shifts. These figures are helpful for early conversations but should not be used as the basis for a final settlement.
Certified Pricing Professionals in the Divorce Process
Couples who need market-based pricing guidance can benefit from working with a certified pricing professional. C-REPS professionals are active real estate agents and brokers who have been trained and tested through the National Association of BPO Professionals (NABPOP) certification program. The designation requires specialized training, passing certification exams, meeting performance requirements, maintaining membership, and following a professional code of ethics. They are part of a collaborative network, so a couple working with one member can draw on broader local market knowledge.
It is important to be clear about roles. C-REPS professionals are not appraisers, and their pricing analysis does not replace a court-required appraisal. Where a judge, mediator, or lender needs a formal valuation, couples should obtain one from a licensed or certified appraiser. A C-REPS pricing analysis is most valuable for understanding current buyer demand, preparing a home for sale, setting a realistic list price, and evaluating whether an offer reflects the market. In many divorces, both tools are used together: an appraisal for the legal record and a market analysis for the sale or buyout decision.
The Tax Issues That Often Go Overlooked
Property transfers between spouses during marriage, and transfers incident to divorce, are generally not taxable events under Internal Revenue Code Section 1041. The receiving spouse takes the transferor’s cost basis, which means the tax consequences are deferred until the property is eventually sold. This carryover basis is critical. Two homes with the same market value can have very different tax outcomes if their original purchase prices differ.
The home sale exclusion under Section 121 may also apply. A single filer can generally exclude up to $250,000 of gain from the sale of a principal residence, and a married couple filing jointly can exclude up to $500,000, provided ownership and use requirements are met. Special rules allow a spouse who moves out to continue to be treated as using the home while the ex-spouse lives there under a divorce or separation instrument, so long as the other requirements are satisfied. Couples should review these rules with a tax professional before deciding who keeps the home and when it should be sold.
Mortgage refinancing, mortgage assumption, and the release of one spouse from liability also carry financial consequences. A spouse who keeps the home may need to refinance into a single name, and lenders will evaluate income and credit independently. Valuation provides the equity figure, but lending approval is a separate step that should be checked early.
Comparing Common Settlement Approaches
Most couples resolve the home in one of three ways, and each has advantages and trade-offs.
A sale and division of proceeds is often the cleanest solution. The home is listed, sold at market value, and the net proceeds after the mortgage and selling costs are divided according to the settlement. This approach relies heavily on an accurate pricing strategy, because an overpriced listing can sit unsold for months while carrying costs accumulate. It also removes both spouses from ongoing financial ties to the property.
A buyout allows one spouse to keep the home by paying the other spouse for their share of the equity. This requires a reliable valuation and a clear method for calculating the payment. The spouse keeping the home must usually qualify for a mortgage or have sufficient liquid assets. Buyouts preserve stability for children or for a spouse who values the home, but they can strain finances if the equity payment is large relative to income.
A deferred sale allows one spouse to remain in the home for a set period, often until children finish school or until a market condition improves. The decree must specify who pays the mortgage, taxes, insurance, and repairs, and when the sale will occur. This option can reduce short-term disruption, but it can also create lingering conflict if expectations are not clearly defined.
A Step-by-Step Approach to Accurate Valuation
The most effective settlements follow a structured process that keeps the numbers transparent.
Begin by gathering documents. This includes the deed, mortgage statements, property tax records, closing statements from the original purchase, records of significant improvements, and any evidence of premarital ownership or separate contributions. Organized records reduce disputes and speed up the valuation.
Next, confirm the valuation date with an attorney. Once the date is established, give the appraiser or pricing professional a clear written scope that identifies the date, the property, and the purpose of the valuation.
Then obtain the appropriate valuation. If the court or a mediator requires an appraisal, order it from a licensed or certified appraiser. If the couple needs help understanding the market or preparing for a sale, arrange a market analysis from a qualified professional. In some cases, both steps are necessary.
Calculate the equity by subtracting the mortgage balance, liens, and any agreed adjustments from the valuation. Consider selling costs if the property will be sold, since commissions, closing costs, and repairs reduce the net proceeds.
Finally, document the agreement. Include the valuation figure, the date, the method used to calculate equity, and the terms of any buyout, sale, or deferred arrangement. Attorneys often incorporate these details into the marital settlement agreement or decree.
Common Mistakes That Lead to Unfair Outcomes
Several errors appear again and again in divorce valuations. The first is relying on a single online estimate. Automated values can be far off, particularly for homes with unique features or recent renovations. A second opinion, or a formal appraisal, is worth the cost when significant money is at stake.
A second mistake is ignoring selling costs when comparing a sale to a buyout. A spouse who keeps the home may receive a valuation that seems fair, but if the sale comparison omits commissions and closing costs, the numbers will not match. Consistency in assumptions matters.
A third mistake is failing to account for improvements and contributions. A spouse who paid for a major renovation with separate funds may be entitled to a credit, depending on the state. Without documentation, these claims are difficult to prove.
A fourth mistake is delaying the valuation until the eve of trial. Early valuation supports better negotiation and gives both spouses time to plan financially.
Practical Examples
Consider a couple married for twelve years in a state that uses equitable distribution. They own a home with a market value of $540,000 and a mortgage balance of $300,000. The equity is $240,000. One spouse wants to keep the house and can refinance based on their income. An appraisal establishes the value as of the date of separation, and the parties agree that the spouse keeping the home will pay the other half of the equity, adjusted for an agreed credit for a roof replacement paid from a separate account. The valuation makes the buyout calculation transparent and defensible.
In a second example, a couple in a community property state disagrees about whether the home should be sold. One spouse believes the market is strong and wants to list quickly. The other prefers to wait. A market analysis from a C-REPS professional shows recent comparable sales, current inventory, and buyer activity in the neighborhood, and it recommends a list price range. The couple uses this information to make a decision based on current conditions rather than assumptions.
A third example involves a home that one spouse owned before the marriage. The original down payment came from that spouse’s premarital savings, while the mortgage was paid from joint funds during the marriage. An appraisal and a review of mortgage records help the attorney trace the premarital equity and the marital contributions. The resulting settlement reflects both the separate and marital components of the property.
Actionable Advice for Couples
Start with a conversation about goals. Decide whether the priority is stability for the children, a clean financial break, or the fastest path to a sale. Clear goals make valuation decisions easier.
Ask your attorney which valuation date and property rules apply in your state. Do not assume that the date of filing or the date of trial is the correct one.
Choose professionals who understand divorce matters. Ask appraisers about experience with court-required reports, and ask pricing professionals about their certification, training, and approach to local market data. Confirm fees in writing and make sure the scope of work matches the purpose.
Keep detailed records of mortgage payments, improvements, and any funds from separate sources. Organized documentation is often the deciding factor when contributions are disputed.
If you plan to buy out your spouse, speak with a lender early to confirm that you can qualify for refinancing. A valuation is only useful if the financing is available to act on it.
If you plan to sell, consider a market analysis before choosing a list price. A realistic price shortens time on the market and reduces the chance of a prolonged dispute over selling costs.
Comparing Valuation Support Options
Couples typically choose among three levels of valuation support, and the right choice depends on the stakes and the level of disagreement.
A formal appraisal provides the most rigorous and defensible number, and it is usually the right choice when a court or lender requires it or when spouses disagree about value. It is the most expensive option but often the most cost-effective when the equity at stake is substantial.
A market analysis from a trained pricing professional is ideal for sale planning, pricing strategy, and understanding current buyer demand. It is faster and less costly than an appraisal, and it can inform negotiations even when a formal valuation is also needed.
Online estimates and tax assessments are useful for early discussions and for getting a general sense of range. They should not serve as the final basis for a settlement, particularly when the outcome involves a buyout or a court filing.
Frequently Asked Questions
Does the court always require a formal appraisal in a divorce?
Not always. Courts often require a formal appraisal when the parties cannot agree on value or when the division depends on a precise number, such as a buyout. When both spouses agree on a reasonable valuation, the court may accept a market analysis or a stipulated value. Local rules and the judge’s preferences also play a role, so an attorney can confirm what is expected.
Who pays for the home appraisal in a divorce?
Costs are commonly shared equally, allocated in proportion to income, or assigned by the court as part of the overall settlement. The arrangement is often spelled out in the temporary orders or the marital settlement agreement. Keep receipts and confirm payment responsibilities before the appraiser begins work.
Can I use a real estate agent’s price estimate instead of an appraisal?
You can use an agent’s market analysis to understand current value and to plan a sale or buyout, but it generally will not satisfy a court requirement for a formal appraisal. If your settlement or court filing requires one, you will need a licensed or certified appraiser. A certified pricing professional can still be valuable for market context alongside the appraisal.
What happens if the home has increased in value since we separated?
The answer depends on your state’s rules and the valuation date. In some states, post-separation appreciation may be treated as separate property or shared, depending on the source of the increase. Your attorney can explain how appreciation is handled and whether your facts support an adjustment.
How does a home sale affect taxes after divorce?
A transfer of property incident to divorce is generally not taxable at the time of transfer, and the receiving spouse takes the original cost basis. When the home is sold, capital gains may apply, but the Section 121 exclusion may reduce or eliminate the tax if ownership and use requirements are met. A tax professional can review your specific situation.
Can I keep the house if I cannot afford the mortgage on my own?
It may be difficult, but it is not impossible. Lenders evaluate your income, credit, and debt-to-income ratio separately from the divorce. You may need to consider a smaller mortgage, a longer payoff timeline, or a settlement that includes other assets to offset the equity. Speak with a mortgage professional early to understand your options before agreeing to a buyout.
What if my spouse refuses to agree on the value?
Disagreements are common. Options include ordering a second appraisal, requesting a review of the original report, using mediation to narrow the gap, or asking the court to decide. Clear documentation and a neutral professional process usually resolve disagreements more efficiently than prolonged litigation.
Should we sell the house during the divorce or wait until it is final?
Selling during the divorce can simplify finances and reduce conflict, but timing depends on your goals, the market, and whether you have children who need stability. Some couples choose a deferred sale with written terms. Discuss the advantages and risks with your attorney before listing the property.
FIRPTA Foreign Property Sales: What Sellers Need to Know Before Closing
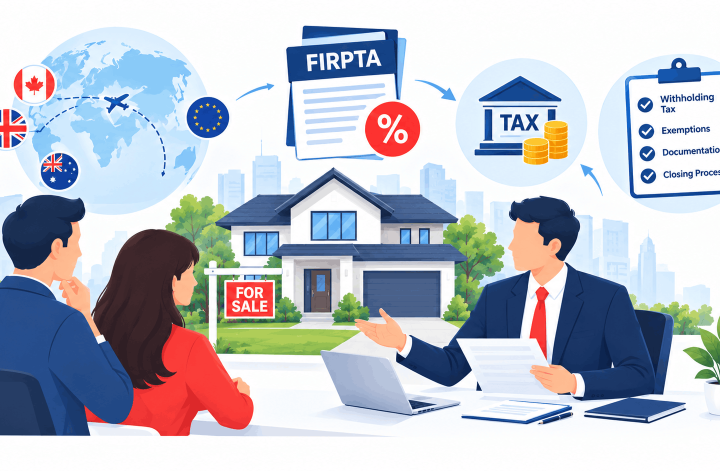
Selling a U.S. property when you live outside the country brings a layer of tax and legal obligations that domestic sellers never face. The most important of these is the Foreign Investment in Real Property Tax Act, known as FIRPTA. Understanding FIRPTA before you list your home, condo, or investment property protects your proceeds, keeps your closing on schedule, and helps you avoid penalties that can follow a sale for years.
This guide explains how FIRPTA foreign property sales work, who it applies to, how withholding is calculated, which exemptions may apply, and what steps sellers should take to stay compliant.
What Is FIRPTA?
FIRPTA is a U.S. federal law, enacted in 1980, that taxes gains from the disposition of U.S. real property interests held by foreign persons. Congress passed it to ensure that foreign owners pay tax on U.S. real estate gains in the same way that U.S. citizens and residents do.
Under FIRPTA, the buyer is generally required to withhold a portion of the sale price and send it to the Internal Revenue Service (IRS) at closing. That withheld amount is credited toward the seller’s actual U.S. tax liability. If the withholding exceeds what the seller owes, the seller can claim a refund by filing a U.S. tax return.
Why FIRPTA Matters for Sellers
Many foreign sellers are surprised to learn that the withholding happens automatically at closing, not after the fact. Without planning, you may receive significantly less cash than you expected on closing day. Understanding the mechanics in advance lets you prepare the right documents and budget for timing differences.
Who Counts as a Foreign Seller?
FIRPTA applies based on the seller’s status for U.S. tax purposes, not simply where they currently live. The definition of a “foreign person” generally includes:
- Nonresident alien individuals
- Foreign corporations not engaged in a U.S. trade or business
- Foreign partnerships, trusts, and estates
A person who holds a U.S. green card or meets the substantial presence test may be treated as a U.S. resident for tax purposes, even if they spend most of their time abroad. Because these rules are technical, sellers with mixed residency should confirm their status before the transaction begins.
How FIRPTA Withholding Works
The standard withholding rate under FIRPTA is 15 percent of the amount realized on the sale. The amount realized generally includes the cash paid, the amount of any debt the buyer takes over, and the fair market value of other property transferred as part of the consideration.
A Practical Example
Suppose a nonresident seller sells a condominium for $500,000, with no mortgage assumed by the buyer. The buyer would typically withhold $75,000 at closing (15 percent of $500,000) and remit it to the IRS. The seller would receive the remaining $425,000, minus normal closing costs and any loan payoff.
If the seller’s actual capital gains tax is only $20,000, the seller can file a U.S. tax return to claim a refund of the $55,000 difference. Refunds are not instant, so sellers should plan their cash flow accordingly.
Reduced Withholding Options
In some cases, the withholding amount can be reduced. Sellers may be able to request a reduced amount through a withholding certificate issued by the IRS, typically using Form 8288-B, when the expected tax liability is lower than the default 15 percent. Applications must be submitted before closing, and processing takes time, so this step should be started early.
Exemptions and Special Cases
Not every foreign sale triggers the full FIRPTA withholding. Common exceptions include:
- Sale price of $300,000 or less when the buyer intends to use the property as a personal residence and the buyer’s residence requirements are met
- Sales to certain buyers who will use the property as their own home, subject to specific rules
- Properties sold by foreign persons who are actually U.S. residents for tax purposes, who should provide the appropriate certification
- Transactions where the seller provides a valid certification that they are not a foreign person, such as a properly completed Form W-9 in qualifying situations
Each exemption has conditions and documentation requirements. Sellers should not assume an exemption applies without confirming eligibility, because a buyer who withholds incorrectly or a seller who claims an exemption improperly can face consequences.
Required Documentation
Compliance depends on paperwork. Sellers should prepare the following where applicable:
- A valid U.S. taxpayer identification number, either a Social Security Number or an Individual Taxpayer Identification Number (ITIN)
- Form 8288, the U.S. Withholding Tax Return for Dispositions by Foreign Persons, which the buyer or closing agent typically files
- Form 8288-A, which reports the withholding to the IRS and provides the seller with documentation
- Form 8288-B, if seeking a reduced withholding certificate
- A signed certification of non-foreign status, when claiming an exemption that relies on it
- Form 1040-NR, the U.S. nonresident income tax return, if the seller needs to report the gain and claim a refund or pay additional tax
Keeping copies of every form submitted and received protects you during future audits and when claiming credits.
Common Compliance Mistakes to Avoid
Foreign sellers and their advisors often run into the same issues. Watch for these:
- Assuming the buyer or agent will handle everything without seller input
- Waiting until the closing date to gather tax identification numbers
- Overlooking state-level withholding or transfer taxes, which operate separately from FIRPTA
- Failing to file a U.S. return to claim a refund after excess withholding
- Ignoring currency conversion effects on reported gains and foreign tax credits in the seller’s home country
- Relying on outdated information from forums or secondhand sources
Foreign Seller Checklist
Before listing a U.S. property, work through these steps:
- Confirm your tax residency status with a qualified U.S. tax professional
- Obtain a U.S. taxpayer identification number if you do not already have one
- Estimate your capital gain and expected U.S. tax liability
- Decide whether to request a reduced withholding certificate and start the application early
- Communicate with the title company or closing attorney about FIRPTA forms
- Set aside funds to cover timing gaps if a refund is expected
- File the required U.S. return after closing to reconcile your tax position
Working With Professionals
FIRPTA sits at the intersection of tax law, real estate, and cross-border regulation. A single error can delay closing or lock up proceeds for months. Sellers benefit from a coordinated team that may include a U.S. CPA or enrolled agent familiar with nonresident returns, a real estate attorney licensed in the property’s state, and a title company experienced with foreign sellers.
Pricing also matters. A property priced without current local market data can sit longer or sell for less than it should, which compounds the financial impact of withholding. Sellers who want an accurate, defensible price can ask a C-REPS certified agent for a professional pricing analysis. C-REPS professionals are trained and certified through the National Association of BPO Professionals (NABPOP), follow a professional code of ethics, and can connect you with a network of colleagues if your transaction requires specialized support.
Conclusion
FIRPTA is manageable when you understand it early. Confirm your residency status, gather your tax identification number, decide whether a reduced withholding certificate makes sense, and build a coordinated team before you list. With preparation, a foreign property sale can close smoothly, and your proceeds can reach you on a predictable timeline.
Frequently Asked Questions
What is FIRPTA in simple terms?
FIRPTA is a U.S. law requiring buyers to withhold a portion of the sale price when a foreign person sells U.S. real estate. The withheld money goes to the IRS and is credited against the seller’s actual tax bill.
How much is FIRPTA withholding?
The default rate is 15 percent of the amount realized, which usually means the total sale price plus any debt the buyer assumes. A reduced rate may be available with an IRS withholding certificate.
Can a foreign seller avoid FIRPTA withholding?
Some sellers qualify for exemptions, such as certain sales of properties priced at $300,000 or less to buyers who will live there. Eligibility depends on specific conditions, so confirm before assuming an exemption applies.
Do I get my FIRPTA withholding back?
If the withholding exceeds your actual U.S. tax liability on the sale, you can claim a refund by filing a U.S. nonresident tax return. Refunds take time, so plan your finances for the gap.
Do I need a Social Security Number to sell property in the U.S.?
Not necessarily. Sellers without an SSN can apply for an Individual Taxpayer Identification Number (ITIN) using IRS Form W-7. Start the application early, since processing can take several weeks.
Does FIRPTA apply to state taxes too?
No. FIRPTA is federal. Some states impose their own withholding or transfer requirements on nonresident sellers, so check the rules for the state where the property is located.
Who files Form 8288?
Typically, the buyer or the closing agent files Form 8288 and the associated Form 8288-A with the IRS after closing. Sellers should confirm who is responsible in their purchase agreement.
Should I hire a professional for a foreign property sale?
Given the tax, legal, and timing complexity, most foreign sellers benefit from working with a U.S. tax advisor, a licensed real estate attorney, and an experienced agent who can provide accurate pricing.
Regional Real Estate Market Differences Explained
Two homes of similar size, age, and condition can sell for very different prices depending on where they are located. A three-bedroom house in one city may draw a dozen eager offers within days, while an almost identical property a few hours away may sit for months. Those gaps are the result of regional real estate market differences, and understanding them is one of the most practical steps a buyer, seller, or property owner can take.
This guide explains what makes local markets behave differently, how those differences show up in prices and timelines, and why local expertise matters when you make a major property decision.
Key Takeaways
Regional real estate market differences are driven by employment, supply, geography, costs, amenities, and financing conditions. These forces create distinct pricing patterns that national averages cannot capture. Buyers and sellers who understand their specific market make more informed decisions, avoid costly pricing mistakes, and move through transactions with greater confidence. Local expertise turns general data into practical guidance for your situation.
What Is a Regional Real Estate Market?
A regional real estate market is a group of properties that compete with each other for the same pool of buyers. The boundaries are rarely the same as city or county lines. A market might cover a single school district, a cluster of neighborhoods, or a stretch of waterfront that shares the same employers and commute routes.
Because buyers tend to shop within a certain radius, the homes in that radius set the pricing benchmark. A property’s value depends far more on what buyers in its immediate market are willing to pay than on national averages or headlines about the broader economy.
The Core Factors That Create Market Variation
Several forces combine to make each market distinct. Some are obvious, while others only become visible when you study local transaction data closely.
Local Employment and Income
Jobs drive housing demand. A region anchored by a large hospital system, a university, or a technology campus may see steady buyer interest, while a community dependent on a single industry can experience sharp swings when that industry slows. Household incomes also vary widely between neighborhoods, which affects what buyers can afford and how they prioritize features.
Housing Supply and Inventory
Supply is one of the strongest pricing forces. Some areas have limited land, strict zoning, or long permitting timelines, which keep inventory tight. Others have plenty of developable land and steady new construction. Low inventory often supports prices and speeds sales, while rising inventory gives buyers more negotiating room.
Geography, Climate, and Natural Risk
Physical features shape value in ways that are easy to overlook from a distance. Proximity to water, elevation, views, and sun exposure can add or subtract value. Flood zones, wildfire risk, coastal erosion, and hurricane exposure affect insurance costs and lender requirements, which in turn influence what buyers can pay. Climate also determines seasonal patterns, since some markets slow dramatically in winter while others stay active year-round.
Property Taxes, Insurance, and Fees
Two buyers looking at the same purchase price can face very different monthly costs. Property tax rates vary by jurisdiction, and some areas add special assessments or HOA fees that increase the total cost of ownership. Insurance premiums differ based on the local risk profile. Savvy buyers look at the full monthly payment, not just the listing price.
School Districts and Community Amenities
School boundaries, parks, transit access, and local services often carry significant weight with buyers. Even when two neighborhoods are only a few miles apart, a difference in school quality, walkability, or commute time can produce a meaningful price gap.
Regional Interest Rate Sensitivity
Mortgage rates affect every market, but not every market responds the same way. Areas with a high share of first-time buyers may react more quickly to rate changes, while luxury markets with more cash buyers may feel less impact. Local lending patterns and loan types also play a role.
How These Differences Show Up in Real Transactions
Abstract factors become concrete when you look at how properties actually sell. Consider the following comparison of how a typical property might perform in two different types of markets.
| Factor | Fast-Moving Urban Market | Slower Suburban or Rural Market |
| Typical inventory | Limited, with frequent bidding | Broader selection with more time to decide |
| Days on market | Often shorter | Often longer |
| Buyer competition | Higher, with some offers above asking | More moderate, with more room to negotiate |
| Price drivers | Walkability, transit, and employment hubs | Lot size, school quality, and commute time |
| Seller strategy | Price carefully to attract strong offers | Be patient and expect a longer timeline |
| Buyer strategy | Move quickly and prepare for competition | Compare options and negotiate on condition |
The table illustrates a key point: the same strategy does not work everywhere. A pricing approach that succeeds in one market can leave money on the table in another, or cause a listing to stall.
Why National Averages Can Be Misleading
National housing statistics are useful for understanding broad trends, but they smooth over the details that matter most to individual decisions. An average can hide a market that is booming next door to one that is flat or declining. A property that is priced according to a national trend may be overpriced in a softening local market or underpriced in a competitive one.
Local data, including recent comparable sales, days on market, price trends within specific neighborhoods, and the condition of nearby inventory, gives a far more accurate picture. This is why professional pricing relies on what buyers are actually paying in a specific area right now.
Practical Examples of Local Variation
Consider two homeowners who both want to sell a similar four-bedroom house.
The first homeowner lives in a neighborhood with very few listings and a long waiting list of interested buyers. A knowledgeable local agent may recommend a pricing strategy that generates multiple offers, while a poorly informed approach might underprice the home and leave thousands of dollars on the table.
The second homeowner lives in a community where inventory has been building for several months. Here, an aggressive asking price that ignores current conditions may cause the home to sit unsold, eventually requiring price reductions that signal weakness to buyers. Accurate pricing from the start protects both the timeline and the final result.
Buyers face similar challenges. A first-time buyer comparing two neighborhoods may see a lower price in one and assume it is the better deal. Local expertise can reveal that the lower-priced area carries higher insurance costs, a special assessment, or a longer commute that changes the true value.
Actionable Steps for Buyers, Sellers, and Owners
Whatever your goal, a few practical habits will help you navigate regional differences more effectively.
- Study hyperlocal data. Look at recent sales within a tight radius and within the same property type, rather than relying on citywide reports.
- Track inventory and days on market. These two numbers reveal whether conditions favor buyers or sellers in a specific neighborhood.
- Calculate total monthly costs. Include property taxes, insurance, HOA dues, and any assessments when comparing properties.
- Research natural risks early. Check flood maps, wildfire exposure, and insurance availability before making an offer.
- Ask about micro-markets. Two streets can behave differently, so ask a local professional how the specific block is performing.
- Revisit pricing regularly. For sellers, market conditions can shift within weeks. A pricing review every few weeks keeps a listing competitive.
Where Public Data Fits In
Public sources provide a strong foundation for understanding local conditions. They work best when combined with on-the-ground knowledge rather than used alone.
- U.S. Census Bureau (census.gov): Offers demographic and housing data at the neighborhood and county level.
- Bureau of Labor Statistics (bls.gov): Provides local employment and wage data that help explain demand.
- Federal Housing Finance Agency (fhfa.gov): Publishes house price indexes that track trends across regions.
- Consumer Financial Protection Bureau (consumerfinance.gov): Offers guidance on mortgages, closing costs, and buyer rights.
Public data reveals patterns, but it may lag behind current conditions. A recent price cut on a nearby property, a new development announced last month, or a shift in buyer demand may not appear in these reports yet. This is where experienced local professionals add value.
The Role of Local Expertise
Local expertise is the ability to interpret market data in context. An experienced professional knows which comparable sales are truly relevant, which features buyers in a specific area value most, and how seasonal patterns or recent developments might affect the next few months.
This expertise matters most during high-stakes decisions, such as pricing a home for sale, making an offer in a competitive market, or estimating the value of a property you plan to keep. Mistakes in these moments can be costly, and they are often difficult to reverse.
How C-REPS Professionals Approach Local Pricing
C-REPS (Certified Real Estate Pricing Specialists) is a network of certified, professional real estate agents and brokers who specialize in accurate property pricing and market expertise. C-REPS professionals are trained, tested, and certified through the National Association of BPO Professionals (NABPOP) certification program. The designation requires specialized training, certification exams, performance requirements, continuing membership, and adherence to a professional code of ethics.
Because C-REPS professionals are active agents and brokers rather than appraisers, they combine systematic training with ongoing, real-market knowledge of what buyers are willing to pay today. Their work is also supported by a collaborative network, so clients can benefit from shared insight across markets rather than relying on a single agent’s perspective.
When you are weighing a pricing decision in a specific area, a conversation with a certified local professional can help you see the details that national data and online estimates often miss.
Frequently Asked Questions
Why do home prices vary so much between nearby towns?
Nearby towns can have different school districts, tax rates, zoning rules, employment bases, and natural risks. Buyers compare these factors when deciding where to live, so even small differences can produce noticeable price gaps.
What is a regional real estate market?
A regional real estate market is the area where buyers and sellers compete for similar properties. Its boundaries often follow commute patterns, school zones, and shared amenities rather than official city or county lines.
Does local expertise really change the outcome of a sale?
Yes. Local expertise helps sellers set a price that attracts qualified buyers and helps buyers identify fair value. Knowing recent comparable sales and neighborhood trends often leads to better timing, pricing, and negotiation.
Are online home value estimates accurate?
Online estimates can be a useful starting point, but they rely on automated models and may not reflect recent sales, property condition, or micro-market conditions. They are best used as one input among several rather than as a final answer.
How can I tell if a market favors buyers or sellers?
Watch inventory levels, days on market, and the share of listings that sell above or below asking price. Rising inventory and longer selling times generally favor buyers, while low inventory and quick sales generally favor sellers.
Should I consider insurance and taxes when comparing neighborhoods?
Absolutely. Property taxes, insurance premiums, and HOA fees can significantly change the monthly cost of owning a home. Comparing total monthly costs gives a clearer picture than comparing purchase prices alone.
How often should a seller review the listing price?
Sellers should review pricing regularly, especially in markets where conditions change quickly. A review every few weeks, or whenever comparable listings sell or new inventory appears, helps keep the home competitive.
Do market differences matter if I am buying a property in a single area?
They matter even more. Within one metro area, micro-markets can differ by street, school zone, or neighborhood character, so understanding the specific area you are buying in is essential.
Housing Inventory Levels and Their Effect on Home Prices
Few numbers in real estate get quoted as often as housing inventory. Local news reports mention it, economists track it, and buyers and sellers feel it in every negotiation. Yet many people still aren’t sure what inventory actually measures or how it moves prices up and down. This guide explains the link between housing inventory and home prices, why the same listing count can mean very different things in different markets, and what buyers and sellers can do with that knowledge.
What Housing Inventory Means
Housing inventory is the number of homes available for sale in a given area at a given time. It usually refers to active listings, meaning homes that are on the market and open to offers. Some analysts also count pending sales or homes that have been listed for a short period.
On its own, a raw count tells you little. Ten thousand listings sounds like a lot until you learn that a city has 200,000 homes and normally sees 15,000 listings at any moment. Inventory becomes useful when it is measured against something, which is why analysts rely on a few standard ways of looking at it.
Common Ways to Measure Inventory
Analysts and agents typically look at inventory in one of these forms:
- Active listings: The total number of homes currently for sale in an area.
- Months of supply: How long the existing inventory would take to sell at the current pace of sales. A market with six months of supply is generally considered balanced, while lower figures lean toward a seller’s market and higher figures lean toward a buyer’s market.
- Inventory compared with historical averages: Whether current listings are above or below what is normal for the same season and location. This matters because listings naturally rise in spring and fall off in winter.
The months of supply figure is the one most closely tied to price behavior, because it expresses the balance between buyers and sellers in a single number.
The Basic Economics: Supply and Demand
Housing follows the same basic logic as any other market. Prices tend to rise when demand outpaces supply and fall when supply outpaces demand. Inventory is the supply side of that equation, and buyer activity (mortgage rates, employment, household formation, and consumer confidence) is the demand side.
When inventory is scarce, buyers compete for a small number of homes. Competition pushes offers higher, shortens time on market, and makes concessions like inspection waivers or price reductions less common. When inventory is abundant, buyers have more choice, negotiate more, and sellers may need to reduce prices or offer incentives to attract offers.
Why Housing Responds Differently Than Other Goods
Housing has a few characteristics that make the supply and demand relationship slower and more complicated than in many other markets:
- Building takes time. New construction can take many months or years from approval to completion, so supply cannot respond quickly to a sudden jump in demand.
- Owners don’t have to sell. Many homeowners hold properties for decades, so the supply of listings depends partly on personal decisions like job moves, life changes, and financial needs.
- Locations are fixed. A shortage in one neighborhood cannot be fixed by building in another, which is why local conditions matter so much.
Because of these factors, housing markets can stay out of balance for long periods, which is part of why pricing pressure builds and fades in cycles.
How Low Inventory Creates Upward Pricing Pressure
Low inventory is one of the most common drivers of rising home prices. When there are fewer homes than buyers, several effects tend to appear at once.
Multiple offers become more frequent. A home priced at a level buyers consider fair may attract several bids, and the winning offer may exceed the asking price. Buyers who want to stand out may waive contingencies or write larger earnest money deposits. Sellers gain leverage, and listing prices may be set conservatively to encourage a bidding contest.
A Practical Example
Consider two neighborhoods with identical homes. In the first, a three-bedroom house is listed at a fair price and receives four offers within a week. The buyers compete, and the home sells above asking. In the second neighborhood, the same house sits for six weeks and eventually sells below its original list price after one reduction. The homes are equal in size and condition, but the inventory conditions differ, and that difference drives the result.
This example shows why agents and appraisers focus on local conditions rather than national headlines. A national inventory figure may suggest a balanced market while a specific price range in a specific county is very tight.
How High Inventory Affects Prices
When inventory rises above typical levels, pricing pressure generally shifts toward buyers. Homes may sit longer, price reductions become more common, and sellers may face a gap between their expectations and what the market will pay.
High inventory does not automatically cause prices to crash. In many cases, prices simply stop rising as quickly, flatten, or adjust modestly in specific segments. The effect depends on how much inventory exceeds normal levels, how long the imbalance lasts, and whether buyers can access financing. A market with high inventory but strong employment and steady mortgage access may see only a slowdown, while a market with high inventory and widespread job losses may see sharper declines.
Segments Don’t Always Move Together
Inventory conditions often vary by price range, property type, and neighborhood. A market may have plenty of luxury homes sitting unsold while starter homes remain scarce and competitive. Looking at an overall average can hide these differences, so buyers and sellers benefit from examining the segment that matches their own situation.
Comparing Tight and Balanced Markets
The table below summarizes how common conditions tend to differ across market types. These are general patterns, and local results can vary.
| Factor | Tight Inventory Market | Balanced Market | Soft Inventory Market |
| Typical months of supply | Low | Around six months | High |
| Negotiating power | Sellers | Shared | Buyers |
| Time on market | Short | Moderate | Longer |
| Price reductions | Uncommon | Occasional | Frequent |
| Offer behavior | Competitive bidding | Normal negotiation | Few or no competing offers |
| Typical buyer strategy | Move quickly, prepare strong offers | Compare options carefully | Take time, negotiate hard |
Other Forces That Interact With Inventory
Inventory is important, but it does not operate alone. Several other factors shape how inventory translates into prices.
Mortgage Rates
Interest rates affect how much buyers can afford. When borrowing costs fall, buyers can support higher prices, which can absorb inventory quickly. When rates rise, purchasing power shrinks, and buyers may pull back even when inventory is limited. In some cases, owners with low-rate mortgages choose not to sell, which can keep listings scarce even as demand weakens.
Employment and Income
Local job growth brings new households into a market and increases demand. Layoffs or industry downturns can reduce demand quickly, which may push inventory higher even if few new homes are built.
New Construction
Builders respond to market conditions, but with a lag. A period of strong demand may lead to a wave of new homes that arrive after the pressure has already eased. Construction costs, land availability, and zoning rules all influence how much new supply comes to market.
Seasonal Patterns
Inventory typically rises in spring and summer, when families often prefer to move, and falls in late fall and winter. Comparing a spring listing count with a winter count can make a market look more or less balanced than it really is. Analysts usually compare the same season year over year for this reason.
Practical Advice for Buyers
Understanding inventory can help buyers plan their search and their offers.
- Check months of supply for your specific area and price range. A citywide figure may not reflect the homes you are interested in.
- Track how long homes take to sell. Rising days on market may signal more room to negotiate.
- Get pre-approved early. In a competitive market, a strong financing position makes your offer more credible.
- Plan for different scenarios. In a tight market, you may need to act quickly and decide what concessions you can accept. In a softer market, you may have time to inspect carefully and negotiate terms.
- Consider a professional pricing review. A thorough comparative market analysis helps you judge whether a home’s price reflects current conditions.
Practical Advice for Sellers
Sellers face the opposite challenge: making sure a home is priced and presented to meet the market as it actually exists.
- Price based on current sales, not last year’s numbers. Inventory conditions can shift in a few months, so recent comparable sales matter most.
- Watch the competition. Homes listed at the same time and price range are your real competitors, and they affect buyer choices.
- Prepare for longer timelines in high-inventory markets. Plan finances and your next move with the possibility of a slower sale in mind.
- Avoid overpricing in soft markets. A home priced well above the market may sit, get reduced, and sell for less than a realistic initial price would have brought.
- Present the home well. In a crowded market, condition, presentation, and clear listing details help a home stand out.
How Professional Pricing Helps Interpret Inventory
Inventory data is only as useful as the interpretation behind it. A raw listing count does not tell you whether a home is priced correctly, whether a neighborhood is about to shift, or how a particular property compares with its real competition.
This is where trained, locally focused professionals add value. C-REPS (Certified Real Estate Pricing Specialists) are active real estate agents and brokers who complete specialized pricing training through the National Association of BPO Professionals (NABPOP) certification program. The designation requires passing certification exams, meeting performance requirements, maintaining membership, and following a professional code of ethics. C-REPS professionals combine that systematic training with real knowledge of what buyers are willing to pay in their local market today, which is exactly the kind of insight needed to read inventory correctly.
Working with a C-REPS professional also gives clients access to a collaborative network rather than a single agent working alone. For sellers, that can mean more accurate pricing from the start. For buyers, it can mean a clearer picture of which offers are realistic and which homes are truly competitive.
If you want a grounded view of how current inventory conditions affect a specific home or neighborhood, a conversation with a C-REPS agent or broker is a helpful next step.
Frequently Asked Questions
Does high housing inventory always lower home prices?
Not always. High inventory usually slows price growth and gives buyers more negotiating power, but prices may hold steady or fall only modestly. The outcome depends on how far inventory exceeds normal levels, how long it lasts, and whether buyers can still access financing.
What is a good number of months of supply?
Around six months of supply is commonly considered a balanced market, where neither buyers nor sellers hold a strong advantage. Figures well below that tend to favor sellers, while figures well above it tend to favor buyers. Local context always matters.
Why do home prices rise when inventory is low?
When there are fewer homes for sale than buyers want, buyers compete for the available properties. That competition drives offers above asking prices and reduces the room for negotiation, which pushes prices upward.
Can inventory change quickly?
Yes. Listings can rise or fall within a few months as seasons change, interest rates move, or local employment shifts. Construction takes longer to respond, so new supply often arrives after conditions have already changed.
How do mortgage rates affect inventory and prices?
Higher rates reduce how much buyers can borrow, which can cool demand and soften prices. Lower rates can increase demand. Rates also influence whether owners choose to sell, since many homeowners with low-rate loans prefer to stay put.
Should I wait for inventory to rise before buying?
That depends on your finances, timeline, and local market. Waiting for more inventory may give you more choice and negotiating room, but prices and rates can move in either direction. A local professional can help you weigh those trade-offs for your situation.
How can I find current inventory data for my area?
Local multiple listing services, real estate associations, and government housing data sources publish inventory figures. The National Association of Realtors and the U.S. Census Bureau are useful starting points for national and regional data. A local agent can provide neighborhood-level detail.
How Interest Rates Affect Property Values: Expert Analysis
Few forces shape the housing market as directly as interest rates. When mortgage rates move, buyers’ budgets change, sellers’ pricing decisions change, and the number of homes that actually sell changes with them. Yet many people still ask a simple question: if rates go up, do home values fall?
The honest answer is that interest rates influence property values through several channels at once, and those channels do not always move in the same direction. This analysis explains how rates affect what buyers can pay, why the link between rates and prices is not one-to-one, what current forecasts suggest for 2026, and how professionals who specialize in accurate pricing account for rate changes when they value a home.
How Interest Rates Reach Property Values
Most homes are bought with a mortgage, so the interest rate on that loan becomes a central part of the price a buyer can afford. A property’s market value is not set by rates alone, but rates shape the pool of people who can pay a given price and the terms under which they are willing to pay it.
Three channels do most of the work.
The Affordability Channel
The most direct effect is on monthly payments. Consider a buyer borrowing $400,000 on a 30-year fixed mortgage. At 6%, the principal and interest payment is about $2,398 per month. At 7%, it rises to about $2,661, roughly $263 more each month, or about 11% higher, for the same loan amount.
Put differently, if a buyer can comfortably afford $2,398 per month, a 7% rate reduces the loan they can support to about $360,000. That is roughly 10% less purchasing power for the same budget. Every percentage point increase in mortgage rates reduces what a given income can buy by a similar order of magnitude.
When many buyers lose purchasing power at once, demand softens. Weaker demand usually shows up first in fewer offers, longer time on the market, and more negotiation, and only later in lower prices.
The Buyer Demand Channel
Rates also affect how many people decide to enter the market at all. Higher rates generally reduce buyer demand, and some buyers choose to wait for better conditions. Tembo, a mortgage advisory firm, has argued that if rates stay at or near current levels, more buyers may hold off purchasing, and that an overpriced home will struggle to sell in that environment.
This is one reason rate changes can matter more than their size suggests. A fall in rates can bring buyers back quickly, and the surge in demand can push prices up if supply does not keep pace.
The Lock-In Channel
The third channel is less obvious. Many homeowners locked in low mortgage rates during the years when borrowing was cheap. Those owners have a strong financial reason to stay put, which keeps the supply of existing homes for sale low. Morgan Stanley strategists have pointed to this lock-in effect as a factor that has constrained supply and supported higher prices, even when rates are elevated.
This creates a counterintuitive result. High rates reduce buyer demand, but they can also reduce supply, so prices may hold up better than a simple affordability model would predict. The net effect depends on which force is stronger in a given market.
Why the Relationship Is Not Simple
Rates and prices move together in many periods, but the relationship is not a fixed formula. Economic conditions can change how rates affect values.
During periods of strong economic growth and rising incomes, buyers may be willing to pay more even when rates are higher, which can keep prices firm. During periods of economic weakness, higher rates can reduce both demand and prices more sharply.
The housing market’s history illustrates this. The period before the 2008 financial crisis involved rising prices and widespread borrowing, followed by a sharp decline in values and sharp changes in lending conditions. Today’s market differs in important ways, including the prevalence of fixed-rate loans and the level of homeowner equity, so historical episodes should be read as context rather than a forecast.
Rates also reach valuations through the financing environment. Investors who buy property with borrowed money feel rate changes directly in their carrying costs, which affects how much they are willing to pay for rental and commercial properties. Residential buyers, meanwhile, respond to monthly payments and their personal budgets.
What Current Forecasts Show
Forecasters are not in full agreement about where rates and prices are headed, which is itself a useful signal about uncertainty.
Freddie Mac’s Primary Mortgage Market Survey put the average 30-year fixed rate in a range of roughly 6.11% to 6.25% in early 2026. Forecasts for the end of 2026 vary. The Mortgage Bankers Association projects rates near 6.4%, Realtor.com projects about 6.3%, and Fannie Mae has been more optimistic, expecting around 5.9%. Morgan Stanley strategists have suggested rates could decline to around 5.75%, particularly in the first half of the year.
For prices, the picture is similarly mixed. Zillow forecasts that home values will rise just 1.2% this year, while Cotality, a real estate analytics firm, has reported that annual home price appreciation slowed from 3.4% in January to 1.1% by October, a slowdown it attributed to elevated mortgage rates and persistent affordability challenges. Cotality’s own forecast projects future annual growth of 4.3% for October 2026, and it warns that a notable drop in rates combined with low supply could reaccelerate price gains.
| Indicator | Forecast Range Cited | Key Takeaway |
| 30-year rate, end of 2026 | About 5.75% to 6.4% | Forecasters expect modest movement, with no consensus on direction |
| Home price change | About 1% to 4% | Growth is expected to be slower than in recent peak years |
| Inventory | Gradual improvement | Supply is expected to rise slowly, supporting more balanced conditions |
The lesson from these forecasts is that rates and prices are linked through the supply side as well as the demand side. A rate decline alone does not guarantee falling or rising prices. The combination of rates, supply, and local demand determines the outcome.
Rate Changes Do Not Hit Every Property Equally
One of the most important insights for anyone analyzing property values is that interest rates affect different segments of the market in different ways.
Entry-Level Homes
Starter homes and lower-priced properties are often most sensitive to rate changes. Buyers in this segment tend to rely heavily on mortgage financing, and a small change in rate can change qualification for a loan. When rates rise, the number of qualified buyers can drop quickly, which can put pressure on prices in the most affordable price bands.
Higher-Priced Homes
Buyers of higher-priced homes may use more cash or have more financial flexibility, so rate changes can affect them differently. Some buyers in this segment are less sensitive to a half-point change, while others still face meaningful differences in monthly costs.
Investment Properties
Investors feel rates through financing costs, rental yields, and the spread between borrowing costs and expected returns. When rates rise, investors often demand lower purchase prices to earn their target return. When rates fall, they may be willing to pay more, which can lift values in rental-heavy neighborhoods.
Local Markets
National averages can hide enormous variation. A market with rising inventory and softer employment may see prices fall even as the national trend is flat. A market with limited new construction and strong job growth may see prices rise despite high rates. This is why a national rate forecast is a starting point, not a valuation tool.
The Valuation Side: How Professionals Account for Rates
A property’s value is ultimately what a willing buyer will pay, and that figure depends on current financing conditions. For this reason, accurate pricing requires professionals to account for rates rather than relying on past sales alone.
C-REPS professionals are licensed real estate agents and brokers who complete specialized pricing training through the National Association of BPO Professionals (NABPOP) certification program. Their work emphasizes what buyers are actually willing to pay in a specific local market today. In a higher-rate environment, that often means paying close attention to how buyers are responding to listings, how many are qualifying at current payment levels, and whether recent sales reflect the financing reality of this period rather than an earlier one.
Rates matter for valuation in several practical ways:
- Recent sales may reflect different financing conditions. A home that sold during a low-rate period may not be a reliable comparison for a home listed when rates are higher.
- Buyer pool size matters. If fewer buyers can afford a given price, the likely sale price may need to adjust.
- Time on market is a signal. Longer listing periods can indicate that a price is out of step with current buyer willingness to pay.
- Concessions tell a story. Seller credits, rate buydowns, and closing cost help can reveal how much buyers need financial relief to complete a purchase.
A useful principle is to ask whether a comparable sale reflects the same market conditions you face today. If the answer is no, the sale still matters, but it needs adjustment.
Practical Examples
Example One: A Seller in a Higher-Rate Market
Suppose a homeowner in a mid-sized metro area believes their home is worth what a similar home sold for two years earlier, when mortgage rates were noticeably lower. Their neighbor’s sale may still be useful, but the current buyer pool is smaller at today’s rates. A pricing professional would compare recent sales from the past several months, check how many similar homes are currently listed, and look at how quickly they are selling. The likely conclusion is that the home should be priced to current buyer capacity rather than the peak of the earlier market.
Example Two: A Buyer Deciding Whether to Wait
A buyer considering a $400,000 home has two possibilities. At a 6% rate, their payment is about $2,398 per month. If they wait and rates fall to 5%, that payment drops to about $2,147, a difference of roughly $250 per month. But if prices rise while they wait, or if rates rise instead, the advantage disappears. A buyer who can afford the monthly payment today and plans to stay in the home for several years may find that waiting has a real cost. A buyer who is stretched to afford the payment may benefit from a longer wait, but only if they have a clear plan for their finances in the meantime.
These examples show why there is no universal answer. The right decision depends on payment capacity, time horizon, local supply, and the price being negotiated.
Actionable Advice for Buyers, Sellers, and Investors
For buyers:
- Calculate your monthly payment at several rate levels, including one or two percentage points higher than today’s rate, before setting a budget.
- Get pre-approved with more than one lender, since rate and fee differences can meaningfully change your payment.
- Look at homes in the context of local sales and time on market, not only the list price.
- Consider whether a rate buydown, seller credit, or lender credit could offset the payment more effectively than waiting.
For sellers:
- Price based on current buyer capacity, not on a peak market you remember.
- Ask your agent to explain how recent comparable sales reflect today’s financing conditions.
- Be prepared for buyers to ask for concessions when rates are high, and decide in advance what you are willing to offer.
- If the market is slow, act early on pricing adjustments rather than waiting for a rate change to rescue the listing.
For investors:
- Stress-test your returns at higher financing costs, not only at current rates.
- Compare the expected rental yield with your borrowing cost, and avoid assuming that falling rates will automatically lift values.
- Consider how refinancing options and fixed versus variable loan structures affect your risk.
- Recognize that lock-in effects can keep supply tight in some areas, which may support values even when demand softens.
The Bottom Line
Interest rates influence property values through affordability, buyer demand, and the supply of homes for sale, and their effects vary by price range, property type, and local market. Forecasts for 2026 do not agree on the direction of rates or prices, which is a reminder that the relationship depends on many factors at once.
The most useful approach is to focus on what rates mean for your specific situation: your monthly payment, your time horizon, and the comparable sales in your area. For buyers, that means budgeting realistically. For sellers, it means pricing to current buyer capacity. For investors, it means stress-testing returns against higher financing costs. Accurate pricing grounded in local data remains the most reliable way to navigate a market where rates keep shifting.
Frequently Asked Questions
Do higher interest rates always lower home prices?
No. Higher rates usually reduce buyer demand and purchasing power, which can soften prices, but they can also reduce supply because homeowners with low rates are less likely to sell. The net effect depends on local supply and demand, employment, and economic conditions.
How much does a 1% rate increase affect a mortgage payment?
It depends on the loan size and the starting rate. On a $400,000 30-year loan, moving from 6% to 7% increases the monthly principal and interest payment by about $263, or roughly 11%.
Will mortgage rates go down in 2026?
Forecasts differ. Some expect rates to decline modestly by the end of 2026, while others expect them to stay near current levels. No forecast can guarantee the direction, so buyers and sellers should plan for a range of outcomes.
Why are home prices not falling more when rates are high?
Several factors can keep prices from falling sharply. Many homeowners have low locked-in rates and are reluctant to sell, which limits supply. Demand for housing also remains strong in some areas, and high construction costs can limit new supply.
Does a rate drop always make homes more expensive?
Not always, but it can. Lower rates can bring more buyers into the market quickly. If supply is limited, that extra demand can push prices up. If supply is growing, the effect may be smaller.
Should I wait for lower rates before buying a home?
It depends on your finances and your plans. Waiting can make sense if you need more time to build savings or if rates fall enough to offset potential price increases. Buyers who can afford the current payment and plan to stay for several years often find that the cost of waiting is higher than expected.
How do professionals factor interest rates into home pricing?
Pricing professionals look at recent comparable sales, time on market, buyer activity, and concessions. They consider whether past sales reflect current financing conditions and adjust their analysis when they do not.
Can rate buydowns or seller credits offset high rates?
They can reduce the effective cost of a loan in some situations, but the details matter. Buydowns, credits, and fee structures vary, so buyers should compare the total cost of different options rather than focusing only on the headline rate.
Real Estate Market Trends 2026: What C-REPS Professionals Are Seeing
Every year brings a new set of headlines about where housing is headed. Some predict a crash, others predict a boom, and most buyers and sellers are left unsure what to do. The real estate market trends for 2026 point to something less dramatic than either extreme: a market that is slowly rebalancing after several years of unusual swings.
This guide looks at the trends shaping 2026, what they mean for home buyers, sellers, and investors, and how professionals who specialize in accurate pricing approach a market like this one. It also explains why local conditions often matter more than national forecasts.
The Big Picture: A Market Finding Its Footing
For the past several years, the housing market has been shaped by rapid price increases, sharp moves in mortgage rates, and long stretches where buyers and sellers were pulling in opposite directions. Many analysts now describe 2026 as a transition year. Forecasters expect the market to stabilize rather than swing hard in either direction.
That stability does not mean the market is cheap. One consumer real estate publication noted that, halfway through the year, the housing market was not crashing but remained expensive for many buyers. Affordability is still the central challenge, and that shapes nearly every other trend discussed below.
For C-REPS professionals, the key takeaway is that 2026 rewards accuracy. When conditions are changing gradually, a home priced precisely to current buyer behavior tends to sell more predictably than one priced on last year’s headlines.
Mortgage Rates: Expect Stability Over Dramatic Moves
Mortgage rates have a direct effect on how much buyers can afford and how many people are actively shopping. Many forecasts for 2026 project average 30-year mortgage rates in the low-to-mid 6% range for much of the year. That is a meaningful shift from the extremes of recent years, but it is not a return to the ultra-low rates many buyers remember from before the pandemic.
Commercial real estate follows a similar pattern. A 2026 outlook from Morgan Stanley Investment Management argues that moderating interest rates are supporting recovering property valuations and creating better conditions for long-term investors. Lower borrowing costs tend to help the entire sector, not just residential buyers.
What this means in practice:
- Buyers should budget using the current rate environment, not a hoped-for drop.
- Sellers should expect some buyers to be rate-sensitive, which makes competitive pricing more important.
- Refinancing decisions depend on individual loan terms, so compare offers carefully instead of relying on national averages.
A useful habit for any buyer is to run monthly payment estimates at several rate levels. If the payment still works at a rate half a point higher than today’s, a purchase is more likely to remain comfortable if rates do not fall as quickly as hoped.
Inventory: Slowly Returning Options
One of the clearest themes for 2026 is the gradual return of housing supply. Realtor.com forecasts roughly 8.9% more inventory in 2026, which would move the market closer to equilibrium between buyers and sellers. More homes on the market give buyers more choices and reduce the pressure that drove bidding wars in tighter years.
Supply does not rise evenly across the country, however. Some metro areas have seen listings climb faster than others, while some markets remain tight. Rochester, New York, for example, has been described as a strong seller’s market, while Albany, Georgia, has been cited as a leading buyer’s market. Many other areas fall somewhere in between.
What Rising Inventory Means for Buyers
More inventory can make buying less stressful. Buyers have more time to compare properties, can negotiate on repairs and closing costs in some markets, and are less likely to feel forced into waiving inspections. The tradeoff is that homes may sit longer, and overpriced listings can linger on the market.
What It Means for Sellers
Sellers can no longer assume that any well-located home will attract multiple offers. Competition is now more about condition, presentation, and price accuracy. A home that is priced correctly from the start often performs better than one that is listed high and reduced repeatedly, because stale listings signal weakness to buyers.
Home Prices: Modest Growth, Uneven Results
Most forecasters expect home prices to rise in 2026, but at a slower pace than during the strongest years of the recent cycle. One outlook discussed in widely read market commentary suggests that prices may rise somewhere between 1% and 4% over the year. That range is useful as a baseline, but it hides large local differences.
Inflation matters here too. If prices rise by 3% while inflation runs at a similar pace, the inflation-adjusted value of a home may barely change. Buyers and investors should think about real returns, not just nominal price increases.
It is also important to remember that a national average can be misleading. A city with rising inventory may see flat or falling prices, while a market with limited supply and strong job growth may continue to climb. Price trends vary by neighborhood, school district, property type, and even street.
Comparison of market conditions to watch in 2026:
| Market Condition | What It Usually Looks Like | Strategy Focus |
| Buyer’s market | Higher inventory, longer days on market, more negotiation room | Buyers: negotiate, inspect thoroughly, compare listings. Sellers: price aggressively and prepare for longer timelines |
| Balanced market | Steady sales, moderate inventory, prices near local averages | Buyers: act on well-priced homes. Sellers: price to current comparable sales |
| Seller’s market | Low inventory, quick sales, frequent multiple offers | Buyers: prepare strong offers and pre-approval. Sellers: prepare the home and set a precise price |
Most 2026 forecasts point toward a balanced market in many areas, which is why local data is so important.
Sales Activity and Buyer Demand
Transaction volume is another key indicator. Zillow forecasts that home sales will rise by nearly 5% in 2026. A modest increase in sales suggests that buyers who paused during the high-rate period are gradually returning, but it is not a sign of a frenzied rebound.
Buyer demand is also shaped by larger forces, including household formation, job markets, and migration patterns. Some regions continue to attract residents from high-cost areas, while others see slower population growth.
Institutional investors remain part of the conversation. Large companies that own significant numbers of single-family homes have drawn attention for buying properties with cash, which can make it harder for owner-occupant buyers to compete in certain neighborhoods. For individual buyers, the practical response is to be well prepared, with financing finalized and a clear understanding of the local price range.
Local Markets Matter More Than National Headlines
Perhaps the most important point for 2026 is that national trends are a starting point, not a verdict on your property. Housing conditions vary dramatically across metro areas, and even across zip codes within the same city.
Consider a few questions when evaluating your local market:
- How many homes are currently listed, and how does that compare with the same period in previous years?
- How long are homes staying on the market before going under contract?
- What percentage of homes are selling above, at, or below asking price?
- Are price reductions becoming more common in certain price ranges?
- What is happening with new construction in the area?
Answering these questions requires local comparable sales data, which is exactly where professional pricing expertise becomes valuable. A certified professional can interpret the local signals rather than relying on a headline about the national market.
Commercial Real Estate and Emerging Technology
The 2026 outlook is not limited to homes. Commercial real estate is recovering, but unevenly. A recent outlook co-published by PwC and the Urban Land Institute, which describes the environment as a mix of optimism and caution, notes that different property types face very different conditions. Office markets continue to adjust to changing work patterns, while sectors tied to logistics, housing, and data infrastructure have attracted more attention.
Technology is reshaping the sector as well. Artificial intelligence is driving significant demand for data center development, and it is influencing how buildings are managed, leased, and valued. Residential professionals are also seeing technology change their workflows, from digital listing tools to online pricing analysis and virtual tours.
For investors and property owners, the lesson is to look closely at sector-specific trends rather than assuming all commercial property moves together.
Economic Uncertainty: What Analysts Warn About
No forecast is certain, and several analysts have emphasized that uncertainty remains high. PwC’s Emerging Trends in Real Estate report has described the current environment as a kind of fog, meaning the direction is visible in parts but unclear in others. Economic conditions, policy decisions, employment levels, and global events can all shift the market faster than projections anticipate.
That uncertainty is a reason to avoid rigid assumptions. Buyers should keep a financial cushion for unexpected costs. Sellers should avoid building a plan that depends on a specific price or timeline. Investors should stress-test their numbers against higher vacancy, higher rates, or slower appreciation.
How C-REPS Professionals Approach Pricing in a Shifting Market
C-REPS, short for Certified Real Estate Pricing Specialists, is a network of licensed real estate agents and brokers who hold a professional designation focused on accurate property pricing. These professionals complete specialized training through the National Association of BPO Professionals (NABPOP) certification program, pass certification exams, meet performance requirements, maintain their membership, and follow a professional code of ethics.
In a shifting market, that combination of formal training and local knowledge matters. C-REPS professionals focus on what buyers are actually willing to pay today in a given area, rather than what a home might have sold for a year ago or what a neighbor’s listing claims. Their approach emphasizes:
- Current comparable sales: Recent transactions that closely match the property in size, condition, and location.
- Real buyer behavior: How the market is responding to listings now, including showing activity, offers, and price reductions.
- Systematic analysis: A consistent process that reduces guesswork and emotional pricing.
- Collaborative insight: Access to a broader professional network, so clients benefit from shared market knowledge rather than one agent’s perspective alone.
For sellers, accurate pricing is the single most important early decision. An overpriced home can sit, lose buyer interest, and eventually sell for less than it would have if it had been priced correctly from the start. For buyers, accurate pricing helps identify when a listing is genuinely competitive and when it is simply optimistic.
Five Questions to Ask Any Agent in 2026
Whether you are buying or selling, these questions can help you evaluate whether an agent understands the current market:
- What do the most recent comparable sales show for homes like mine or the ones I want to buy?
- How has inventory changed in this neighborhood over the past six to twelve months?
- What are the typical price reductions and days on market for this price range?
- How do you explain your pricing recommendation, and what data supports it?
- What is your process if market conditions change after we list or make an offer?
A strong answer will be specific, data-based, and willing to explain its reasoning. Vague reassurance is a warning sign.
Practical Steps for Buyers, Sellers, and Investors
For Buyers
Start by getting pre-approved so you know your budget and can move quickly when a suitable home appears. Use the current rate environment to test your monthly payment at several interest levels. Work with an agent who can show you local comparable sales, not just listings. In a market with more inventory, it is reasonable to ask for inspections, review disclosures carefully, and negotiate on terms rather than rushing into an offer.
For Sellers
Begin with a pricing analysis based on recent local sales, not on the highest number you hope to get. Prepare the home so it shows well, address obvious maintenance issues, and consider how buyers will compare your property with alternatives in the same range. If you need to adjust the price, do it early and based on data, not after weeks of silence on the market.
For Investors
Focus on the local fundamentals that drive rental demand and long-term value, including job growth, population trends, and supply of new housing. Build conservative assumptions into your model, especially for interest costs, vacancy, and expenses. If you are considering commercial property, evaluate each sector separately, since office, industrial, multifamily, and specialized assets are moving in different directions.
Frequently Asked Questions
Will home prices fall in 2026?
Most forecasts expect modest price growth rather than a major decline, though results will vary widely by location. Some markets with rising inventory may see flat or slightly lower prices, while others with limited supply may continue to rise. Local comparable sales are the most reliable guide.
Will mortgage rates drop in 2026?
Many forecasts project rates in the low-to-mid 6% range for much of the year, which suggests stability rather than a dramatic fall. Rates can change with economic conditions, so it helps to plan around the current environment and monitor offers from several lenders.
Is 2026 a buyer’s market or a seller’s market?
Most experts describe 2026 as moving toward a more balanced market overall. Individual markets can still lean one way or the other, which is why local data matters more than national labels.
What does a C-REPS professional do differently?
C-REPS professionals complete specialized pricing training, pass certification exams, meet performance requirements, and follow a professional code of ethics. Their approach focuses on what buyers are willing to pay today in a specific local market.
Should I wait until 2027 to buy a home?
Waiting only makes sense if you have a clear reason, such as an expected change in your income or a need to build savings. Trying to time the market is difficult, and a home that fits your budget and long-term plans may be a better decision than waiting for a specific rate or price.
How much will housing inventory increase in 2026?
Realtor.com has forecast roughly 8.9% more inventory in 2026, which would help move the market toward equilibrium. Actual results will depend on local construction, owner decisions, and economic conditions.
Are institutional investors making it harder for regular buyers?
In some neighborhoods, large investors buying homes with cash have drawn concern from buyers. The impact varies by location and price range. Buyers can improve their position by getting financing ready early and working with an agent who knows the local competition.
Do national real estate trends predict what will happen in my area?
Not reliably. National forecasts provide useful context, but housing conditions vary by metro area and neighborhood. The most useful information comes from recent local sales, inventory levels, and days on market.
Foreclosure Property Valuation: Special Considerations for Distressed Assets
Foreclosure property valuation is the process of estimating what a distressed home is worth when it has been taken back by a lender, sold at auction, or is being marketed as a bank-owned (REO) property. These homes often look like bargains on paper, but their true value depends on factors that standard pricing methods do not fully capture: condition unknowns, title complications, limited access, and the motivations of the seller. Getting the number right matters for buyers deciding what to offer and for lenders or sellers deciding what to list for.
This guide explains how foreclosure and REO valuation differs from conventional pricing, which adjustments matter most, and how to avoid paying too much for a property that only looks inexpensive.
What Makes a Foreclosure Different
A conventional home is typically priced by comparing it to similar homes that recently sold in good condition under ordinary circumstances. Foreclosures break that pattern in several ways. The seller is often a lender that wants to recover its loss rather than maximize its return. The property may have sat vacant for months, and vacancy tends to accelerate deterioration. The owner may have stopped paying utilities, leaving pipes, appliances, and systems at risk. And the sale may come with limited disclosure, meaning the buyer knows less than they would in a standard transaction.
These factors mean that a foreclosure’s sale price can differ meaningfully from what the same home would fetch if it were move-in ready and fully disclosed.
Foreclosure, REO, and Short Sales
Several terms describe distressed properties, and they carry different implications:
- Pre-foreclosure: The owner has fallen behind on payments, but the lender has not yet taken the property. The owner may still sell or refinance.
- Auction (foreclosure sale): The property is sold at a public auction, often through a courthouse or trustee process, sometimes with limited inspection rights.
- REO (real estate owned): The lender has taken title after an unsuccessful auction and now markets the property directly, usually through an asset manager or listing agent.
- Short sale: The owner sells for less than the mortgage balance, with the lender’s approval. The seller is not yet foreclosed, but the sale is still shaped by lender terms.
Each category involves different timelines, disclosure levels, and negotiation dynamics, which affects how a valuation should be built.
The Core Valuation Approach
Foreclosure valuation still starts with the same foundation as any residential appraisal or pricing analysis: comparable sales, adjusted for differences in size, location, and features. The difference lies in how aggressively the analyst adjusts for condition and how carefully they separate the distressed sale from the market.
Step One: Establish the Market Value of a Comparable Home in Good Condition
Begin by estimating what the property would sell for if it were repaired and in typical condition. Analysts look at recently sold homes within a reasonable distance, with similar square footage, bedroom and bathroom counts, lot size, and age. Sales in the past three to six months carry the most weight in most markets, though slower markets may require a longer window.
Be cautious about using other foreclosure sales as comparables for the “good condition” baseline. Distressed sales can pull averages down and create a false sense of how a repaired home would trade.
Step Two: Estimate Repair and Rehabilitation Costs
Once a baseline value is established, the analyst estimates what it will cost to bring the home to that condition. This is where foreclosures require the most scrutiny. Repair estimates should cover:
- Roof condition and any water intrusion
- Foundation, structural, and grading issues
- Plumbing, including water heater and supply lines
- Electrical systems and panel capacity
- HVAC equipment, which may need replacement after long vacancy
- Interior damage such as flooring, drywall, cabinets, and fixtures
- Exterior issues such as siding, windows, and landscaping
- Mold, pest damage, or hazardous materials
Repair estimates should include a contingency. Experienced investors often add 10 to 20 percent to initial estimates because hidden damage tends to appear once work begins.
Step Three: Calculate the Net Value
A simplified valuation for a distressed property follows this structure:
Estimated Repaired Value minus Repair Costs minus Holding Costs minus Transaction Costs = Maximum Justified Price
Holding costs include property taxes, insurance, utilities, and any ongoing maintenance while the property is owned. Transaction costs include closing fees, title work, and selling costs if the buyer plans to resell.
Special Considerations That Affect Foreclosure Pricing
Several issues are unique to distressed properties and can significantly shift the valuation.
Title and Lien Risk
Foreclosures can involve tax liens, mechanics’ liens, HOA liens, or other encumbrances. Some liens survive a foreclosure sale, while others are extinguished, depending on jurisdiction and the type of sale. Buyers should obtain a full title search and, where appropriate, title insurance, and should factor any unresolved claims into their price.
Occupancy and Possession
A property may still be occupied by a former owner or tenant after the sale. Removing occupants can take time and legal action, and that delay carries costs. In some cases, a buyer may need to budget for relocation assistance or eviction proceedings, depending on local law.
Disclosure Limits
Many REO properties are sold “as is,” and lenders often provide limited disclosures. Buyers should not assume that the absence of a disclosure means the absence of a problem. A professional inspection is more important than usual in these transactions, and inspection contingencies are worth negotiating when the sale terms allow it.
Utility and Systems Status
Utilities are frequently shut off during vacancy, which can hide problems and cause damage. A home that has sat without heat through a winter may have burst pipes or compromised systems. When utilities are off, buyers should ask whether the property can be safely tested before purchase.
Deferred Maintenance
Vacant homes age faster than occupied ones. Lawns die, gutters clog, moisture accumulates, and pests move in. Deferred maintenance often hides beneath surface appearance, so a home that looks acceptable from the curb may need significant work inside.
Comparing Foreclosure and Traditional Valuations
The table below illustrates how two similar homes can produce different pricing conclusions.
| Factor | Traditional Listing | REO Property |
| Estimated repaired value | $320,000 | $320,000 |
| Condition | Well maintained | Vacant, needs repairs |
| Estimated repair cost | $0 | $45,000 |
| Holding costs (6 months) | $0 | $7,500 |
| Contingency (15 percent of repairs) | $0 | $6,750 |
| Maximum justified price | $320,000 | $260,750 |
| Typical asking price | $325,000 | $265,000 |
The REO property may appear to be a strong deal at $265,000, but the buyer’s realistic maximum is closer to $260,000 after accounting for repairs and holding costs. The difference is not a flaw in the market. It reflects the real expense of bringing the home to a sellable or livable state.
Pricing Strategies for Lenders and Sellers
Lenders and asset managers who own REO properties face their own valuation questions. Pricing too high can keep a property on the market for months, adding carrying costs and deterioration. Pricing too low can leave money on the table and invite quick offers that may not reflect the property’s full potential.
Effective REO pricing typically includes:
- An accurate as-is value, based on current condition
- A repaired value, to show buyers the potential after investment
- Documentation of known issues, to reduce surprises
- A realistic timeline, since vacant properties attract fewer buyers over time
- Competitive positioning against similar REO listings and conventional comparables
Lenders should also recognize that a property’s list price influences buyer expectations. An overpriced REO can become “stale” and face repeated price cuts, which can ultimately reduce net proceeds.
Practical Examples
Example 1: A Vacant Three-Bedroom Home
A three-bedroom house in a stable neighborhood has a repaired value of $280,000. The property has been vacant for eight months, and the inspection reveals a roof that needs replacing, outdated electrical panels, and water damage in the basement. Repair estimates total $52,000, with a contingency of about $7,800. Holding costs over the expected renovation period add roughly $9,000. The buyer’s maximum justified price is approximately $211,000, well below the repaired value and well below what a move-in ready version would command.
Example 2: An Auction Purchase
A buyer bids on a property at a courthouse auction, where the only inspection available is an exterior walk-through. The buyer estimates a repaired value of $190,000 and repair costs of $40,000, but the interior is unknown. After accounting for a title review that reveals an outstanding tax lien, the buyer reduces the maximum bid to account for the lien payoff and the risk of unseen damage. Because the risks are higher and information is limited, the buyer sets a conservative ceiling rather than bidding up to the theoretical maximum.
Actionable Steps for Buyers
- Run a title search before making any offer, and budget for any liens you discover.
- Build a repair budget from a professional inspection, not from a drive-by estimate.
- Add a contingency of 10 to 20 percent to initial repair estimates.
- Confirm whether the property is occupied and what it will take to gain possession.
- Find out whether utilities can be safely turned on for inspection.
- Compare the price against recent sales of repaired homes, not just other distressed sales.
- Set a maximum price before you bid, and stick to it.
Actionable Steps for Sellers and Lenders
- Order a current as-is valuation and a repaired value estimate.
- Disclose known issues clearly, which can reduce renegotiation after inspection.
- Price competitively against both REO and conventional listings in the area.
- Address basic safety and access issues, such as securing the property and restoring utilities if feasible.
- Revisit pricing at regular intervals, especially if the property remains unsold.
Common Mistakes in Foreclosure Valuation
- Treating the list price as the market value. Asking prices for REO properties are starting points, and final sales may differ.
- Using distressed sales as the only comparables. This can understate a repaired home’s value.
- Underestimating repairs. Hidden damage is common in vacant homes.
- Ignoring holding costs. Taxes, insurance, and utilities add up quickly over a long renovation.
- Skipping the title search. Unresolved liens can transfer costs to the new owner.
- Bidding emotionally at auction. Competitive pressure can push prices beyond what the property justifies.
Working With a Professional Pricing Specialist
Distressed properties benefit from careful, experienced analysis. Certified pricing professionals, including those who hold the C-REPS designation through the National Association of BPO Professionals (NABPOP), are trained to evaluate market evidence and adjust for the conditions that make foreclosures different. C-REPS professionals are licensed agents and brokers rather than appraisers, so they bring a market-facing perspective on what buyers are currently willing to pay in a given area.
When choosing a pricing professional for a distressed property, ask how they separated distressed sales from the market baseline, how they estimated repairs, and what assumptions they made about holding costs and timing. Clear answers signal a thorough process.
Frequently Asked Questions
What is foreclosure property valuation?
Foreclosure property valuation is the process of estimating the value of a home that has been foreclosed, is in pre-foreclosure, or is owned by a lender. It adjusts standard pricing methods for condition, repair costs, title risk, and the circumstances of the sale.
How is an REO property priced?
REO properties are typically priced using a repaired value estimate, minus the cost of repairs, holding costs, and a reasonable margin. Lenders often also consider an as-is value and recent comparable sales of similar homes in good condition.
Are foreclosures always a good deal?
No. Foreclosures can offer lower prices, but repairs, delays, liens, and limited disclosure can make them more expensive than they appear. The discount should be measured against the full cost of ownership, not just the purchase price.
What is the difference between REO and a foreclosure auction?
An REO property is one the lender has already taken back, usually after an auction fails to find a buyer. A foreclosure auction is a public sale where the property is sold before the lender takes title, and buyers often have limited inspection access.
Can I inspect a foreclosure before buying?
It depends on the sale type. Bank-owned REO properties often allow inspections, though access may be limited. Auction purchases frequently offer little or no interior access, which makes thorough due diligence more difficult.
What repairs should I budget for in a distressed home?
Common budget items include roof, foundation, plumbing, electrical, HVAC, interior finishes, and exterior maintenance. Vacant homes often need additional work due to moisture, pests, and deferred maintenance.
How do liens affect a foreclosure purchase?
Liens can remain attached to a property after a sale, depending on jurisdiction and the type of foreclosure. A title search helps identify them so the buyer can factor the cost into their offer or require payoff before closing.
Why would a lender price an REO property below market?
Lenders aim to recover losses and reduce carrying costs. Vacant properties deteriorate and attract fewer buyers over time, so pricing competitively can speed up a sale and limit additional expenses.