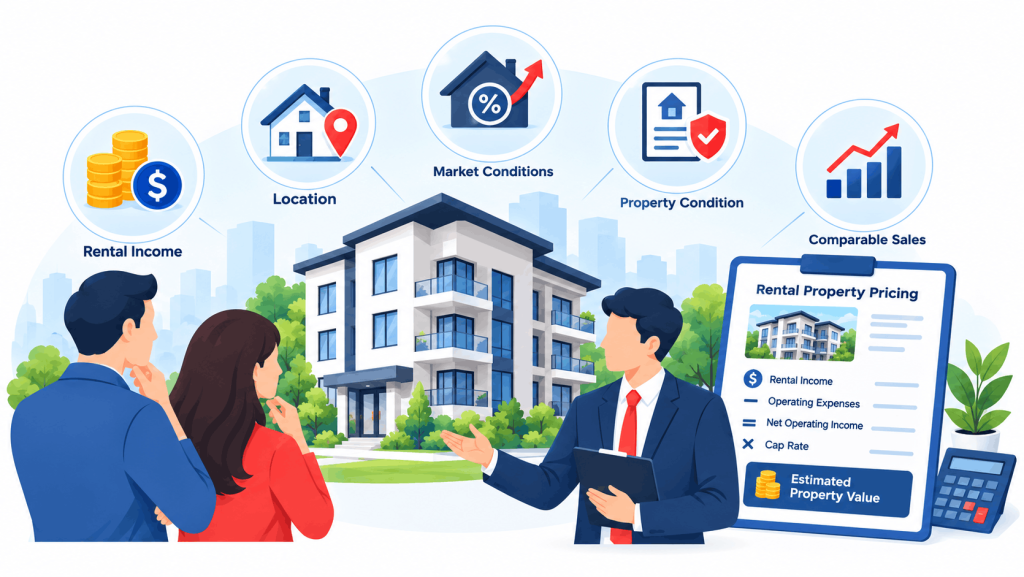
Rental property valuation pricing is the process of determining what an income-producing property is worth based on the money it earns, the risks involved in earning it, and the prices buyers are paying for similar assets in the same market. Unlike a primary residence, which buyers often value for comfort and neighborhood appeal, a rental is primarily a financial instrument. Its price should reflect the cash flow it generates, the stability of its tenants, and the expenses required to keep it operating.
This guide explains how investors, owners, and pricing professionals approach income property valuation, which methods carry the most weight, and where common mistakes lead to overpaying or underpricing. Whether you are considering a purchase, preparing to sell, or setting a rent that supports a fair asset value, the principles below will help you think more clearly about the numbers.
Why Rental Properties Are Valued Differently
Most homes are valued largely by comparing them to similar homes that recently sold. That approach, known as the sales comparison method, still matters for rentals. However, income properties add a second lens: what the property earns. A duplex in a strong rental market might sell for a price that looks high compared to a similar house in the same neighborhood, simply because the duplex produces more rent.
The Three Main Valuation Approaches
Professionals typically use three approaches, sometimes in combination:
- Sales comparison approach: Compares the property to recently sold properties with similar size, condition, location, and features.
- Income approach: Estimates value based on the income the property produces, most commonly through capitalization rates.
- Cost approach: Estimates what it would cost to rebuild the structure today, minus depreciation, plus the land value. This is most useful for newer construction or unusual properties.
For most residential rentals, the income approach and the sales comparison approach carry the most weight, with the cost approach serving as a sanity check.
Understanding Cap Rate Analysis
Cap rate analysis is central to income property valuation. The capitalization rate expresses the relationship between a property’s annual net operating income (NOI) and its value.
The Basic Formula
Cap Rate = Net Operating Income ÷ Property Value
Rearranged to solve for value:
Property Value = Net Operating Income ÷ Cap Rate
Suppose a property produces $24,000 in net operating income per year, and comparable properties in the area trade at a 6 percent cap rate. The estimated value would be $24,000 ÷ 0.06, or $400,000.
What Counts as Net Operating Income
NOI is gross rental income minus operating expenses. It does not include mortgage payments, income taxes, or capital expenditures such as a new roof.
Typical operating expenses include:
- Property taxes
- Insurance
- Property management fees
- Routine maintenance and repairs
- Utilities paid by the owner
- Vacancy and credit loss allowances
- Landscaping, snow removal, and similar services
- Reserves for future replacements (depending on the method used)
A common mistake is overstating NOI by ignoring vacancy. A property that rents at $2,000 per month does not produce $24,000 per year in practice if it sits empty for a month or two between tenants. Most experienced analysts apply a vacancy factor, often between 5 and 10 percent depending on the market.
How Cap Rates Are Determined
Cap rates are not set by formula. They are derived from market evidence. Analysts examine recent sales of similar properties, divide each sale’s NOI by its price, and look at the range of results. Cap rates tend to be lower in markets with strong growth, stable tenants, and low risk, and higher in markets with weaker demand, older housing stock, or greater volatility.
A cap rate reflects the return a buyer expects. A lower cap rate usually signals higher confidence, higher prices, and lower immediate yield. A higher cap rate suggests more risk or a higher required return, which generally means a lower price for the same income.
Gross Rent Multiplier: A Quick Screening Tool
The gross rent multiplier (GRM) is a simpler metric used for initial screening. It divides the property price by its gross annual rent.
GRM = Property Price ÷ Gross Annual Rent
If a property sells for $300,000 and generates $30,000 in gross annual rent, its GRM is 10. GRM is useful for comparing properties quickly, but it ignores operating expenses, so it should not be the final word on value. Two properties with identical GRMs can have very different expense profiles and returns.
Cap Rate Analysis: A Comparison Example
Consider two duplexes in the same city, both listed at $500,000.
| Factor | Property A | Property B |
| Annual gross rent | $42,000 | $42,000 |
| Operating expenses | $12,000 | $18,000 |
| Net operating income | $30,000 | $24,000 |
| Implied cap rate at asking price | 6.0% | 4.8% |
| Condition | Updated | Needs repairs |
| Tenant history | Long-term | High turnover |
Property A produces more income and carries a stronger implied return at the same price. Property B’s lower return may reflect higher expenses, deferred maintenance, or tenant turnover. A buyer comparing these two should ask why the expenses differ and whether the gap can be closed. If Property B’s repairs and turnover costs are temporary, its value could improve. If they are structural, the asking price may be too high.
Comparable Rents and Market Rent Analysis
Rental income is the foundation of the income approach, so accurate rent estimation matters enormously. Analysts look at:
- Current leases at the subject property
- Rents for similar units in the same building or neighborhood
- Listed rents and recently leased rents for comparable properties
- Local rent trends over the past 6 to 12 months
- Concessions, such as free months or reduced deposits, which can distort effective rent
Market rent is not always the rent a property is currently achieving. An owner who has held a tenant for many years at a below-market rate may have a property whose value is understated by the income approach, while a property with an above-market rent that is about to expire may be overstated. Good valuation accounts for both the current lease terms and the likely rent once the lease ends.
Operating Expenses: Where Valuations Often Go Wrong
Expense assumptions can make or break a rental valuation. Several errors appear frequently:
- Using seller-provided expenses without verification. Sellers sometimes omit costs such as management fees or reserves to make NOI look better.
- Ignoring capital reserves. Roofs, water heaters, HVAC systems, and appliances all wear out. Experienced investors set aside money each year for these replacements.
- Underestimating property taxes after a sale. In some jurisdictions, a sale triggers reassessment, which can raise the tax bill substantially.
- Assuming zero vacancy. As noted earlier, even well-managed properties experience turnover.
- Forgetting insurance increases. Insurance costs have risen in many regions, and a buyer’s premium may differ from the seller’s.
A thorough valuation requests historical operating statements, tax records, utility bills, and maintenance logs, then compares them against market norms.
How to Estimate a Rental Property’s Value Step by Step
Here is a practical sequence for working through an income property valuation:
- Gather the income data. Collect current rent rolls, lease terms, deposits, and any other income such as parking, laundry, or storage fees.
- Establish market rent. Compare the property’s rent to recent leases of similar units nearby.
- Calculate gross potential income. Multiply each unit’s market or contract rent by 12 months, then add other income.
- Apply a vacancy and credit loss allowance. Subtract an estimated percentage to arrive at effective gross income.
- Subtract operating expenses. Include taxes, insurance, management, maintenance, utilities, and reserves to find net operating income.
- Identify market cap rates. Review recent sales of comparable income properties and calculate their cap rates.
- Estimate value. Divide NOI by the appropriate cap rate.
- Cross-check with sales comparables. Confirm that the income-based value is consistent with the price per unit, price per square foot, or other metrics for similar properties.
- Adjust for condition and risk. Account for deferred maintenance, lease risk, neighborhood trajectory, and financing terms.
If the income approach and the sales comparison approach produce very different numbers, investigate before choosing one. The gap often reveals an assumption that needs correction.
Pricing a Rental for Sale Versus Pricing for Purchase
Owners preparing to sell an income property often face a different question than buyers. The seller wants a price that reflects the property’s income while also appealing to investors who will run their own numbers.
Sellers benefit from presenting clean, documented financials. A property with verified rent rolls, recent tax bills, and transparent expense history tends to attract more confident offers. Buyers who see unexplained figures often discount the price to account for uncertainty, which can make a property sit longer on the market.
Buyers, meanwhile, should resist anchoring on the asking price. A listing price is a starting point for negotiation, not a verified value. Running an independent income analysis and comparing the result against recent sales helps buyers avoid paying for income that may not materialize.
Common Mistakes in Rental Property Valuation
Even experienced investors fall into predictable traps:
- Relying on a single method. An income-only view can miss neighborhood factors, while a comparable-sales view can miss the income potential of an underused property.
- Using a cap rate from a different market. A 5 percent cap rate in a major metro area is not comparable to a 5 percent rate in a secondary city with different risk profiles.
- Treating appreciation as guaranteed. Projected price growth should not be the primary justification for paying above what the income supports.
- Confusing gross and net figures. Quoting gross rent as though it were profit inflates perceived value.
- Ignoring financing. Leverage affects returns, but the property’s value should be assessed independently of the buyer’s loan terms.
- Skipping professional review for complex properties. Multi-unit buildings, mixed-use properties, and properties with unusual leases benefit from experienced analysis.
Practical Examples of Rental Valuation
Example 1: A Four-Unit Building
An investor evaluates a four-unit building where each unit rents for $1,400 per month. Gross potential income is $67,200 per year. Applying a 7 percent vacancy allowance reduces effective gross income to about $62,500. Operating expenses total $22,000, leaving NOI of about $40,500. In a market where similar buildings trade at a 6.5 percent cap rate, the estimated value is roughly $623,000.
If the seller is asking $700,000, the investor can see that the price implies a cap rate near 5.8 percent. That gap does not automatically make the deal bad, but it signals that the buyer would need to believe in rent growth or expense reductions to justify the premium.
Example 2: A Single-Family Rental
A single-family rental producing $1,800 per month in rent generates $21,600 annually. After taxes, insurance, management, and reserves totaling $7,000, NOI is $14,600. With a market cap rate of 5 percent, the estimated value is $292,000. Here, the sales comparison approach might be more informative, since single-family rentals often trade at prices driven heavily by neighborhood comparables.
Actionable Steps for Owners and Investors
- Maintain organized records of rents, expenses, and maintenance for at least three years.
- Review your rents against the market every 12 months, and understand the legal limits on increases where you operate.
- Budget for capital reserves annually, even if no major repairs are imminent.
- Obtain a professional valuation before listing or making a major purchase.
- Request full operating statements and verify them independently before relying on seller figures.
- Compare cap rates across at least five to ten recent comparable sales, not just one or two.
Working With a Professional Valuation
A credible valuation combines local market knowledge, documented data, and a consistent method. Certified pricing professionals, such as those who hold the C-REPS designation through the National Association of BPO Professionals (NABPOP), are trained to apply these methods to real market evidence. Because C-REPS professionals are licensed agents or brokers rather than appraisers, they bring a sales and market perspective to pricing, which can be especially useful when you need to understand what buyers in your area are currently paying.
When evaluating any valuation provider, ask how they arrived at their figures, which comparables they used, how they treated expenses and vacancy, and whether they can explain the assumptions behind a cap rate. A transparent answer is a good sign.
Frequently Asked Questions
What is rental property valuation pricing?
Rental property valuation pricing is the process of estimating an income-producing property’s worth using its rental income, operating expenses, market cap rates, and comparable sales. It differs from residential home pricing because income performance is a central factor.
What is a good cap rate for a rental property?
There is no single good cap rate. Acceptable rates vary by market, property type, and risk. Lower cap rates are common in strong, stable markets, while higher rates are typical in areas with more uncertainty. Compare the target property to recent local sales.
How do you calculate the value of a rental property?
Divide the property’s annual net operating income by the market cap rate. For example, $30,000 in NOI at a 6 percent cap rate implies a value of $500,000. Cross-check the result against comparable sales.
What expenses should be included in NOI?
Include property taxes, insurance, management fees, routine maintenance, owner-paid utilities, vacancy allowances, and reserves for future replacements. Exclude mortgage payments, income taxes, and major capital improvements.
Is the gross rent multiplier reliable?
The gross rent multiplier is useful for quick screening but should not be the sole basis for a decision. It ignores operating expenses, which can vary widely between properties.
Why does my rental property’s value depend on the income?
Investors buy income properties for the cash flow and returns they generate. A property’s value is closely tied to how much income it produces relative to the return investors require in its market.
How often should I revalue a rental property?
Many owners revisit valuations annually or when market conditions change, when considering refinancing, or before a sale. A fresh valuation helps you spot changes in rents, expenses, or local cap rates.
Can a professional valuation help before I sell?
Yes. A professional valuation helps you set a realistic listing price, identify issues that may concern buyers, and understand how your property compares to recent sales and current investor expectations.