Investment Property Valuation ROI: How C-REPS Professionals Assess Return Potential
Buying an investment property is one of the largest financial decisions many people make. The purchase price is only the starting point. Whether a property will actually earn a good return depends on how accurately it was valued, what it can realistically produce in rent, what it will cost to hold, and where the local market is heading. This is where investment property valuation ROI analysis comes in, and it is the discipline that separates thoughtful investors from speculators.
This guide explains how investment property valuation works, how return on investment is calculated and interpreted, and how certified professionals approach the process. It is written for property investors, first-time landlords, and anyone who wants to understand what a sound valuation looks like before committing capital.
Why Investment Property Valuation Differs From Home Valuation
A home buyer usually values a property based on whether it suits their life: the schools, the commute, the kitchen. An investor values it based on cash flow and appreciation. The same three-bedroom house can be a poor investment at one price and an excellent one at another, even though its physical features never change.
This difference matters because an investment valuation must answer a different question. Instead of asking “What is this home worth to me?” it asks “What will this asset earn, and what will it be worth later?” That shift changes which data matters most.
The Core Inputs
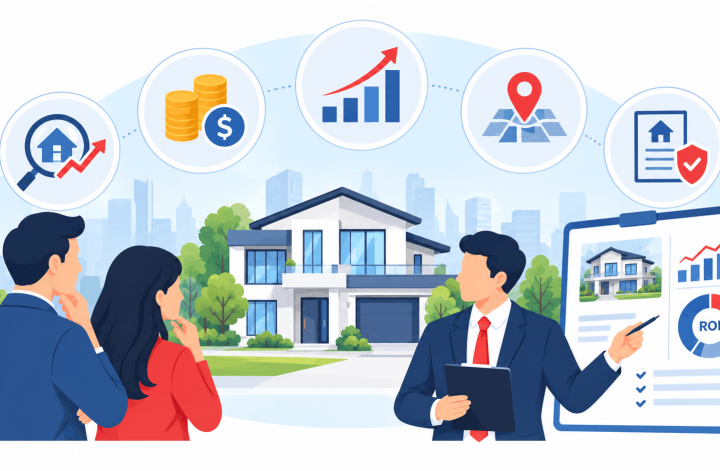
Every sound investment property valuation draws on several categories of information:
- Comparable sales: Recent sales of similar properties nearby, adjusted for differences in size, condition, and features.
- Rental market data: Current rents for comparable units, vacancy rates, and typical lease terms.
- Operating costs: Property taxes, insurance, maintenance, management fees, and utilities the owner pays.
- Financing terms: Interest rate, loan amount, and loan structure, which affect the true cost of ownership.
- Market direction: Employment trends, population movement, new construction, and infrastructure plans.
Understanding ROI: The Metrics That Matter
Return on investment is not a single number. Investors use several measures, and each reveals something different about a property.
Gross Rent Multiplier
The gross rent multiplier (GRM) is a quick screening tool. Divide the purchase price by the annual gross rental income. A lower number generally suggests the property is priced more favorably relative to the rent it produces. GRM is useful for comparing many properties quickly, but it ignores expenses, so it should never be the final word.
Capitalization Rate
The capitalization rate, or cap rate, divides net operating income (rental income minus operating expenses, before financing costs) by the property’s price. A property with $24,000 in annual net operating income priced at $400,000 has a cap rate of 6 percent. Cap rate lets investors compare properties on a like-for-like basis, though what counts as an acceptable cap rate varies by market and property type.
Cash-on-Cash Return
Cash-on-cash return measures the annual pre-tax cash flow against the actual cash invested, including the down payment and closing costs. It reflects the financing structure, which makes it especially relevant for leveraged purchases. A property can have a modest cap rate and still deliver a strong cash-on-cash return if financing is favorable, and the reverse is also true.
Total Return
Total return combines cash flow with appreciation and the effect of loan paydown over the holding period. It gives the fullest picture but depends heavily on assumptions about future prices and rents, so it should be stress-tested rather than taken at face value.
How Certified Professionals Approach the Analysis
Pricing professionals who hold recognized certifications tend to follow a disciplined process. The specifics vary, but the general approach looks like this.
Step 1: Establish a Defensible Market Value
Before any return can be calculated, the investor needs to know what the property is realistically worth. Certified professionals begin with recent comparable sales and adjust for real differences: square footage, lot position, condition, age, and renovation quality. The aim is a value grounded in what buyers are actually paying in that specific neighborhood now, not what sellers hope to get or what an automated estimate suggests.
This is where local market knowledge becomes essential. Two streets apart, a property can sell for noticeably different amounts because of school zones, noise, flood exposure, or simply which blocks have been well maintained. Professionals who work a local market regularly tend to recognize these patterns faster than data models alone.
Step 2: Estimate Achievable Rent
Rent is the engine of investment return, so it deserves careful study. Professionals look at what comparable units are renting for, not what the owner would like to charge. They also consider the condition of the unit, the amenities it offers, and seasonal demand patterns. A realistic rent estimate is often lower than optimistic projections, and building the analysis around a conservative figure protects the investor.
Step 3: Build a Complete Expense Picture
Many weak investments fail on expenses rather than on price. A thorough analysis includes property taxes, insurance, routine maintenance, capital reserves for major replacements such as roofs and HVAC systems, property management fees if applicable, and vacancy allowances. Experienced investors typically budget for vacancy and repairs even in strong markets, because assuming a unit will always be occupied and never need work is one of the most common valuation mistakes.
Step 4: Calculate and Compare Return Metrics
With market value, rent, and expenses established, the professional calculates the relevant ROI measures. The most useful comparison is between the subject property and other opportunities in the same market, since return expectations shift with interest rates and local conditions.
Step 5: Stress-Test the Assumptions
A valuation is only as reliable as its assumptions. Good analysis asks what happens if rents fall by 10 percent, if vacancy doubles, if interest rates rise, or if a major repair arrives in year two. A property that still performs acceptably under several adverse scenarios carries far less risk than one that depends on everything going right.
A Practical Example
Consider a two-bedroom condominium listed at $300,000. Comparable sales in the building and nearby suggest its fair market value is closer to $285,000, since the unit needs updated flooring and the kitchen is dated. Comparable rentals support a monthly rent of $1,900, or $22,800 per year.
Annual operating costs include $3,600 in association fees, $1,800 in property taxes, $600 in insurance, and $1,500 for maintenance and reserves. Allowing 5 percent for vacancy, effective gross income is about $21,660. Subtracting operating costs of $7,500 leaves net operating income of roughly $14,160. Against the $285,000 valuation, that produces a cap rate of about 5 percent.
If the investor puts 25 percent down, plus closing costs, and the mortgage payments total around $12,000 per year in interest and principal, annual cash flow is modest. The cash-on-cash return will depend on the exact cash invested, but the example illustrates an important lesson: a property can look attractive on gross rent alone and still deliver thin returns once costs and financing are included.
The professional’s job in this scenario is not to declare the property good or bad. It is to show the investor the realistic range of outcomes and the assumptions that drive them, so the decision is informed.
Common Valuation Mistakes to Avoid
Several errors appear repeatedly in investment analysis:
- Using asking price instead of market value as the basis for return calculations.
- Ignoring capital expenditures, since roofs, water heaters, and HVAC systems eventually need replacement.
- Assuming full occupancy with no allowance for turnover or vacancy.
- Overestimating rent based on the best-case listing rather than typical comparable units.
- Relying on a single metric, such as gross rent multiplier alone.
- Forgetting taxes on the return, including depreciation recapture and capital gains where applicable.
Working With a Certified Professional
Investors who want a second opinion on valuation can benefit from working with a certified pricing professional. Certification programs typically require training, examinations, and continuing education, which helps ensure that the person has a structured method for analysis rather than relying on instinct alone.
When evaluating any professional, ask how they arrived at their value, which comparable sales they used, and how they treated expenses and vacancy. A trustworthy advisor will explain their reasoning clearly and will be comfortable showing where the assumptions could be wrong.
C-REPS (Certified Real Estate Pricing Specialists) is a network of licensed agents and brokers who have completed specialized training through the National Association of BPO Professionals (NABPOP) certification program. Its members are active real estate professionals rather than appraisers, and they combine systematic training with deep local market knowledge. Because members work as part of a collaborative network, investors can benefit from a broader market perspective than a single agent might offer alone. Investors can review the program’s requirements and find a member through the official C-REPS website.
Frequently Asked Questions
What is investment property valuation ROI?
Investment property valuation ROI refers to the process of estimating a property’s market value and then measuring the return it is likely to produce. It combines an accurate price estimate with projections of rental income, operating costs, financing, and appreciation.
How do you calculate ROI on an investment property?
The simplest approach divides annual net profit by the total cash invested. More precise measures include cap rate (net operating income divided by property value) and cash-on-cash return (annual pre-tax cash flow divided by cash invested). Each answers a slightly different question.
What is a good cap rate for an investment property?
There is no universal answer. Acceptable cap rates vary by market, property type, interest rates, and expected growth. Investors should compare a property’s cap rate against similar properties in the same area rather than against a fixed benchmark.
Why does the purchase price matter less than the rent?
Purchase price matters, but the income a property generates determines whether it is a good investment. A property bought at a fair price that produces strong, reliable rent can outperform one bought cheaply but generating weak income.
How much should I budget for vacancy and repairs?
Many investors plan for a vacancy allowance and set aside a percentage of rent for maintenance and capital reserves. The right figures depend on the property’s age, condition, and location, so local data and professional input are the best guides.
Can I rely on an online estimate for investment decisions?
Automated estimates can be a useful starting point, but they often miss condition, local nuance, and the specific features that drive value. For an investment decision, it is wise to verify any automated figure with recent comparable sales and a professional analysis.
Do I need a certified professional to value an investment property?
You are not required to hire one, but a certified professional can add structure and local expertise, especially for first-time investors or those buying in unfamiliar markets.
Is investment property valuation the same as appraisal?
Not quite. An appraisal is typically performed by a licensed appraiser for lending purposes and follows specific standards. Pricing and investment analysis may be performed by agents or advisors to guide buying, selling, or return assessment decisions.