Common Pricing Mistakes Home Sellers Make (And How to Avoid Them)
Most home sellers approach pricing with more hope than strategy. They anchor on emotional attachments, rely on outdated internet estimates, or follow aggressive agent promises without examining underlying methodology. The result: systematic mispricing that costs thousands in lost equity or extended market time.
The mistakes sellers make tend to cluster into recognizable patterns. Some owners overestimate their home’s value based on personal investment or emotional attachment. Others anchor on their purchase price, ignoring market evolution. Still others delegate pricing entirely to agents without understanding the methodology or questioning recommendations.
What separates successful sellers from frustrated ones isn’t luck. It’s understanding common pricing pitfalls and implementing systematic approaches that prioritize data over emotion, market reality over wishful thinking, and professional expertise over casual estimates.
This guide walks through the most costly pricing mistakes home sellers make, explains the financial and strategic consequences of each error, and provides concrete strategies to avoid them. Whether you’re preparing your home for market or evaluating a pricing recommendation from an agent, understanding these mistakes helps you make decisions grounded in market reality rather than speculation.
Mistake 1: Overpricing Based on Emotional Attachment
The most common and costly pricing mistake stems directly from emotion. Home sellers frequently overvalue what they’ve invested in their property, what they paid for it, or what they believe it deserves in an imaginary market.
Why Emotional Attachment Distorts Pricing
You’ve lived in your home for years. You’ve invested money into renovations, maintained the property, created memories, and formed attachment. Naturally, you believe your home is worth more than comparable properties because you know its quality intimately.
This emotional lens creates systematic overpricing. You remember every repair you’ve made, every upgrade you’ve invested in, and every care you’ve provided. Buyers, by contrast, see a property competing against alternatives in their actual budget range. They lack your emotional investment and historical context.
The kitchen renovation you funded because you love cooking might represent $40,000 of your investment but add only $25,000 of buyer value. The landscaping you’ve maintained meticulously because it brings you joy has little relevance to buyers who primarily want low-maintenance outdoor space.
The Financial Consequence
Overpricing by just 5% on a $500,000 home means listing at $525,000 when market value is $500,000. What happens next is predictable:
First week: Minimal showings. Buyers searching the market immediately recognize that comparable homes sell for 495,000-510,000, making your $525,000 asking price unrealistic.
Weeks 2-4: Extended showings without offers. Your home competes against similar properties correctly priced. Buyer interest shifts to properly priced alternatives.
Weeks 5-8: Price reduction to $510,000, acknowledging that overpricing failed. But buyers have already noticed the extended market time and assume problems exist.
Week 12: Final sale at $485,000 after market exposure reveals buyer resistance.
Financial impact: You listed at $525,000, finally sold for $485,000 (nearly 8% below what accurate pricing would have achieved), wasted three months of carrying costs (roughly 3,000-5,000 in mortgage interest, taxes, utilities, and opportunity cost), and faced buyer psychology that you’re desperate.
The emotional attachment that led to overpricing ultimately cost you $20,000+ in lost equity plus additional carrying costs and psychological disadvantage during negotiation.
How to Avoid Emotional Overpricing
Separate your emotional value from market value. What you paid for your home, what you’ve invested in it, and what it means to you personally is irrelevant to what buyers will pay. This separation is uncomfortable but necessary.
Get a professional valuation from a certified specialist who has no emotional investment in your home and no incentive to overestimate value. Require that specialists show their work: comparable properties used, adjustments made, market conditions considered.
If your emotional valuation significantly exceeds professional recommendations, acknowledge the gap. It signals that your emotional attachment is distorting judgment. Professional valuations exist precisely to counteract this bias.
Trust the market data more than your intuition. Comparable homes that sold in your neighborhood for $500,000 represent actual buyer behavior and willingness to pay. Your belief that your home deserves $525,000 represents hope, not market reality.
Mistake 2: Anchoring on Purchase Price
A surprisingly common pricing mistake involves anchoring on what you paid for your home years ago. “I bought it for $450,000, so it must be worth at least that now,” sellers think, ignoring that markets change dramatically over time.
How Purchase Price Becomes a Pricing Anchor
Your purchase price is irrelevant to current market value. Markets appreciate or depreciate based on supply and demand, interest rates, neighborhood conditions, and economic factors completely unrelated to what any individual paid.
Yet sellers consistently use purchase price as a pricing floor, assuming appreciation over time. This reasoning fails when markets depreciate or appreciate less than expected. A $450,000 purchase five years ago might support a $520,000 current value (appreciating 3.1% annually, compounded). Alternatively, that same home might support only $425,000 in a market that appreciated only 0.5% annually.
Using purchase price as a pricing anchor causes systematic overpricing in depreciating markets and missed opportunity in strongly appreciating markets.
The Market Reality
Markets evolve. Interest rates fluctuate. Employment patterns shift. Neighborhood conditions change. New developments or highway noise might reduce buyer demand. Conversely, new transit access or corporate relocation might increase demand dramatically.
A home’s purchase price is historical information with zero relevance to current value. Skilled buyers and their agents immediately recognize overpricing anchored to old purchase prices and adjust offers accordingly.
How to Avoid Anchor Bias
Explicitly reject your purchase price as a pricing reference point. Acknowledge what you paid, but recognize that it’s historical information unrelated to current value.
Focus exclusively on comparable sales of similar properties in similar conditions selling during similar timeframes. Recent market activity reveals actual buyer behavior and current value far more accurately than your purchase price.
If you paid $450,000 five years ago and that same home currently sells for $420,000, accepting this reality (while emotionally difficult) beats the alternative: overpricing at $450,000, experiencing extended market time, and eventually selling for $415,000 after months of carrying costs.
The market has spoken through comparable sales. Your purchase price is irrelevant.
Mistake 3: Dismissing Professional Guidance in Favor of Internet Estimates
Zillow Zestimates, Realtor.com estimates, and similar automated tools provide rough value ranges but consistently fail to match professional valuations. Yet many sellers trust these algorithms more than experienced specialists.
Why Automated Estimates Miss the Mark
Online valuation tools use algorithms trained on historical data without incorporating current market conditions, neighborhood-specific dynamics, or property-specific details. They might include recent renovations in the algorithm but can’t evaluate renovation quality or buyer preferences in your specific market.
These tools also lack real-time market intelligence. They don’t know that inventory surged last month, changing pricing power. They don’t account for a new employer opening in your area, creating a demand surge. They don’t recognize that your neighborhood is appreciating faster than surrounding areas.
For a rough range, automated estimates provide value. For actual pricing decisions affecting your most valuable asset, they’re dangerously inaccurate.
The Cost of Relying on Automated Estimates
A Zestimate showing $500,000 might represent actual market value of $475,000 or $525,000, depending on market conditions and property specifics. Listing based on the estimate alone means you’re essentially guessing.
The professional specialists you’re dismissing have seen hundreds of comparable sales, know current buyer demand patterns, understand inventory levels, and recognize emerging market trends. Their valuations reflect this expertise.
How to Avoid Misplacing Trust in Automation
Use online estimates as one data point, not the primary pricing source. If a Zestimate conflicts with professional valuation, investigate why. Ask your specialist to explain the difference and show their supporting analysis.
Demand professional analysis from someone with market expertise and no incentive to inflate your home’s value to make a sale seem easier. C-REPS certified specialists prioritize accuracy over optimistic promises.
Compare multiple professional valuations if significant amounts of money are at stake. Specialists using systematic methodology should produce similar values. Large discrepancies warrant investigation.
Mistake 4: Overlooking Current Market Conditions
The same home priced appropriately in a balanced market might be overpriced in a buyers’ market or underpriced in a sellers’ market. Yet many sellers fail to adjust for current inventory levels, buyer demand, and market velocity.
Market Conditions That Change Pricing
Inventory levels dramatically influence pricing power. In balanced markets (4-6 months of inventory at current sales pace), pricing remains relatively stable. In buyers’ markets (8+ months of inventory), prices soften as buyer competition diminishes. In sellers’ markets (under 2 months’ inventory), prices strengthen as buyer competition intensifies.
Days on market for comparable properties reveal market velocity. If comparable homes sold in 10 days last year but require 25 days currently, market conditions have shifted downward. Pricing needs adjustment.
Seasonal patterns matter. Spring markets typically move faster than winter markets. Year-end holidays reduce buyer activity. Professional specialists adjust pricing recommendations for the season.
Interest rates significantly influence affordability and buyer demand. When rates spike, buyer purchasing power declines. Prices typically adjust downward to maintain affordability at lower income levels.
Sellers’ Common Mistake
Sellers frequently price based on market conditions from 6-12 months ago without recognizing how conditions have shifted. “A comparable sold for $500,000 last May,” they think, ignoring that May’s market differed substantially from December’s market.
This creates systematic overpricing when markets shift downward and systematic underpricing when markets shift upward.
How to Avoid Market Condition Missteps
Get current market data, not historical data. Ask your specialist about today’s inventory levels, average days on market for current listings, and recent pricing trends.
Request analysis of both recent comparable sales (within 60 days) and current comparable listings. Recent sales show what buyers actually paid. Current listings show current asking prices (which typically exceed selling prices by 2-5%).
Understand whether current market conditions favor buyers or sellers. This fundamental reality should influence pricing positioning.
Recognize that market conditions change continuously. A home priced correctly in January might need adjustment by March as conditions shift. Quality specialists monitor conditions and recommend adjustments when warranted.
Mistake 5: Overinvesting in Renovations Without Market Validation
Home sellers frequently invest in major renovations expecting dollar-for-dollar return on investment. Yet many renovations fail to deliver proportional value increases. Some actually reduce buyer appeal by creating homes that are highly personalized or over-improved for their market segment.
Renovation ROI Reality
Kitchen renovations typically return 60-80% of investment. Bathroom updates often return 50-75%. Roof replacement and HVAC updates (addressing deferred maintenance) typically return 60-100%. Luxury upgrades, high-end finishes, and personalized installations often recover only 20-40% of costs.
A $60,000 luxury kitchen renovation might add only 35,000-45,000 to your home’s value. That’s money spent from your equity perspective.
Worse, over-improved homes sometimes alienate buyers. A luxury kitchen in a neighborhood of modest homes might actually reduce buyer appeal. Highly personalized spaces (custom theaters, elaborate landscaping, unusual color schemes) appeal to fewer buyers than neutral, flexible spaces.
The Personalization Problem
Renovations based on your preferences rather than market preferences frequently fail to return investment. You invested in the spaces you personally valued. Buyers value different things.
Sellers also frequently complete renovations immediately before selling, expecting full value recovery. But sophisticated buyers recognize new renovations as signs that the previous owner finally addressed deferred maintenance or attempted to disguise problems.
How to Avoid Poor Renovation Decisions
Before investing in major renovations, consult with pricing specialists about which improvements your market values most. Don’t assume all renovations are equally valuable.
Research typical ROI for renovations in your price segment and neighborhood. Some neighborhoods support luxury upgrades; others don’t.
Consider that market conditions affect renovation value. In slowly moving markets, buyer preferences matter less. In competitive markets, neutral finishes appeal to more buyers than highly personalized spaces.
If you’ve already invested in renovations that don’t align with market preferences, accept that you won’t recover full investment. Adjust pricing accordingly rather than expecting buyers to reward your personalization.
The best renovation strategy: address deferred maintenance, update key areas (kitchen, bathrooms) to current but not luxury standards, and maintain neutral finishes that appeal broadly.
Mistake 6: Failing to Adjust for Property Condition Differences
Comparable properties used for pricing rarely match your home perfectly. Professionals adjust prices for differences. Sellers frequently fail to make these adjustments, leading to mispricing.
What Adjustments Matter
Recent major system replacements (roof, HVAC, electrical, plumbing) might warrant 1-3% price adjustments. Significant deferred maintenance (aging HVAC, roof damage, foundation concerns) requires downward adjustments of similar magnitude.
Renovation quality matters. Professionally completed renovations support higher adjustments than DIY work. Custom built-ins and professional design warrant higher value than basic updates.
Lot size differences affect value. Larger lots in suburban areas support higher prices. In urban areas, land value matters less than location walkability.
Common Mistake
Sellers compare their home to nicest properties in their neighborhood, ignoring condition differences. Your home with original systems, average condition, and outdated finishes should price below similar homes with recent renovations and excellent condition.
Yet many sellers price as if their home deserves “best comparable” pricing without acknowledging condition gaps.
How to Adjust Appropriately
Ask specialists to explain adjustments they make between comparable properties and your home. Understand whether your home is better or worse positioned than comparables and by how much.
Be honest about your home’s condition. If your HVAC system is 18 years old and comparable properties have 5-year-old systems, your home warrants downward adjustment.
Focus pricing on properties truly comparable in condition, not on aspirational comparables that look better than your actual property.
Mistake 7: Ignoring Buyer Perception and Market Psychology
Pricing influences buyer psychology in ways sellers frequently overlook. List price anchors buyer perception. Extended market time signals problems. Psychological price points matter more than their numerical difference suggests.
The List Price Anchor Effect
Your initial list price influences buyer perception throughout the selling process. List at $500,000, then reduce to $475,000, and buyers anchor to the original $500,000. They perceive the reduction as a concession rather than an accurate correction.
List at $475,000 from the start, and buyers accept this as market price without perception of overpricing or desperation.
This psychological effect means first-impression pricing matters enormously. Overpricing initially creates lasting perception problems even after price corrections.
Days on Market Signal
Markets recognize extended market time as a signal that something is wrong. Either the price is too high, the property has issues, or both. Once a home is perceived as problematic, recovering from that perception proves difficult.
A home selling after 10 days seems appropriately priced. A home selling after 60 days seems problematic, even if the final price is strong. Buyer psychology matters.
Psychological Price Points
Homes listed at $499,000 receive different buyer attention than homes listed at $505,000, despite a $6,000 price difference. Pricing just below round numbers (hundred-thousand markers, million markers) triggers different buyer search behavior and perception.
However, psychological pricing only works when the underlying price is accurate. It can’t overcome fundamental mispricing.
How to Avoid Perception Mistakes
Price accurately at market entry to capture maximum attention during the critical first 7-14 days. This positions your home for a quick sale at a strong price rather than extended marketing followed by price reduction.
Recognize that initial list price creates lasting perception. Don’t overestimate to create negotiation room. Price correctly from the start.
Use psychological price points (just below round numbers) but only when the price is actually accurate. Psychological pricing isn’t a license to inflate prices arbitrarily.
Mistake 8: Underpricing in Hopes of Quick Sale
Some sellers deliberately underprice their homes, hoping to generate buyer competition and a quick sale. “Price it low, and we’ll get multiple offers,” they think. This strategy frequently backfires.
The Underpricing Strategy Failure
Underpricing sometimes generates quick sales because multiple buyers recognize the value and compete. But this competition for an underpriced property means multiple buyers want to negotiate down further.
Even with multiple offers, an underpriced home sells for less than accurate pricing would have achieved. You trade time for equity.
Additionally, underpricing sometimes fails to generate competition. If your home is underpriced in a slow market, it still sells slowly despite low price. The underpricing provided no benefit.
When Underpricing Makes Sense
Strategic underpricing makes sense in specific situations: you need a rapid sale for relocation or emergency reasons, your home has specific appeal issues that require aggressive pricing, or your market is moving so slowly that only aggressive positioning generates offers.
In these situations, underpricing is a tactical response to market reality, not a strategic choice.
How to Avoid Careless Underpricing
Don’t underprice simply because you’re impatient. Patient pricing captures full market value. Impatient pricing leaves equity on the table.
Consider your specific situation. Do you genuinely need a rapid sale? Or are you creating artificial urgency? Only genuine time constraints justify significant underpricing.
If you choose strategic underpricing, do so intentionally after consulting with specialists who understand your market. Don’t underprice by accident through casual or emotional decisions.
Mistake 9: Trusting Generic Agent Promises Over Data
Many sellers select agents based on aggressive promises about home value rather than careful analysis and market data. “I can sell your home for $550,000,” an optimistic agent claims. Sellers choose this agent, then experience reality when the home won’t sell at $550,000.
This happens repeatedly because sellers want to believe optimistic promises and agents know this. Aggressive value overestimates win listings (and commissions) even though they rarely result in optimal outcomes for sellers.
The Promise Versus Reality Gap
Agents sometimes overestimate home values to win listing agreements, planning to reduce prices after market exposure reveals reality. From the agent’s perspective, they earn commission either way. From your perspective, overpricing costs thousands in lost equity and months of extended market time.
Red Flags for Overestimating Agents
Agents who provide valuations significantly above multiple professional estimates are typically overestimating to secure your listing.
Agents who resist providing detailed comparable analysis or market condition explanation often lack confidence in their valuations.
Agents who promise specific sale prices without detailed methodology or market analysis are making promises they can’t control. Market conditions determine outcomes, not agent promises.
How to Evaluate Agent Recommendations
Request detailed analysis from any agent recommending pricing. They should explain comparable properties used, adjustments made for differences, and current market conditions considered.
Compare multiple agent recommendations. Consistency between recommendations builds confidence. Large discrepancies warrant investigation.
Ask agents to commit recommendations in writing with supporting analysis attached. Agents confident in their recommendations typically accept written commitments.
Trust systematic methodology more than aggressive promises. C-REPS certified specialists prioritize accurate analysis over optimistic promises designed to win listings.
Mistake 10: Failing to Monitor Market Conditions During Marketing
Markets change continuously. A home priced accurately at market entry might need adjustment if conditions shift significantly. Yet many sellers refuse to adjust pricing despite market changes.
When Market Conditions Warrant Price Adjustment
If your home enters the market with 3 months’ inventory and shifts to 6 months’ inventory, pricing needs downward adjustment to maintain competitiveness.
If new inventory surges in your neighborhood, pricing needs adjustment to remain compelling.
If buyer demand indicators shift (job losses, interest rate increases, economic concerns), pricing typically needs adjustment.
If comparable properties recently reduced prices, your pricing likely needs adjustment.
The Stubbornness Problem
Many sellers resist price adjustments, viewing them as personal failure or admission that initial pricing was wrong. But markets change. Intelligent pricing adjustment is a response to market evolution, not failure.
Homes that refuse price adjustments despite market shifts typically experience extended market time and eventual price reduction deeper than strategic early adjustment would have required.
How to Adjust Intelligently
Commit to monitoring your market continuously. If conditions shift after listing, discuss adjustments with your specialist.
Establish trigger points for price adjustment. “If comparable homes’ average selling price decreases by 2%, we’ll adjust our price accordingly.” Having predetermined triggers prevents emotional resistance when adjustment becomes necessary.
Remember that small early adjustments prevent larger late adjustments. Price reduction from $495,000 to $485,000 mid-month signals market adjustment. Price reduction from $500,000 to $475,000 after 90 days signals desperation.
Expert Insights: What Pricing Specialists Know
Professional pricing specialists recognize patterns that sellers frequently miss.
Pattern Recognition from Experience
Specialists who’ve priced hundreds of homes recognize which homes will sell quickly at asking price, which will sell with modest negotiation, and which will require significant price reduction to generate offers.
This pattern recognition comes from experience and market data analysis, not intuition. Sellers lack this pattern recognition simply because they price homes infrequently.
Buyer Behavior Intelligence
Specialists understand actual buyer behavior in your specific market. They know what price point triggers showing requests. They know which features generate disproportionate buyer response. They know whether your market attracts investors, families, or move-up buyers.
Generic pricing advice ignores these market-specific realities.
Negotiation Dynamics
Professionals understand how pricing influences negotiation. Correctly priced homes generate multiple offers with minimal negotiation. Overpriced homes experience seller desperation during negotiation. Underpriced homes generate buyer confidence and aggressive final offers.
The Cost of Mispricing
Specialists quantify the actual cost of mispricing to help sellers understand the stakes involved. “Overpricing by $25,000 typically costs sellers $35,000 once carrying costs and psychological disadvantage are included.” Quantifying costs motivates accurate pricing.
Conclusion
Pricing mistakes cost home sellers thousands in lost equity, extended market time, and negotiation disadvantage. Yet these mistakes cluster into recognizable patterns that sellers can learn to avoid.
Emotional attachment, purchase price anchoring, dismissal of professional analysis, failure to account for market conditions, poor renovation decisions, condition assessment problems, pricing psychology oversight, strategic underpricing, misplaced trust in aggressive agent promises, and failure to adjust as markets shift represent the most costly errors.
Each mistake has a solution: systematic analysis, professional expertise, market data focus, continuous monitoring, and commitment to data-driven decision-making rather than hope-based speculation.
The home sellers who achieve optimal results implement these solutions. They seek professional valuations from certified specialists, demand detailed analysis and methodology, compare multiple perspectives, monitor market conditions continuously, and adjust positioning as reality dictates.
C-REPS certified professionals specialize in exactly these practices. Their training, market expertise, and commitment to systematic methodology help sellers avoid costly mistakes, achieve accurate pricing, sell efficiently, and capture appropriate market value.
Your home’s pricing determines your financial outcome and your selling timeline. These stakes justify investing time in understanding common mistakes and implementing systematic approaches that protect your interests.
The difference between casual pricing and strategic positioning often proves as simple as avoiding these ten common mistakes and working with professionals who prioritize accuracy over aggressive promises.
Frequently Asked Questions
How do I know if my agent’s pricing is accurate?
Request written analysis showing comparable properties, adjustments made for differences, and market conditions considered. Ask about current inventory levels, average days on market, and recent pricing trends. Compare multiple agent recommendations; consistency between recommendations builds confidence. Large discrepancies warrant investigation or obtaining professional valuations. Ask your agent to defend their pricing against comparable sales data, not against your emotional expectations.
What if an appraiser values my home lower than I expected?
If an appraisal comes in below expected value, understand why before accepting it. Request a detailed appraisal explanation. Sometimes appraisers miss recent renovations or fail to recognize neighborhood improvements. Sometimes appraisers are simply conservative. If the appraisal seems inaccurate, request reconsideration with additional comparable data. But if multiple valuations converge on similar value, accept that this represents realistic market value regardless of your expectations.
Can I price my home above market if I’m willing to wait?
You can list at any price you choose, but results follow predictable patterns. Overpriced homes experience extended market time without offers, eventually requiring price reductions deeper than accurate initial pricing would have required. The patience strategy typically fails because buyers recognize overpricing quickly and focus on properly priced alternatives. Time costs money through carrying expenses. Strategic patience makes sense only when market conditions genuinely support waiting.
How much should I invest in staging before selling?
Staging costs typically range from 1,500-5,000 depending on the extent. Well-staged homes often sell faster and for higher prices than unstaged homes, but staging doesn’t change underlying market value. Invest in staging when it helps buyers envision themselves in your home. Don’t expect staging to overcome fundamental pricing problems. Stage properties accurately priced at market entry; don’t use staging to justify overpricing.
What if I receive an offer that seems low?
Evaluate offers against comparable sales data and recent market activity, not against your emotional expectations. If comparable homes sold for $475,000 and you receive an offer for $465,000, that’s only 2% below recent comparable. Demanding $500,000 based on emotional attachment isn’t realistic negotiation. Reasonable offers warrant serious consideration. Unrealistic demands based on overpricing guarantee extended market time.
How often should I adjust my price if my home isn’t selling?
Monitor comparable sales and market activity weekly. If several comparable homes reduce prices or your competitive set shifts, evaluate whether adjustment makes sense. Pricing adjustment after 7-10 days of minimal activity makes sense. Waiting 30+ days before adjusting pricing signals poor initial pricing decisions. Small adjustments early typically work better than large adjustments late.
Should I price based on what I owe on my mortgage?
Your mortgage balance is irrelevant to your home’s market value. You might owe $400,000 on a home worth $425,000 or $375,000. Market value reflects what buyers will actually pay today, not what you owe or what you need to receive. Pricing based on mortgage balance causes systematic overpricing for sellers with small balances and underpricing for sellers with large balances.
What if comparable homes have sold at prices significantly higher than today’s market?
Past sales, even recent ones, represent historical data. Current market value reflects current conditions. If comparable homes sold for $500,000 six months ago but current comparable homes are selling for $475,000, your pricing should reflect current market conditions. Markets change. Historical prices don’t determine current value.
How do seasonal factors affect pricing?
Spring markets typically move faster than winter markets. Seasonal timing influences buyer activity and pricing power. If you’re selling in December (slow season), pricing might need adjustment from spring pricing to attract limited winter buyers. Conversely, spring pricing authority lets you maintain higher prices. Specialists adjust recommendations for the season.
Can I negotiate commission based on high home value?
Agent commission percentage rarely changes based on home price. Standard commissions range from 5-6% regardless of whether your home sells for $400,000 or $800,000. However, you can negotiate commission in competitive markets or when using discounted brokerages. Commission negotiation shouldn’t drive pricing decisions. Price for market reality; negotiate commission separately.
Home Seller’s Guide: What to Expect During a Professional Property Valuation
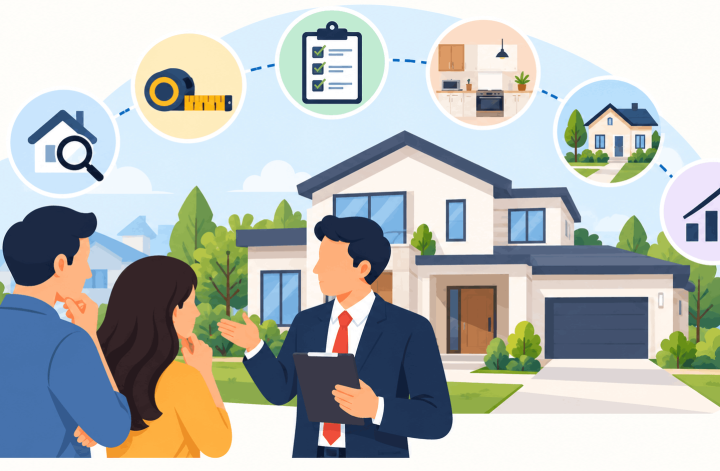
When you first decide to explore selling your home, one of the earliest and most important steps is getting a professional property valuation. Yet many home sellers approach this process with uncertainty. What exactly happens during a valuation? What should you prepare? How long does it take? What will the professional evaluate? What questions should you ask?
Professional property valuations are fundamentally different from casual online estimates or your personal attachment to your home’s worth. A valuation conducted by a trained, certified professional provides an objective assessment grounded in market data, comparable properties, and systematic analysis. Understanding what happens during this process reduces anxiety and helps you make confident decisions about selling.
This guide walks home sellers through the complete property valuation experience. We’ll explain what to expect before, during, and after the valuation, how professionals approach their work, what factors they evaluate, and how to position yourself for the most accurate and favorable assessment possible.
What Is a Professional Property Valuation?
A professional property valuation is a systematic evaluation of your home’s market value conducted by a trained real estate professional. Unlike casual estimates or online tools, professional valuations combine comparable sales data, property condition assessment, market analysis, and expert judgment to determine what your home is worth in today’s market.
It’s important to understand what a valuation is not. A professional valuation is not an appraisal. Appraisals are ordered by lenders and follow strict federal standards. Valuations are more flexible assessments conducted for various purposes, including pricing guidance, refinancing decisions, investment analysis, or simply understanding your home’s value.
C-REPS professionals conduct valuations as trained, certified real estate agents and brokers. They’re not appraisers, but they are extensively trained in valuation methodology through the National Association of BPO Professionals (NABPOP) certification program. This training distinguishes them from typical agents who may rely more on intuition than systematic analysis.
The purpose of a valuation is straightforward: to provide an accurate, defensible estimate of what your home is worth based on current market conditions, comparable properties, and property-specific factors.
Why Professional Valuations Matter
In an industry where pricing accuracy directly affects financial outcomes, professional valuations serve several important functions for home sellers.
Pricing guidance for sale. If you’re listing your home, an accurate valuation establishes the foundation for an appropriate listing price. Overpricing by even 5-10% can dramatically reduce buyer interest and extend your time on market. Accurate pricing attracts buyers and generates momentum.
Refinancing decisions. Understanding your home’s current market value helps you make intelligent refinancing decisions. If your home has appreciated, you may have sufficient equity to refinance or access equity through a cash-out refinance.
Estate or divorce planning. When homes are part of estate settlements or divorce agreements, an objective valuation by a certified professional prevents disputes and ensures fair division of assets.
Investment analysis. If you’re considering investment properties, professional valuations provide the market-based data needed for sound investment decisions.
Insurance coverage verification. Understanding your home’s current market value helps ensure your insurance coverage is adequate for replacement value.
The common thread: professional valuations transform guesswork into data-driven decision-making. For a transaction involving your most valuable asset, the cost of professional valuation is trivial compared to the financial consequences of mispricing.
Before the Valuation: What Sellers Should Know
Professional valuations typically require scheduling in advance. When you contact a C-REPS professional or other certified valuation specialist, be prepared to provide basic information about your property.
Property basics include your home’s address, type (single-family, condo, multi-unit), age, size (square footage), number of bedrooms and bathrooms, lot size, and any major improvements or renovations.
Timeline flexibility matters. Most valuations can be scheduled within a few days, but professionals appreciate advance notice when possible. If you need a valuation urgently, communicate that when requesting the appointment.
Access requirements should be clarified. The valuation professional will need access to all areas of the property, including the attic, basement or crawl space, garage, and exterior. Ensure that any security systems are disabled or that you’ll be present to grant access.
Availability preferences help schedule efficiently. Professionals often have preferred times for valuations. Morning or midday appointments typically work better than early evening, as professionals want adequate light for exterior evaluation and photography.
Recent improvements or repairs should be noted when scheduling. If you’ve recently replaced the roof, updated the kitchen, or completed other significant work, mention this. The professional will ask detailed questions about these improvements.
Known issues or concerns can be mentioned upfront, though professionals will identify these themselves during the evaluation. If there’s a history of roof leaks, foundation concerns, or other issues, this context can be helpful.
When the appointment is scheduled, the professional will likely confirm the appointment date and time, sometimes providing guidance on how to prepare the home.
Preparing Your Home for Valuation
While professionals conduct valuations for properties in various conditions, preparing thoughtfully helps ensure the valuation is accurate and favorable. Preparation is not about deception; it’s about allowing the professional to see your home clearly.
Deep cleaning throughout makes the most significant difference. A thoroughly clean home presents better and allows professionals to assess condition rather than be distracted by clutter or dirt. Pay special attention to kitchens, bathrooms, and high-traffic areas.
Declutter to show space. Remove excess furniture, personal items, and clutter that obscures room size and layout. A home that looks spacious and organized presents better than one packed with belongings.
Address obvious maintenance issues. Fix leaky faucets, replace burned-out light bulbs, repair broken cabinet doors, and address other visible maintenance problems. These signal poor care and create negative impressions.
Ensure good lighting. Open curtains and blinds to maximize natural light. Replace any burned-out bulbs in interior fixtures. Good lighting makes spaces look larger and more inviting.
Organize accessibly. If the professional requests to see the attic or basement, have these spaces as organized as possible. This creates a favorable impression about overall home maintenance.
Prepare documentation. Gather receipts or records for major improvements, roof replacement, HVAC servicing, electrical or plumbing updates, or other significant work. Having this information readily available helps the professional understand your home’s condition and investment in maintenance.
Secure pets. Arrange to have pets confined or boarded during the valuation. Pets create distractions and potential liability concerns for the professional.
Ensure access. If you have security systems, gate locks, or other access restrictions, have these ready to grant the professional entry. Difficult access can complicate the valuation process.
The goal is straightforward: help the professional see your home’s best features without obstacles or distractions.
During the Valuation: What Happens
Most residential property valuations require 30 minutes to an hour, depending on the property’s size and complexity. Understanding the typical process reduces surprises.
Initial walkthrough. The professional typically begins with an exterior evaluation, examining the property’s curb appeal, roof condition, siding, windows, doors, landscaping, and overall maintenance. They’ll photograph or note significant features and condition.
Interior systematic evaluation. Moving inside, the professional systematically evaluates each room, noting size, condition, flooring, walls, ceilings, lighting, and fixtures. They’ll take measurements of major living spaces and note architectural features, windows, and condition issues.
Kitchen and bathroom focus. Kitchens and bathrooms receive particular attention because they significantly impact value. Professionals note appliance age and condition, cabinet quality, countertop materials, plumbing fixtures, and layout functionality.
Systems inspection. The professional evaluates visible evidence of major systems, including HVAC (furnace, air conditioning), electrical panel (updated or outdated), plumbing (evidence of leaks or corrosion), water heater age, and roof condition. They’re not conducting detailed inspections, but they note obvious issues.
Condition assessment. Throughout the walkthrough, the professional evaluates overall condition, noting deferred maintenance, recent updates, cosmetic condition, and any obvious problems like water damage, foundation cracks, or pest evidence.
Measurement and documentation. The professional takes measurements of major rooms and living areas, photographs the exterior and key interior spaces, and documents significant features, improvements, or condition issues.
Exterior and site evaluation. They examine the lot size, landscaping, driveway condition, drainage, and any site-specific factors affecting value. For multi-level homes, they note the number of stories and any unusual architectural features.
Comparable sales analysis. While some of this occurs in the office, the professional may discuss comparable properties they’re aware of in the local market, asking questions about your home’s positioning relative to recent sales.
Seller communication. The professional will likely ask you questions about your home, recent improvements, maintenance history, neighborhood changes, and your understanding of the market. They’re gathering context that helps refine their valuation.
Throughout this process, professional valuators maintain objectivity. They’re evaluating your property systematically against comparable properties and market data, not making personal judgments about your home or its features.
What Professionals Evaluate: Key Factors
Understanding what professionals focus on helps you recognize the factors that truly drive valuation and where preparation matters most.
Property condition ranks high in valuation factors. Homes in excellent condition command premiums. Properties requiring deferred maintenance see value reduction. Condition is visible and directly impacts what buyers will pay.
Square footage and layout affect value significantly. Larger homes generally command higher prices, but unusual layouts or low ceilings can reduce value per square foot.
Bedroom and bathroom count matters, particularly for residential properties. Homes with fewer bedrooms than comparable properties sell at a discount. Additional bathrooms add value disproportionate to their cost.
Lot size affects value based on market preferences and local norms. Larger lots may be valued highly in some markets; they’re irrelevant or undesirable in others.
Age and construction quality influence valuation. Newer homes typically command premiums, though well-built older homes may hold value. Materials and construction methods affect assessed value.
Location and neighborhood are critical. Homes in desirable locations with good schools, walkability, or commute access command premiums. Neighborhood trends affect value trajectory.
Recent improvements and updates can add value. A new roof, HVAC, plumbing, electrical updates, kitchen renovation, or bathroom updates all contribute to higher valuation if completed professionally.
Energy efficiency increasingly matters to buyers. Homes with energy-efficient windows, insulation, HVAC systems, or solar power may command premiums.
Parking and garage factors vary by market but significantly affect value in urban areas or places with limited parking.
Special features like waterfront access, views, architectural significance, or exceptional lot characteristics may justify premium pricing.
The valuation professional weighs these factors systematically, comparing your home to recent comparable sales and adjusting for differences. The result is a valuation grounded in comparable sales analysis, current market conditions, and professional expertise.
Understanding the Valuation Report
After completing the valuation, the professional prepares a detailed report. Understanding what this report contains helps you evaluate its accuracy and use it effectively.
The executive summary typically includes the property address, valuation date, property type, and the appraiser’s or valuer’s conclusion about market value.
Property description documents the subject property’s characteristics, including age, size, bedroom and bathroom count, construction quality, special features, and current condition.
Comparable sales analysis shows the properties used to establish market value, including sale prices, adjustments for differences, and the valuation conclusion drawn from comparable sales.
Condition assessment documents visible condition issues, recent improvements, and maintenance level. This section supports the concluded value by explaining how condition factors into the valuation.
Market analysis provides context about local market conditions, absorption rates, inventory levels, and market trends affecting the property.
Detailed breakdown often shows how the professional arrived at the valuation, including what factors supported value and what factors reduced value.
Photographs document the property’s condition, exterior appearance, key interior spaces, and notable features or issues.
The report’s level of detail varies depending on the valuation’s purpose and the professional’s methodology. Professional C-REPS valuations typically provide comprehensive detail supporting the concluded value.
Common Questions Sellers Ask During Valuations
Home sellers often have questions during the valuation process. Professional valuators welcome reasonable questions that help them understand the property and your goals.
How does my home compare to similar properties? This is reasonable to ask. Professionals can explain how recent comparable sales inform the valuation and how your home’s condition, features, and location compare to properties used for comparison.
What improvements would add most value? Professionals can offer perspective on which improvements might increase value most efficiently, though they’re typically not providing renovation consulting.
Is this valuation for listing purposes? Understanding the valuation’s intended use helps professionals interpret your question. Valuations for sale pricing may differ slightly from valuations for refinancing, as they may account for market-specific positioning.
What’s your assessment of the local market? Professionals typically offer perspective on whether the market is strong or weak, inventory levels, and demand characteristics.
How long should the home take to sell at this value? This is reasonable to discuss. Market conditions, competition, and positioning all affect time-on-market estimates.
Are there obvious issues that would concern buyers? This is an important question. Professionals can highlight condition issues that inspectors will certainly identify and that buyers will use in negotiations.
Questions to avoid include asking the professional to deliberately inflate or deflate the valuation, asking them to suggest illegal pricing strategies, or testing their objectivity with biased scenarios. Professional valuators maintain objectivity and won’t be swayed by seller pressure to adjust valuations beyond what market data supports.
After the Valuation: Using the Report Effectively
Once you receive the valuation report, several important next steps follow.
Understand the valuation. Read through the report carefully, understanding not just the concluded value but the reasoning behind it. Ask the professional to clarify anything unclear.
Compare to your expectations. If the valuation differs significantly from your expectations, discuss this with the professional. What factors caused the difference? Are you missing context about recent comparable sales or market conditions?
Use the valuation for strategic decision-making. If you’re selling, the valuation informs your listing price. If you’re refinancing, it determines your available equity. Use the professional’s analysis to make informed decisions.
Keep documentation. Store the valuation report securely. You may need it for refinancing, tax purposes, insurance considerations, or future reference.
Discuss pricing strategy. If you’re listing, work with your real estate professional to translate the valuation into an appropriate listing price. Market positioning, marketing strategy, and condition all factor into the final listing price decision.
Share with relevant parties. If you’re in a divorce or estate settlement, the valuation provides an objective basis for discussions about asset division.
Update your insurance. If the valuation significantly exceeds your home’s insured value, contact your insurance agent to ensure adequate coverage.
Valuation vs. Appraisal: Understanding the Difference
Many home sellers confuse valuations with appraisals. Understanding the distinction helps you recognize which service you need.
Appraisals are ordered by lenders and follow strict federal standards (USPAP, Uniform Standards of Professional Appraisal Practice). Appraisers are licensed and regulated. Appraisals are required for mortgage lending and provide the value the lender will use to determine loan-to-value ratios.
Valuations are conducted by trained real estate professionals using systematic methodology but without the rigid federal standards governing appraisals. Valuations are more flexible and used for various purposes, including pricing guidance, investment analysis, and refinancing decisions.
For home sellers, valuations are typically more relevant than appraisals. Valuations provide accurate market pricing information and help determine appropriate listing prices. Appraisals become relevant when you’re refinancing or dealing with mortgage lenders.
A C-REPS professional provides valuations trained in systematic methodology and market analysis. This is distinct from an appraisal but provides a professional, defensible assessment of market value.
Choosing a Professional Valuation Provider
Not all professionals providing valuations are equally qualified. Understanding what distinguishes quality valuation providers helps you select someone you can trust.
Certification matters. C-REPS professionals complete training and certification through NABPOP, demonstrating commitment to professional standards and systematic methodology. Certified professionals have passed exams and maintain continuing education requirements.
Local market knowledge is essential. A professional who understands your specific market, recent comparable sales, local trends, and neighborhood characteristics provides more valuable guidance than someone unfamiliar with your area.
Experience counts. Professionals who have valued hundreds or thousands of properties bring pattern recognition and expertise that newer professionals lack.
Professional reputation is important. References from past clients, online reviews, and recommendations from real estate professionals all signal quality and reliability.
Transparent methodology helps. Professionals willing to explain their approach, show the comparables they used, and discuss their reasoning inspire confidence.
No pressure or bias. Trustworthy professionals provide objective valuations regardless of whether you want them higher or lower. Professionals pushing toward predetermined conclusions are prioritizing something other than accuracy.
When seeking a valuation, ask about the professional’s qualifications, experience, and methodology. Don’t simply accept the first estimate; compare perspectives from multiple qualified professionals if the stakes are high.
Common Valuation Mistakes and How to Avoid Them
Several common mistakes can compromise valuation accuracy or create problems for sellers later.
Failing to disclose known issues undermines the valuation’s reliability. If you know about roof problems, foundation concerns, or other issues, full disclosure helps professionals conduct accurate valuations and prevents surprises during buyer inspections.
Overstating recent improvements without documentation weakens the valuation. Professional-quality work with receipts and permits carries more weight than claimed improvements without evidence.
Expecting valuations to match emotional attachment. A home may feel worth a certain amount to you, but market value is determined by comparable sales, not personal attachment. Objective assessment requires acknowledging market reality.
Neglecting home presentation. A dirty, cluttered home creates unfavorable impressions affecting valuation. Preparation costs nothing compared to potential impact on assessed value.
Arguing with the professional. If you disagree with a valuation, ask questions and understand the reasoning. Arguing won’t change the professional’s assessment if it’s grounded in market data.
Using outdated valuations. Market conditions change. A valuation from a year ago may not reflect current conditions. Get current valuations when market conditions have shifted significantly.
Assuming online tools replace professional valuations. Online estimates provide ballpark figures but lack the detailed analysis and market knowledge of professional valuations.
Avoiding these mistakes ensures that your valuation is accurate, defensible, and useful for decision-making.
Frequently Asked Questions
How long does a property valuation take?
Most residential property valuations require 30 minutes to an hour on-site. The professional may need additional time in the office to prepare the report, typically one to three business days. From scheduling to receiving the report, expect a one-to-two-week turnaround.
How much does a professional property valuation cost?
Valuation fees vary by location and professional, typically ranging from $300 to $500 for residential properties. Some professionals provide free consultations or pricing opinions. C-REPS professionals’ fees reflect their training and certification. Compare fees but prioritize professional qualification over price alone.
Can I get a free valuation instead of paying for a professional one?
Buyer’s agents sometimes provide free “comparative market analyses” to encourage listing with them. These have value for pricing guidance but lack the objectivity and detailed analysis of independent professional valuations. For significant financial decisions, professional valuation fees are worthwhile investments.
Do I need to be home during the valuation?
Being present is helpful, as the professional may ask questions about improvements, maintenance history, or the home’s features. However, some professionals prefer clients not be present to avoid bias. Confirm the preference when scheduling.
Will the valuation affect my property taxes?
No. Property valuations for sale pricing or refinancing decisions are separate from property tax assessments. Your local assessor determines property values for tax purposes through different methodologies, typically on a multiyear cycle.
What if I disagree with the valuation?
Discuss your concerns with the professional. They can explain their reasoning, show comparable sales used, and discuss factors affecting the valuation. If you still disagree, you can obtain a second valuation for comparison. However, if multiple qualified professionals reach similar conclusions, the market is likely telling you something about your home’s value.
Is a valuation the same as what my home will sell for?
A valuation estimates market value based on current conditions and comparables. The actual sale price depends on buyer demand, market conditions, listing pricing, marketing effectiveness, and negotiations. The valuation provides a baseline; the actual price may be higher or lower depending on these factors.
How do I know if a valuation is accurate?
Accurate valuations are grounded in recent comparable sales, systematic analysis, and current market conditions. If the valuation significantly exceeds all recent comparable sales without justification, it’s likely optimistic. If it’s significantly below comparable sales, it’s likely conservative. The most accurate valuations typically fall within the range of recent comparable sales with appropriate adjustments.
Should I get a valuation before listing my home?
Yes. A pre-listing valuation helps determine an appropriate listing price, positions you for a faster sale, and prevents overpricing that extends your time on market. The valuation’s cost is trivial compared to the expense of holding an overpriced property.
Can I use an appraisal from a refinance instead of getting a separate valuation?
Possibly, but appraisals are conducted for lender purposes and may not align perfectly with market pricing for sale purposes. The lender’s appraisal is designed to protect the lender, not to establish optimal listing prices. A current valuation specifically for sale pricing is preferable if you’re planning to sell soon.