How Interest Rates Affect Property Values: Expert Analysis
Few forces shape the housing market as directly as interest rates. When mortgage rates move, buyers’ budgets change, sellers’ pricing decisions change, and the number of homes that actually sell changes with them. Yet many people still ask a simple question: if rates go up, do home values fall?
The honest answer is that interest rates influence property values through several channels at once, and those channels do not always move in the same direction. This analysis explains how rates affect what buyers can pay, why the link between rates and prices is not one-to-one, what current forecasts suggest for 2026, and how professionals who specialize in accurate pricing account for rate changes when they value a home.
How Interest Rates Reach Property Values
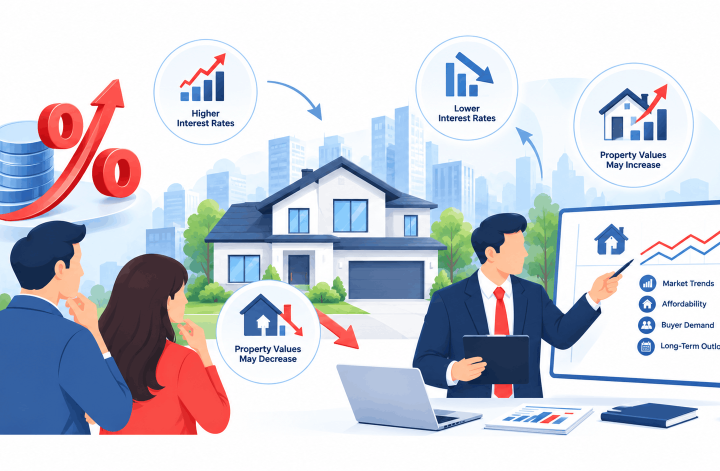
Most homes are bought with a mortgage, so the interest rate on that loan becomes a central part of the price a buyer can afford. A property’s market value is not set by rates alone, but rates shape the pool of people who can pay a given price and the terms under which they are willing to pay it.
Three channels do most of the work.
The Affordability Channel
The most direct effect is on monthly payments. Consider a buyer borrowing $400,000 on a 30-year fixed mortgage. At 6%, the principal and interest payment is about $2,398 per month. At 7%, it rises to about $2,661, roughly $263 more each month, or about 11% higher, for the same loan amount.
Put differently, if a buyer can comfortably afford $2,398 per month, a 7% rate reduces the loan they can support to about $360,000. That is roughly 10% less purchasing power for the same budget. Every percentage point increase in mortgage rates reduces what a given income can buy by a similar order of magnitude.
When many buyers lose purchasing power at once, demand softens. Weaker demand usually shows up first in fewer offers, longer time on the market, and more negotiation, and only later in lower prices.
The Buyer Demand Channel
Rates also affect how many people decide to enter the market at all. Higher rates generally reduce buyer demand, and some buyers choose to wait for better conditions. Tembo, a mortgage advisory firm, has argued that if rates stay at or near current levels, more buyers may hold off purchasing, and that an overpriced home will struggle to sell in that environment.
This is one reason rate changes can matter more than their size suggests. A fall in rates can bring buyers back quickly, and the surge in demand can push prices up if supply does not keep pace.
The Lock-In Channel
The third channel is less obvious. Many homeowners locked in low mortgage rates during the years when borrowing was cheap. Those owners have a strong financial reason to stay put, which keeps the supply of existing homes for sale low. Morgan Stanley strategists have pointed to this lock-in effect as a factor that has constrained supply and supported higher prices, even when rates are elevated.
This creates a counterintuitive result. High rates reduce buyer demand, but they can also reduce supply, so prices may hold up better than a simple affordability model would predict. The net effect depends on which force is stronger in a given market.
Why the Relationship Is Not Simple
Rates and prices move together in many periods, but the relationship is not a fixed formula. Economic conditions can change how rates affect values.
During periods of strong economic growth and rising incomes, buyers may be willing to pay more even when rates are higher, which can keep prices firm. During periods of economic weakness, higher rates can reduce both demand and prices more sharply.
The housing market’s history illustrates this. The period before the 2008 financial crisis involved rising prices and widespread borrowing, followed by a sharp decline in values and sharp changes in lending conditions. Today’s market differs in important ways, including the prevalence of fixed-rate loans and the level of homeowner equity, so historical episodes should be read as context rather than a forecast.
Rates also reach valuations through the financing environment. Investors who buy property with borrowed money feel rate changes directly in their carrying costs, which affects how much they are willing to pay for rental and commercial properties. Residential buyers, meanwhile, respond to monthly payments and their personal budgets.
What Current Forecasts Show
Forecasters are not in full agreement about where rates and prices are headed, which is itself a useful signal about uncertainty.
Freddie Mac’s Primary Mortgage Market Survey put the average 30-year fixed rate in a range of roughly 6.11% to 6.25% in early 2026. Forecasts for the end of 2026 vary. The Mortgage Bankers Association projects rates near 6.4%, Realtor.com projects about 6.3%, and Fannie Mae has been more optimistic, expecting around 5.9%. Morgan Stanley strategists have suggested rates could decline to around 5.75%, particularly in the first half of the year.
For prices, the picture is similarly mixed. Zillow forecasts that home values will rise just 1.2% this year, while Cotality, a real estate analytics firm, has reported that annual home price appreciation slowed from 3.4% in January to 1.1% by October, a slowdown it attributed to elevated mortgage rates and persistent affordability challenges. Cotality’s own forecast projects future annual growth of 4.3% for October 2026, and it warns that a notable drop in rates combined with low supply could reaccelerate price gains.
| Indicator | Forecast Range Cited | Key Takeaway |
| 30-year rate, end of 2026 | About 5.75% to 6.4% | Forecasters expect modest movement, with no consensus on direction |
| Home price change | About 1% to 4% | Growth is expected to be slower than in recent peak years |
| Inventory | Gradual improvement | Supply is expected to rise slowly, supporting more balanced conditions |
The lesson from these forecasts is that rates and prices are linked through the supply side as well as the demand side. A rate decline alone does not guarantee falling or rising prices. The combination of rates, supply, and local demand determines the outcome.
Rate Changes Do Not Hit Every Property Equally
One of the most important insights for anyone analyzing property values is that interest rates affect different segments of the market in different ways.
Entry-Level Homes
Starter homes and lower-priced properties are often most sensitive to rate changes. Buyers in this segment tend to rely heavily on mortgage financing, and a small change in rate can change qualification for a loan. When rates rise, the number of qualified buyers can drop quickly, which can put pressure on prices in the most affordable price bands.
Higher-Priced Homes
Buyers of higher-priced homes may use more cash or have more financial flexibility, so rate changes can affect them differently. Some buyers in this segment are less sensitive to a half-point change, while others still face meaningful differences in monthly costs.
Investment Properties
Investors feel rates through financing costs, rental yields, and the spread between borrowing costs and expected returns. When rates rise, investors often demand lower purchase prices to earn their target return. When rates fall, they may be willing to pay more, which can lift values in rental-heavy neighborhoods.
Local Markets
National averages can hide enormous variation. A market with rising inventory and softer employment may see prices fall even as the national trend is flat. A market with limited new construction and strong job growth may see prices rise despite high rates. This is why a national rate forecast is a starting point, not a valuation tool.
The Valuation Side: How Professionals Account for Rates
A property’s value is ultimately what a willing buyer will pay, and that figure depends on current financing conditions. For this reason, accurate pricing requires professionals to account for rates rather than relying on past sales alone.
C-REPS professionals are licensed real estate agents and brokers who complete specialized pricing training through the National Association of BPO Professionals (NABPOP) certification program. Their work emphasizes what buyers are actually willing to pay in a specific local market today. In a higher-rate environment, that often means paying close attention to how buyers are responding to listings, how many are qualifying at current payment levels, and whether recent sales reflect the financing reality of this period rather than an earlier one.
Rates matter for valuation in several practical ways:
- Recent sales may reflect different financing conditions. A home that sold during a low-rate period may not be a reliable comparison for a home listed when rates are higher.
- Buyer pool size matters. If fewer buyers can afford a given price, the likely sale price may need to adjust.
- Time on market is a signal. Longer listing periods can indicate that a price is out of step with current buyer willingness to pay.
- Concessions tell a story. Seller credits, rate buydowns, and closing cost help can reveal how much buyers need financial relief to complete a purchase.
A useful principle is to ask whether a comparable sale reflects the same market conditions you face today. If the answer is no, the sale still matters, but it needs adjustment.
Practical Examples
Example One: A Seller in a Higher-Rate Market
Suppose a homeowner in a mid-sized metro area believes their home is worth what a similar home sold for two years earlier, when mortgage rates were noticeably lower. Their neighbor’s sale may still be useful, but the current buyer pool is smaller at today’s rates. A pricing professional would compare recent sales from the past several months, check how many similar homes are currently listed, and look at how quickly they are selling. The likely conclusion is that the home should be priced to current buyer capacity rather than the peak of the earlier market.
Example Two: A Buyer Deciding Whether to Wait
A buyer considering a $400,000 home has two possibilities. At a 6% rate, their payment is about $2,398 per month. If they wait and rates fall to 5%, that payment drops to about $2,147, a difference of roughly $250 per month. But if prices rise while they wait, or if rates rise instead, the advantage disappears. A buyer who can afford the monthly payment today and plans to stay in the home for several years may find that waiting has a real cost. A buyer who is stretched to afford the payment may benefit from a longer wait, but only if they have a clear plan for their finances in the meantime.
These examples show why there is no universal answer. The right decision depends on payment capacity, time horizon, local supply, and the price being negotiated.
Actionable Advice for Buyers, Sellers, and Investors
For buyers:
- Calculate your monthly payment at several rate levels, including one or two percentage points higher than today’s rate, before setting a budget.
- Get pre-approved with more than one lender, since rate and fee differences can meaningfully change your payment.
- Look at homes in the context of local sales and time on market, not only the list price.
- Consider whether a rate buydown, seller credit, or lender credit could offset the payment more effectively than waiting.
For sellers:
- Price based on current buyer capacity, not on a peak market you remember.
- Ask your agent to explain how recent comparable sales reflect today’s financing conditions.
- Be prepared for buyers to ask for concessions when rates are high, and decide in advance what you are willing to offer.
- If the market is slow, act early on pricing adjustments rather than waiting for a rate change to rescue the listing.
For investors:
- Stress-test your returns at higher financing costs, not only at current rates.
- Compare the expected rental yield with your borrowing cost, and avoid assuming that falling rates will automatically lift values.
- Consider how refinancing options and fixed versus variable loan structures affect your risk.
- Recognize that lock-in effects can keep supply tight in some areas, which may support values even when demand softens.
The Bottom Line
Interest rates influence property values through affordability, buyer demand, and the supply of homes for sale, and their effects vary by price range, property type, and local market. Forecasts for 2026 do not agree on the direction of rates or prices, which is a reminder that the relationship depends on many factors at once.
The most useful approach is to focus on what rates mean for your specific situation: your monthly payment, your time horizon, and the comparable sales in your area. For buyers, that means budgeting realistically. For sellers, it means pricing to current buyer capacity. For investors, it means stress-testing returns against higher financing costs. Accurate pricing grounded in local data remains the most reliable way to navigate a market where rates keep shifting.
Frequently Asked Questions
Do higher interest rates always lower home prices?
No. Higher rates usually reduce buyer demand and purchasing power, which can soften prices, but they can also reduce supply because homeowners with low rates are less likely to sell. The net effect depends on local supply and demand, employment, and economic conditions.
How much does a 1% rate increase affect a mortgage payment?
It depends on the loan size and the starting rate. On a $400,000 30-year loan, moving from 6% to 7% increases the monthly principal and interest payment by about $263, or roughly 11%.
Will mortgage rates go down in 2026?
Forecasts differ. Some expect rates to decline modestly by the end of 2026, while others expect them to stay near current levels. No forecast can guarantee the direction, so buyers and sellers should plan for a range of outcomes.
Why are home prices not falling more when rates are high?
Several factors can keep prices from falling sharply. Many homeowners have low locked-in rates and are reluctant to sell, which limits supply. Demand for housing also remains strong in some areas, and high construction costs can limit new supply.
Does a rate drop always make homes more expensive?
Not always, but it can. Lower rates can bring more buyers into the market quickly. If supply is limited, that extra demand can push prices up. If supply is growing, the effect may be smaller.
Should I wait for lower rates before buying a home?
It depends on your finances and your plans. Waiting can make sense if you need more time to build savings or if rates fall enough to offset potential price increases. Buyers who can afford the current payment and plan to stay for several years often find that the cost of waiting is higher than expected.
How do professionals factor interest rates into home pricing?
Pricing professionals look at recent comparable sales, time on market, buyer activity, and concessions. They consider whether past sales reflect current financing conditions and adjust their analysis when they do not.
Can rate buydowns or seller credits offset high rates?
They can reduce the effective cost of a loan in some situations, but the details matter. Buydowns, credits, and fee structures vary, so buyers should compare the total cost of different options rather than focusing only on the headline rate.
Pricing Your Home Right: The Science Behind Accurate Valuations
Your home is likely the most valuable asset you’ll ever own. Yet most home sellers approach pricing with surprising uncertainty, relying on gut feelings, internet estimates, or agent promises rather than systematic valuation methodology.
The consequences of mispricing are substantial. Overprice by just 5-10%, and your home sits on the market for months while other properties sell. Underprice by the same margin, and you leave tens of thousands of dollars on the table. In either case, you sacrifice time, money, and opportunity.
The difference between guesswork and accuracy lies in understanding the science behind home valuation. Professional pricing combines data analysis, market expertise, and systematic methodology to determine what buyers are genuinely willing to pay in your specific market, right now.
This guide explores the framework that certified real estate professionals use to price homes accurately. Whether you’re a home seller preparing for market entry, a buyer seeking to understand property values, or a homeowner curious about your property’s worth, understanding valuation science helps you make better decisions about your most important asset.
Why Accurate Pricing Matters More Than You Think
Pricing a home isn’t an art form. It’s a calculation grounded in data, comparable properties, market conditions, and buyer psychology. Yet countless homes are mispriced because owners and even agents prioritize wishful thinking over methodical analysis.
The Cost of Overpricing
List your home 10% above market value, and you’ll likely discover that no buyers match your expectations. What happens next varies: aggressive price reductions after months on the market (signaling desperation to savvy buyers), withdrawn listings (damaging future sale prospects), or eventual sales at discounts deeper than your original overpricing mistake.
Overpriced homes experience extended market time, which creates psychological perception problems. Buyers and agents notice when properties linger. Extended listings suggest problems: either the owner is unreasonable about price, the property has hidden issues, or both.
During this extended marketing period, your home competes against newly listed inventory. Properties priced correctly sell. Your overpriced property gets overlooked. The longer this continues, the more negotiating power shifts toward buyers.
The Cost of Underpricing
Conversely, underprice your home, and you lose money directly. List 10% below market value, and you’ll sell quickly. But quick sales mean you’ve given away equity that should have been yours.
Consider this concretely: underpricing a $500,000 home by 10% leaves you $50,000 short. That’s not a small rounding error. That’s real wealth transfer from you to a buyer who recognized the deal.
Underpricing particularly frustrates sellers because it often feels safer psychologically. “Better to sell fast than wait,” many think. Yet this reasoning ignores that accurate pricing also sells relatively quickly while capturing full market value.
The Window Between Purchase and Sale
Homes sell fastest when priced correctly at market entry. This period (first 7-14 days on market) generates maximum buyer attention and competition. Mispriced homes miss this critical window, then require price reductions to attract attention later. By that point, you’ve lost both time and leverage.
Accurate pricing maximizes your position by attracting buyer competition, generating multiple offers, and creating upward price pressure at the point when you have maximum negotiating power.
The Science of Home Valuation
Professional pricing relies on a systematic methodology that removes emotion and prioritizes data. While appraisers (used primarily for mortgage lending) focus on property condition and comparable sales, market pricing specialists also factor in current buyer demand, days-on-market for comparables, and real-time market velocity.
Comparative Market Analysis (CMA)
The foundation of professional pricing is Comparative Market Analysis. Rather than picking random comparable properties, CMA identifies homes that truly parallel your property in meaningful ways.
Key comparables include:
Recently sold properties in your immediate neighborhood or comparable areas (usually within the last 3-6 months)
Properties currently on the market at similar price points (representing active competition)
Properties that failed to sell or were delisted (understanding market resistance levels)
Properties that sold substantially above or below list price (revealing market strength or weakness)
Quality CMA analysis examines at least 8-12 comparable properties, analyzing what makes them similar to and different from your home. An agent claiming they based pricing on three random comps hasn’t conducted serious analysis.
Data Points That Drive Valuation
Professional pricing incorporates systematic data analysis across multiple property characteristics:
Location and Neighborhood: Properties in school districts with high ratings command different pricing than districts with lower ratings. Proximity to employment centers, transit, shopping, and parks influences buyer demand. Neighborhood appreciation trends matter: is the area appreciating or depreciating? Growing neighborhoods with strong demand support stronger pricing.
Property Size and Layout: Square footage is foundational, but layout complexity matters. Open-concept homes may appeal more strongly in some markets than homes with compartmentalized rooms. Number of bedrooms versus bathrooms reflects changing buyer preferences and household compositions.
Age and Condition: Newer homes typically command premiums over older properties, though well-maintained historic homes with character sometimes overcome this. Major systems (HVAC, roof, electrical, plumbing) significantly influence value. Recent renovations and updates add value, but only when aligned with market preferences.
Lot Size and Outdoor Space: In some markets, land value comprises substantial home value. Larger lots appeal to buyers wanting privacy and space. In urban areas, lot size matters far less than walkability and density.
Amenities and Features: Quality kitchens and bathrooms influence buyer perception. Energy efficiency, smart home features, outdoor living spaces, and garage configurations all affect value. However, over-customization can limit buyer appeal; homes with unusual layouts or extreme personalization may appeal to fewer buyers.
Market Conditions: Inventory levels determine pricing power. Balanced markets with 4-6 months of inventory at current sales pace support stable pricing. Buyers’ markets with excess inventory (8+ months of inventory) push prices downward as competition intensifies. Sellers’ markets with limited inventory (under 2 months) create upward price pressure.
The Pricing Methodology: From Data to Market Value
Converting data into accurate pricing requires a systematic methodology that professional specialists follow consistently.
Step 1: Identify True Comparable Properties
Start by identifying properties that genuinely parallel your home. Comparables should share fundamental characteristics: similar square footage (within 10-20%), comparable lot size, similar age or condition, matching bedroom and bathroom count, and location in the same or closely adjacent neighborhoods.
Many amateurs make the mistake of using properties that are somewhat similar but miss critical differentiators. A home with a pool isn’t truly comparable to one without if market research shows pools don’t add proportional value in your area. A home recently renovated differs substantially from a home in its original condition.
Professional analysis acknowledges these differences, adjusting comparable prices upward or downward based on how your home compares. This adjustment process converts comparable sales into adjusted values that better reflect your home’s likely market value.
Step 2: Calculate Adjusted Values
For each comparable property, professionals analyze:
Sale price and date (more recent sales weigh more heavily than older sales)
What the property sold for relative to list price (revealing buyer demand: did it sell over list or below?)
Time on market before sale (fast sales suggest proper pricing; long marketing periods suggest overpricing or property issues)
Any unique circumstances (foreclosure sales, estate sales, buyer and seller relationships that might affect pricing)
Adjustments for differences between comparable and subject property (your home)
Adjusted comparable values provide a range rather than a single “right” price. If your home’s adjusted comparable values range from $445,000 to $465,000, your accurate list price likely falls within this range, adjusted slightly for current market conditions.
Step 3: Account for Market Conditions
Current market conditions significantly influence pricing. The same home priced at $500,000 in a balanced market might appropriately list at $475,000 in a buyers’ market or $525,000 in a sellers’ market.
Professional specialists analyze:
Current inventory levels and months of supply
Average days on market for homes in your category
Recent pricing trends (are comparable homes selling for increasing or decreasing prices?)
Buyer demand indicators (are homes receiving multiple offers or sitting?)
Seasonal considerations (some markets shift seasonally; spring markets differ from winter markets)
Economic indicators affecting buyer behavior (interest rates, employment, economic confidence)
Common Valuation Mistakes That Cost Money
Understanding what professionals avoid helps explain why systematic methodology matters.
Mistake 1: Using Only Online Estimates
Zillow Zestimates, realtor.com estimates, and similar automated tools provide general ranges but lack the precision of professional analysis. These tools use algorithms based on historical data without considering current market conditions, neighborhood-specific dynamics, or property-specific details.
Online estimates often miss recent renovations, fail to recognize neighborhood appreciation trends, and don’t account for competitive inventory entering your market. Relying on them for pricing decisions risks substantial mispricing.
Mistake 2: Anchoring on Your Purchase Price
What you paid for your home is irrelevant to its current market value. Markets shift. Your $400,000 purchase five years ago might support a $500,000 sale or a $370,000 sale depending on market conditions. Anchoring on purchase price leads to overpricing if your market appreciated less than expected or underpricing if your market appreciated more substantially.
Professional specialists focus exclusively on current market value, not historical acquisition cost.
Mistake 3: Emotional Attachment to Features
Owners frequently overvalue personal upgrades. That $50,000 custom kitchen renovation might add $30,000 to market value. The high-end landscaping you installed because you love gardens might appeal to relatively few buyers. Personal theaters, custom wine rooms, and other highly specific installations can actually limit buyer appeal.
Professionals evaluate features from a buyer’s perspective: what do actual market participants value, not what the owner values?
Mistake 4: Ignoring Market Velocity
A home priced correctly in a fast-moving market might be overpriced in a slowing market. Professional specialists track not just comparable prices but market velocity. If comparable homes sold in 10 days on average six months ago but are now selling in 25 days, market conditions have shifted. Pricing needs adjustment accordingly.
Mistake 5: Comparing to Aspiration Rather Than Reality
Comparing your home to the nicest homes in your neighborhood provides inflated value perspectives. Accurate analysis compares to homes actually competing for the same buyers: homes similar to yours, selling during similar timeframes, in similar market conditions.
The C-REPS Difference: Why Certification Matters
C-REPS professionals distinguish themselves from typical real estate agents through specialized training, rigorous certification, and commitment to systematic valuation methodology.
Professional Certification and Training
C-REPS designation requires completion of specialized training covering valuation methodology, market analysis, pricing strategy, and professional ethics. Agents must pass certification exams demonstrating competency, then maintain their designation through continuing education and professional standards compliance.
This formalized training distinguishes C-REPS specialists from agents who learned pricing through trial and error or who approach each listing without systematic methodology.
Deep Market Expertise
C-REPS professionals combine their training with extensive local market knowledge. They understand not just what homes sold for, but what current buyers are actually willing to pay in today’s market. They track inventory levels, buyer competition, and market velocity continuously.
This real-time market knowledge prevents the common mistake of relying solely on historical comparable sales without adjusting for current conditions.
Collaborative Network Advantage
When you work with a C-REPS professional, you gain access to an entire network of certified specialists. This collaboration means your listing benefits from multiple perspectives on valuation, broader market insight than any solo agent could provide, and coordinated marketing efforts across a professional network.
Accuracy-Focused Approach
C-REPS professionals are held to higher professional standards regarding pricing accuracy. Rather than optimizing for quick sales or inflated list prices that eventually require reductions, they prioritize accurate positioning that sells homes relatively quickly at strong prices.
How to Work with Pricing Specialists
Understanding the valuation process helps you work effectively with professionals.
Before Meeting with Specialists
Gather information about your home: accurate square footage, lot size, age, major systems, recent renovations, and property features. Document the condition of your home objectively. Collect information about your neighborhood: school district ratings, neighborhood appreciation trends, proximity to amenities.
Understand your timeline and goals. Are you selling quickly to relocate? Do you have flexibility? Are you targeting maximum price regardless of timeline? These factors influence positioning strategy.
During CMA Discussion
Ask your specialist to show you the comparable properties they selected and explain why each was chosen. Understand the adjustments they made for differences between comparables and your home. Ask about current market conditions and how they influenced pricing recommendations.
A quality specialist will show their work, walk you through the analysis, and welcome questions about their methodology.
Pricing Presentation
Your specialist should provide a detailed pricing recommendation with rationale, not just a single number. The recommendation should include a supported price range with explanation for adjustments from comparable sales.
Ask specifically about recent market trends affecting pricing. How many homes in your category are currently on market? What’s the average days on market for recent sales? Are homes selling above, at, or below list prices?
Ongoing Monitoring
Market conditions change. If your home is on the market for 15 days without showings, that’s different from receiving multiple offers. Professional specialists monitor market response and recommend pricing adjustments when market conditions warrant.
Expert Insights: What Market Specialists Know That Others Don’t
Professional pricing specialists understand nuances that casual observers miss.
Buyer Psychography Matters
Homes listed at $499,000 receive different buyer attention than identical homes listed at $505,000, even though the difference is minimal. Pricing just below psychological price points (full million markers, hundred-thousand markers) affects buyer search patterns and perception.
However, this tactical pricing only works when the home is already accurately positioned. Psychological pricing can’t overcome fundamental mispricing.
Seasonal Patterns Are Real
Spring markets typically generate stronger buyer demand and competition. Winter markets move more slowly. Year-end holidays reduce buyer activity. Professional specialists understand these patterns and price accordingly, recognizing that a home selling in January faces different market conditions than an identical home selling in May.
Days on Market Signals More Than You Think
Homes that sell quickly (under 10 days) suggest they were priced correctly or below market. Homes that sell after 30+ days signal potential overpricing or property issues to savvy buyers, even if the property eventually sells.
This creates incentive for accurate pricing at market entry. Once a home is perceived as overpriced (signaled by extended market time), recovering from that perception proves difficult.
Listing Price Anchors Buyer Perception
Your initial list price influences buyer perception throughout the selling process. If you list at $500,000 then reduce to $475,000 six months later, buyers anchor to the original $500,000 and perceive the reduction as concession rather than accurate positioning. Conversely, homes priced accurately at $475,000 from the start generate stronger buyer perception and quicker sales.
The Financial Impact of Accurate Pricing
Consider concrete financial scenarios to understand accurate pricing’s value.
Scenario 1: Overpriced Home
List price: $520,000 (10% above accurate market value of $475,000)
Result: Home sits for 90+ days, receives minimal showings, generates no offers
Price reduction after 60 days: $500,000 (still overpriced)
Final sale price after 120 days: $465,000 (15% below original list price)
Outcome: Extended marketing period, lower final price, increased carrying costs (mortgage, taxes, insurance, utilities during extended ownership), psychological perception of desperation, and opportunity cost of capital tied up in unsold home.
Scenario 2: Accurately Priced Home
List price: $475,000 (market value)
Result: Home generates multiple showings in the first week, generates competing offers by day 7
Final sale price after 14 days: $485,000 (101% of list price)
Outcome: Quick sale, strong price, reduced carrying costs, favorable buyer psychology, opportunity to proceed with next transaction.
Financial comparison: The accurately priced home nets approximately $20,000 more than the overpriced home ($485,000 versus $465,000), accomplishes the sale in 1/8th the time, avoids extended carrying costs, and maintains strong buyer perception.
Conclusion
Pricing your home accurately requires far more than guesswork or generic internet estimates. It demands systematic analysis, professional market expertise, and commitment to data-driven methodology that converts comparable properties, market conditions, and buyer behavior into realistic pricing that captures full market value while selling in reasonable timeframes.
The stakes matter significantly. A pricing error of just 5% on a $500,000 home equals $25,000 in direct financial impact. Beyond direct financial cost, overpricing creates extended market time with all its associated carrying costs and negative perception effects. Underpricing leaves wealth on the table permanently.
C-REPS certified professionals specialize in exactly this challenge. Their training, market expertise, and commitment to systematic valuation methodology help homeowners price accurately, sell successfully, and capture appropriate market value.
Whether you’re preparing to sell your home, evaluating your property’s worth, or simply curious about valuation methodology, understanding the science behind accurate home pricing helps you make better decisions about your most valuable asset.
The difference between casual pricing and professional accuracy often proves as simple as working with someone who understands not just comparable properties, but the systematic methodology that converts comparable data into accurate, defensible pricing that serves your interests and respects market reality.
Frequently Asked Questions
How often should I get my home revalued?
Market conditions change continuously. If you’re selling, get a professional valuation immediately before listing. If you own your home and want to understand current value for refinancing, equity access, or insurance purposes, annual revaluations make sense during active market periods. In stable markets, valuations remain relevant for 6-12 months. In rapidly changing markets, revaluate quarterly. Professional specialists monitor market conditions and recommend revaluation when conditions shift meaningfully.
What’s the difference between a professional valuation and an appraisal?
Appraisals (ordered by lenders for mortgage purposes) focus on property condition and comparable sales to determine lending value. Appraisers follow specific standardized processes and deliver formal appraisal documents. Professional valuations focus on current market value and what buyers will actually pay today. Specialists consider not just comparable sales but current inventory levels, buyer demand, and market conditions. Appraisals typically run $400-600; professional valuations vary widely depending on who provides them (some agents provide free valuations with listing agreements).
How much does home staging affect valuation?
Staging addresses buyer perception and home presentation, not fundamental property value. A well-staged home may show better during showings and influence buying decisions positively, but it doesn’t change the property’s actual market value. Valuation methodology bases pricing on comparable properties’ actual sale prices and current market conditions, not on presentation. That said, strategic staging that helps buyers envision themselves in the home can support achieving full market value by improving showings and buyer confidence.
Can my home’s value differ significantly between appraisers?
Yes, inconsistency between appraisals suggests either different appraisers using different comparable properties or different interpretations of condition and adjustments. Values within 3-5% of each other are typical variation; larger differences warrant investigation. Using multiple specialists (appraisers or professional valuators) to validate pricing makes sense for major decisions. If an appraisal comes in significantly below your expected value, understand why before accepting it.
How do I know if my agent’s pricing recommendation is accurate?
Request that your agent show you the comparable properties they used, explain the adjustments they made, and document their analysis in writing. Ask about current market conditions: inventory levels, average days on market, sales above or below list price. A professional will welcome detailed questions about their pricing methodology. If your agent resists showing their analysis or uses vague pricing justifications, consider getting a second professional opinion.
What happens if my home won’t appraise at the sale price?
If a buyer’s lender appraises your home below the agreed sale price, several options exist: renegotiate the sale price downward to match the appraisal, the buyer provides additional down payment to cover the appraisal shortfall, or the sale terminates. Accurate pricing at market entry minimizes this risk; overpriced homes face appraisal shortfall more frequently. If appraisal issues concern you, get a professional valuation before listing to understand realistic market value and price accordingly.
How much should I invest in renovations before selling?
This depends on your specific home, market, and renovation category. Kitchen and bathroom updates typically offer the best return on investment (60-80% of costs recovered). Roof replacement, HVAC updates, and other deferred maintenance typically recover 60-100%. Luxury upgrades and highly personal renovations often recover less than 30%. Rather than assuming renovations increase value, consult with specialists who understand which improvements your specific market values most. Sometimes strategic staging and cleanup provide better ROI than expensive renovations.
Do I need a C-REPS specialist or can any agent price my home?
Any licensed agent can provide a pricing recommendation, but C-REPS certified specialists bring specialized training and formalized commitment to valuation methodology. If accurate pricing matters to you (and it should), working with certified professionals reduces the risk of mispricing. C-REPS specialists have demonstrated competency through testing and maintain their credentials through continuing education, unlike agents without specialized certification.
How do international buyers and investors affect local home pricing?
In some markets, investor and international buyer activity significantly influences pricing. Cash buyers often compete aggressively for properties, pushing prices upward. Investor buyers sometimes focus on cash flow and rental income rather than value, influencing investment property pricing differently than owner-occupant pricing. Professional specialists understand buyer composition in your market and how it affects pricing dynamics.
Home Seller’s Guide: What to Expect During a Professional Property Valuation
When you first decide to explore selling your home, one of the earliest and most important steps is getting a professional property valuation. Yet many home sellers approach this process with uncertainty. What exactly happens during a valuation? What should you prepare? How long does it take? What will the professional evaluate? What questions should you ask?
Professional property valuations are fundamentally different from casual online estimates or your personal attachment to your home’s worth. A valuation conducted by a trained, certified professional provides an objective assessment grounded in market data, comparable properties, and systematic analysis. Understanding what happens during this process reduces anxiety and helps you make confident decisions about selling.
This guide walks home sellers through the complete property valuation experience. We’ll explain what to expect before, during, and after the valuation, how professionals approach their work, what factors they evaluate, and how to position yourself for the most accurate and favorable assessment possible.
What Is a Professional Property Valuation?
A professional property valuation is a systematic evaluation of your home’s market value conducted by a trained real estate professional. Unlike casual estimates or online tools, professional valuations combine comparable sales data, property condition assessment, market analysis, and expert judgment to determine what your home is worth in today’s market.
It’s important to understand what a valuation is not. A professional valuation is not an appraisal. Appraisals are ordered by lenders and follow strict federal standards. Valuations are more flexible assessments conducted for various purposes, including pricing guidance, refinancing decisions, investment analysis, or simply understanding your home’s value.
C-REPS professionals conduct valuations as trained, certified real estate agents and brokers. They’re not appraisers, but they are extensively trained in valuation methodology through the National Association of BPO Professionals (NABPOP) certification program. This training distinguishes them from typical agents who may rely more on intuition than systematic analysis.
The purpose of a valuation is straightforward: to provide an accurate, defensible estimate of what your home is worth based on current market conditions, comparable properties, and property-specific factors.
Why Professional Valuations Matter
In an industry where pricing accuracy directly affects financial outcomes, professional valuations serve several important functions for home sellers.
Pricing guidance for sale. If you’re listing your home, an accurate valuation establishes the foundation for an appropriate listing price. Overpricing by even 5-10% can dramatically reduce buyer interest and extend your time on market. Accurate pricing attracts buyers and generates momentum.
Refinancing decisions. Understanding your home’s current market value helps you make intelligent refinancing decisions. If your home has appreciated, you may have sufficient equity to refinance or access equity through a cash-out refinance.
Estate or divorce planning. When homes are part of estate settlements or divorce agreements, an objective valuation by a certified professional prevents disputes and ensures fair division of assets.
Investment analysis. If you’re considering investment properties, professional valuations provide the market-based data needed for sound investment decisions.
Insurance coverage verification. Understanding your home’s current market value helps ensure your insurance coverage is adequate for replacement value.
The common thread: professional valuations transform guesswork into data-driven decision-making. For a transaction involving your most valuable asset, the cost of professional valuation is trivial compared to the financial consequences of mispricing.
Before the Valuation: What Sellers Should Know
Professional valuations typically require scheduling in advance. When you contact a C-REPS professional or other certified valuation specialist, be prepared to provide basic information about your property.
Property basics include your home’s address, type (single-family, condo, multi-unit), age, size (square footage), number of bedrooms and bathrooms, lot size, and any major improvements or renovations.
Timeline flexibility matters. Most valuations can be scheduled within a few days, but professionals appreciate advance notice when possible. If you need a valuation urgently, communicate that when requesting the appointment.
Access requirements should be clarified. The valuation professional will need access to all areas of the property, including the attic, basement or crawl space, garage, and exterior. Ensure that any security systems are disabled or that you’ll be present to grant access.
Availability preferences help schedule efficiently. Professionals often have preferred times for valuations. Morning or midday appointments typically work better than early evening, as professionals want adequate light for exterior evaluation and photography.
Recent improvements or repairs should be noted when scheduling. If you’ve recently replaced the roof, updated the kitchen, or completed other significant work, mention this. The professional will ask detailed questions about these improvements.
Known issues or concerns can be mentioned upfront, though professionals will identify these themselves during the evaluation. If there’s a history of roof leaks, foundation concerns, or other issues, this context can be helpful.
When the appointment is scheduled, the professional will likely confirm the appointment date and time, sometimes providing guidance on how to prepare the home.
Preparing Your Home for Valuation
While professionals conduct valuations for properties in various conditions, preparing thoughtfully helps ensure the valuation is accurate and favorable. Preparation is not about deception; it’s about allowing the professional to see your home clearly.
Deep cleaning throughout makes the most significant difference. A thoroughly clean home presents better and allows professionals to assess condition rather than be distracted by clutter or dirt. Pay special attention to kitchens, bathrooms, and high-traffic areas.
Declutter to show space. Remove excess furniture, personal items, and clutter that obscures room size and layout. A home that looks spacious and organized presents better than one packed with belongings.
Address obvious maintenance issues. Fix leaky faucets, replace burned-out light bulbs, repair broken cabinet doors, and address other visible maintenance problems. These signal poor care and create negative impressions.
Ensure good lighting. Open curtains and blinds to maximize natural light. Replace any burned-out bulbs in interior fixtures. Good lighting makes spaces look larger and more inviting.
Organize accessibly. If the professional requests to see the attic or basement, have these spaces as organized as possible. This creates a favorable impression about overall home maintenance.
Prepare documentation. Gather receipts or records for major improvements, roof replacement, HVAC servicing, electrical or plumbing updates, or other significant work. Having this information readily available helps the professional understand your home’s condition and investment in maintenance.
Secure pets. Arrange to have pets confined or boarded during the valuation. Pets create distractions and potential liability concerns for the professional.
Ensure access. If you have security systems, gate locks, or other access restrictions, have these ready to grant the professional entry. Difficult access can complicate the valuation process.
The goal is straightforward: help the professional see your home’s best features without obstacles or distractions.
During the Valuation: What Happens
Most residential property valuations require 30 minutes to an hour, depending on the property’s size and complexity. Understanding the typical process reduces surprises.
Initial walkthrough. The professional typically begins with an exterior evaluation, examining the property’s curb appeal, roof condition, siding, windows, doors, landscaping, and overall maintenance. They’ll photograph or note significant features and condition.
Interior systematic evaluation. Moving inside, the professional systematically evaluates each room, noting size, condition, flooring, walls, ceilings, lighting, and fixtures. They’ll take measurements of major living spaces and note architectural features, windows, and condition issues.
Kitchen and bathroom focus. Kitchens and bathrooms receive particular attention because they significantly impact value. Professionals note appliance age and condition, cabinet quality, countertop materials, plumbing fixtures, and layout functionality.
Systems inspection. The professional evaluates visible evidence of major systems, including HVAC (furnace, air conditioning), electrical panel (updated or outdated), plumbing (evidence of leaks or corrosion), water heater age, and roof condition. They’re not conducting detailed inspections, but they note obvious issues.
Condition assessment. Throughout the walkthrough, the professional evaluates overall condition, noting deferred maintenance, recent updates, cosmetic condition, and any obvious problems like water damage, foundation cracks, or pest evidence.
Measurement and documentation. The professional takes measurements of major rooms and living areas, photographs the exterior and key interior spaces, and documents significant features, improvements, or condition issues.
Exterior and site evaluation. They examine the lot size, landscaping, driveway condition, drainage, and any site-specific factors affecting value. For multi-level homes, they note the number of stories and any unusual architectural features.
Comparable sales analysis. While some of this occurs in the office, the professional may discuss comparable properties they’re aware of in the local market, asking questions about your home’s positioning relative to recent sales.
Seller communication. The professional will likely ask you questions about your home, recent improvements, maintenance history, neighborhood changes, and your understanding of the market. They’re gathering context that helps refine their valuation.
Throughout this process, professional valuators maintain objectivity. They’re evaluating your property systematically against comparable properties and market data, not making personal judgments about your home or its features.
What Professionals Evaluate: Key Factors
Understanding what professionals focus on helps you recognize the factors that truly drive valuation and where preparation matters most.
Property condition ranks high in valuation factors. Homes in excellent condition command premiums. Properties requiring deferred maintenance see value reduction. Condition is visible and directly impacts what buyers will pay.
Square footage and layout affect value significantly. Larger homes generally command higher prices, but unusual layouts or low ceilings can reduce value per square foot.
Bedroom and bathroom count matters, particularly for residential properties. Homes with fewer bedrooms than comparable properties sell at a discount. Additional bathrooms add value disproportionate to their cost.
Lot size affects value based on market preferences and local norms. Larger lots may be valued highly in some markets; they’re irrelevant or undesirable in others.
Age and construction quality influence valuation. Newer homes typically command premiums, though well-built older homes may hold value. Materials and construction methods affect assessed value.
Location and neighborhood are critical. Homes in desirable locations with good schools, walkability, or commute access command premiums. Neighborhood trends affect value trajectory.
Recent improvements and updates can add value. A new roof, HVAC, plumbing, electrical updates, kitchen renovation, or bathroom updates all contribute to higher valuation if completed professionally.
Energy efficiency increasingly matters to buyers. Homes with energy-efficient windows, insulation, HVAC systems, or solar power may command premiums.
Parking and garage factors vary by market but significantly affect value in urban areas or places with limited parking.
Special features like waterfront access, views, architectural significance, or exceptional lot characteristics may justify premium pricing.
The valuation professional weighs these factors systematically, comparing your home to recent comparable sales and adjusting for differences. The result is a valuation grounded in comparable sales analysis, current market conditions, and professional expertise.
Understanding the Valuation Report
After completing the valuation, the professional prepares a detailed report. Understanding what this report contains helps you evaluate its accuracy and use it effectively.
The executive summary typically includes the property address, valuation date, property type, and the appraiser’s or valuer’s conclusion about market value.
Property description documents the subject property’s characteristics, including age, size, bedroom and bathroom count, construction quality, special features, and current condition.
Comparable sales analysis shows the properties used to establish market value, including sale prices, adjustments for differences, and the valuation conclusion drawn from comparable sales.
Condition assessment documents visible condition issues, recent improvements, and maintenance level. This section supports the concluded value by explaining how condition factors into the valuation.
Market analysis provides context about local market conditions, absorption rates, inventory levels, and market trends affecting the property.
Detailed breakdown often shows how the professional arrived at the valuation, including what factors supported value and what factors reduced value.
Photographs document the property’s condition, exterior appearance, key interior spaces, and notable features or issues.
The report’s level of detail varies depending on the valuation’s purpose and the professional’s methodology. Professional C-REPS valuations typically provide comprehensive detail supporting the concluded value.
Common Questions Sellers Ask During Valuations
Home sellers often have questions during the valuation process. Professional valuators welcome reasonable questions that help them understand the property and your goals.
How does my home compare to similar properties? This is reasonable to ask. Professionals can explain how recent comparable sales inform the valuation and how your home’s condition, features, and location compare to properties used for comparison.
What improvements would add most value? Professionals can offer perspective on which improvements might increase value most efficiently, though they’re typically not providing renovation consulting.
Is this valuation for listing purposes? Understanding the valuation’s intended use helps professionals interpret your question. Valuations for sale pricing may differ slightly from valuations for refinancing, as they may account for market-specific positioning.
What’s your assessment of the local market? Professionals typically offer perspective on whether the market is strong or weak, inventory levels, and demand characteristics.
How long should the home take to sell at this value? This is reasonable to discuss. Market conditions, competition, and positioning all affect time-on-market estimates.
Are there obvious issues that would concern buyers? This is an important question. Professionals can highlight condition issues that inspectors will certainly identify and that buyers will use in negotiations.
Questions to avoid include asking the professional to deliberately inflate or deflate the valuation, asking them to suggest illegal pricing strategies, or testing their objectivity with biased scenarios. Professional valuators maintain objectivity and won’t be swayed by seller pressure to adjust valuations beyond what market data supports.
After the Valuation: Using the Report Effectively
Once you receive the valuation report, several important next steps follow.
Understand the valuation. Read through the report carefully, understanding not just the concluded value but the reasoning behind it. Ask the professional to clarify anything unclear.
Compare to your expectations. If the valuation differs significantly from your expectations, discuss this with the professional. What factors caused the difference? Are you missing context about recent comparable sales or market conditions?
Use the valuation for strategic decision-making. If you’re selling, the valuation informs your listing price. If you’re refinancing, it determines your available equity. Use the professional’s analysis to make informed decisions.
Keep documentation. Store the valuation report securely. You may need it for refinancing, tax purposes, insurance considerations, or future reference.
Discuss pricing strategy. If you’re listing, work with your real estate professional to translate the valuation into an appropriate listing price. Market positioning, marketing strategy, and condition all factor into the final listing price decision.
Share with relevant parties. If you’re in a divorce or estate settlement, the valuation provides an objective basis for discussions about asset division.
Update your insurance. If the valuation significantly exceeds your home’s insured value, contact your insurance agent to ensure adequate coverage.
Valuation vs. Appraisal: Understanding the Difference
Many home sellers confuse valuations with appraisals. Understanding the distinction helps you recognize which service you need.
Appraisals are ordered by lenders and follow strict federal standards (USPAP, Uniform Standards of Professional Appraisal Practice). Appraisers are licensed and regulated. Appraisals are required for mortgage lending and provide the value the lender will use to determine loan-to-value ratios.
Valuations are conducted by trained real estate professionals using systematic methodology but without the rigid federal standards governing appraisals. Valuations are more flexible and used for various purposes, including pricing guidance, investment analysis, and refinancing decisions.
For home sellers, valuations are typically more relevant than appraisals. Valuations provide accurate market pricing information and help determine appropriate listing prices. Appraisals become relevant when you’re refinancing or dealing with mortgage lenders.
A C-REPS professional provides valuations trained in systematic methodology and market analysis. This is distinct from an appraisal but provides a professional, defensible assessment of market value.
Choosing a Professional Valuation Provider
Not all professionals providing valuations are equally qualified. Understanding what distinguishes quality valuation providers helps you select someone you can trust.
Certification matters. C-REPS professionals complete training and certification through NABPOP, demonstrating commitment to professional standards and systematic methodology. Certified professionals have passed exams and maintain continuing education requirements.
Local market knowledge is essential. A professional who understands your specific market, recent comparable sales, local trends, and neighborhood characteristics provides more valuable guidance than someone unfamiliar with your area.
Experience counts. Professionals who have valued hundreds or thousands of properties bring pattern recognition and expertise that newer professionals lack.
Professional reputation is important. References from past clients, online reviews, and recommendations from real estate professionals all signal quality and reliability.
Transparent methodology helps. Professionals willing to explain their approach, show the comparables they used, and discuss their reasoning inspire confidence.
No pressure or bias. Trustworthy professionals provide objective valuations regardless of whether you want them higher or lower. Professionals pushing toward predetermined conclusions are prioritizing something other than accuracy.
When seeking a valuation, ask about the professional’s qualifications, experience, and methodology. Don’t simply accept the first estimate; compare perspectives from multiple qualified professionals if the stakes are high.
Common Valuation Mistakes and How to Avoid Them
Several common mistakes can compromise valuation accuracy or create problems for sellers later.
Failing to disclose known issues undermines the valuation’s reliability. If you know about roof problems, foundation concerns, or other issues, full disclosure helps professionals conduct accurate valuations and prevents surprises during buyer inspections.
Overstating recent improvements without documentation weakens the valuation. Professional-quality work with receipts and permits carries more weight than claimed improvements without evidence.
Expecting valuations to match emotional attachment. A home may feel worth a certain amount to you, but market value is determined by comparable sales, not personal attachment. Objective assessment requires acknowledging market reality.
Neglecting home presentation. A dirty, cluttered home creates unfavorable impressions affecting valuation. Preparation costs nothing compared to potential impact on assessed value.
Arguing with the professional. If you disagree with a valuation, ask questions and understand the reasoning. Arguing won’t change the professional’s assessment if it’s grounded in market data.
Using outdated valuations. Market conditions change. A valuation from a year ago may not reflect current conditions. Get current valuations when market conditions have shifted significantly.
Assuming online tools replace professional valuations. Online estimates provide ballpark figures but lack the detailed analysis and market knowledge of professional valuations.
Avoiding these mistakes ensures that your valuation is accurate, defensible, and useful for decision-making.
Frequently Asked Questions
How long does a property valuation take?
Most residential property valuations require 30 minutes to an hour on-site. The professional may need additional time in the office to prepare the report, typically one to three business days. From scheduling to receiving the report, expect a one-to-two-week turnaround.
How much does a professional property valuation cost?
Valuation fees vary by location and professional, typically ranging from $300 to $500 for residential properties. Some professionals provide free consultations or pricing opinions. C-REPS professionals’ fees reflect their training and certification. Compare fees but prioritize professional qualification over price alone.
Can I get a free valuation instead of paying for a professional one?
Buyer’s agents sometimes provide free “comparative market analyses” to encourage listing with them. These have value for pricing guidance but lack the objectivity and detailed analysis of independent professional valuations. For significant financial decisions, professional valuation fees are worthwhile investments.
Do I need to be home during the valuation?
Being present is helpful, as the professional may ask questions about improvements, maintenance history, or the home’s features. However, some professionals prefer clients not be present to avoid bias. Confirm the preference when scheduling.
Will the valuation affect my property taxes?
No. Property valuations for sale pricing or refinancing decisions are separate from property tax assessments. Your local assessor determines property values for tax purposes through different methodologies, typically on a multiyear cycle.
What if I disagree with the valuation?
Discuss your concerns with the professional. They can explain their reasoning, show comparable sales used, and discuss factors affecting the valuation. If you still disagree, you can obtain a second valuation for comparison. However, if multiple qualified professionals reach similar conclusions, the market is likely telling you something about your home’s value.
Is a valuation the same as what my home will sell for?
A valuation estimates market value based on current conditions and comparables. The actual sale price depends on buyer demand, market conditions, listing pricing, marketing effectiveness, and negotiations. The valuation provides a baseline; the actual price may be higher or lower depending on these factors.
How do I know if a valuation is accurate?
Accurate valuations are grounded in recent comparable sales, systematic analysis, and current market conditions. If the valuation significantly exceeds all recent comparable sales without justification, it’s likely optimistic. If it’s significantly below comparable sales, it’s likely conservative. The most accurate valuations typically fall within the range of recent comparable sales with appropriate adjustments.
Should I get a valuation before listing my home?
Yes. A pre-listing valuation helps determine an appropriate listing price, positions you for a faster sale, and prevents overpricing that extends your time on market. The valuation’s cost is trivial compared to the expense of holding an overpriced property.
Can I use an appraisal from a refinance instead of getting a separate valuation?
Possibly, but appraisals are conducted for lender purposes and may not align perfectly with market pricing for sale purposes. The lender’s appraisal is designed to protect the lender, not to establish optimal listing prices. A current valuation specifically for sale pricing is preferable if you’re planning to sell soon.