FIRPTA Foreign Property Sales: What Sellers Need to Know Before Closing
Selling a U.S. property when you live outside the country brings a layer of tax and legal obligations that domestic sellers never face. The most important of these is the Foreign Investment in Real Property Tax Act, known as FIRPTA. Understanding FIRPTA before you list your home, condo, or investment property protects your proceeds, keeps your closing on schedule, and helps you avoid penalties that can follow a sale for years.
This guide explains how FIRPTA foreign property sales work, who it applies to, how withholding is calculated, which exemptions may apply, and what steps sellers should take to stay compliant.
What Is FIRPTA?
FIRPTA is a U.S. federal law, enacted in 1980, that taxes gains from the disposition of U.S. real property interests held by foreign persons. Congress passed it to ensure that foreign owners pay tax on U.S. real estate gains in the same way that U.S. citizens and residents do.
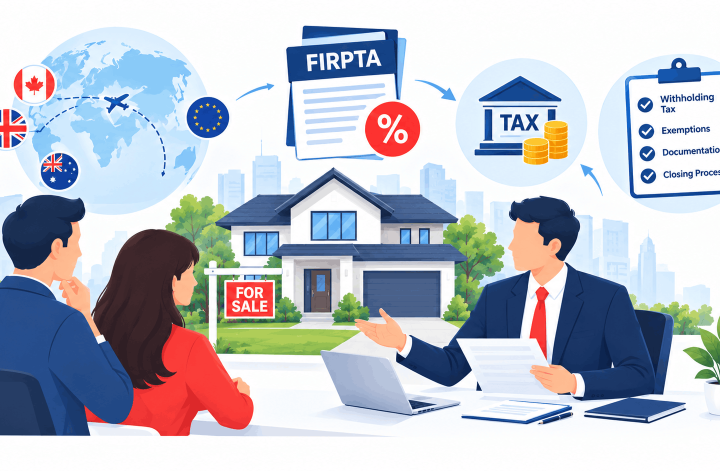
Under FIRPTA, the buyer is generally required to withhold a portion of the sale price and send it to the Internal Revenue Service (IRS) at closing. That withheld amount is credited toward the seller’s actual U.S. tax liability. If the withholding exceeds what the seller owes, the seller can claim a refund by filing a U.S. tax return.
Why FIRPTA Matters for Sellers
Many foreign sellers are surprised to learn that the withholding happens automatically at closing, not after the fact. Without planning, you may receive significantly less cash than you expected on closing day. Understanding the mechanics in advance lets you prepare the right documents and budget for timing differences.
Who Counts as a Foreign Seller?
FIRPTA applies based on the seller’s status for U.S. tax purposes, not simply where they currently live. The definition of a “foreign person” generally includes:
- Nonresident alien individuals
- Foreign corporations not engaged in a U.S. trade or business
- Foreign partnerships, trusts, and estates
A person who holds a U.S. green card or meets the substantial presence test may be treated as a U.S. resident for tax purposes, even if they spend most of their time abroad. Because these rules are technical, sellers with mixed residency should confirm their status before the transaction begins.
How FIRPTA Withholding Works
The standard withholding rate under FIRPTA is 15 percent of the amount realized on the sale. The amount realized generally includes the cash paid, the amount of any debt the buyer takes over, and the fair market value of other property transferred as part of the consideration.
A Practical Example
Suppose a nonresident seller sells a condominium for $500,000, with no mortgage assumed by the buyer. The buyer would typically withhold $75,000 at closing (15 percent of $500,000) and remit it to the IRS. The seller would receive the remaining $425,000, minus normal closing costs and any loan payoff.
If the seller’s actual capital gains tax is only $20,000, the seller can file a U.S. tax return to claim a refund of the $55,000 difference. Refunds are not instant, so sellers should plan their cash flow accordingly.
Reduced Withholding Options
In some cases, the withholding amount can be reduced. Sellers may be able to request a reduced amount through a withholding certificate issued by the IRS, typically using Form 8288-B, when the expected tax liability is lower than the default 15 percent. Applications must be submitted before closing, and processing takes time, so this step should be started early.
Exemptions and Special Cases
Not every foreign sale triggers the full FIRPTA withholding. Common exceptions include:
- Sale price of $300,000 or less when the buyer intends to use the property as a personal residence and the buyer’s residence requirements are met
- Sales to certain buyers who will use the property as their own home, subject to specific rules
- Properties sold by foreign persons who are actually U.S. residents for tax purposes, who should provide the appropriate certification
- Transactions where the seller provides a valid certification that they are not a foreign person, such as a properly completed Form W-9 in qualifying situations
Each exemption has conditions and documentation requirements. Sellers should not assume an exemption applies without confirming eligibility, because a buyer who withholds incorrectly or a seller who claims an exemption improperly can face consequences.
Required Documentation
Compliance depends on paperwork. Sellers should prepare the following where applicable:
- A valid U.S. taxpayer identification number, either a Social Security Number or an Individual Taxpayer Identification Number (ITIN)
- Form 8288, the U.S. Withholding Tax Return for Dispositions by Foreign Persons, which the buyer or closing agent typically files
- Form 8288-A, which reports the withholding to the IRS and provides the seller with documentation
- Form 8288-B, if seeking a reduced withholding certificate
- A signed certification of non-foreign status, when claiming an exemption that relies on it
- Form 1040-NR, the U.S. nonresident income tax return, if the seller needs to report the gain and claim a refund or pay additional tax
Keeping copies of every form submitted and received protects you during future audits and when claiming credits.
Common Compliance Mistakes to Avoid
Foreign sellers and their advisors often run into the same issues. Watch for these:
- Assuming the buyer or agent will handle everything without seller input
- Waiting until the closing date to gather tax identification numbers
- Overlooking state-level withholding or transfer taxes, which operate separately from FIRPTA
- Failing to file a U.S. return to claim a refund after excess withholding
- Ignoring currency conversion effects on reported gains and foreign tax credits in the seller’s home country
- Relying on outdated information from forums or secondhand sources
Foreign Seller Checklist
Before listing a U.S. property, work through these steps:
- Confirm your tax residency status with a qualified U.S. tax professional
- Obtain a U.S. taxpayer identification number if you do not already have one
- Estimate your capital gain and expected U.S. tax liability
- Decide whether to request a reduced withholding certificate and start the application early
- Communicate with the title company or closing attorney about FIRPTA forms
- Set aside funds to cover timing gaps if a refund is expected
- File the required U.S. return after closing to reconcile your tax position
Working With Professionals
FIRPTA sits at the intersection of tax law, real estate, and cross-border regulation. A single error can delay closing or lock up proceeds for months. Sellers benefit from a coordinated team that may include a U.S. CPA or enrolled agent familiar with nonresident returns, a real estate attorney licensed in the property’s state, and a title company experienced with foreign sellers.
Pricing also matters. A property priced without current local market data can sit longer or sell for less than it should, which compounds the financial impact of withholding. Sellers who want an accurate, defensible price can ask a C-REPS certified agent for a professional pricing analysis. C-REPS professionals are trained and certified through the National Association of BPO Professionals (NABPOP), follow a professional code of ethics, and can connect you with a network of colleagues if your transaction requires specialized support.
Conclusion
FIRPTA is manageable when you understand it early. Confirm your residency status, gather your tax identification number, decide whether a reduced withholding certificate makes sense, and build a coordinated team before you list. With preparation, a foreign property sale can close smoothly, and your proceeds can reach you on a predictable timeline.
Frequently Asked Questions
What is FIRPTA in simple terms?
FIRPTA is a U.S. law requiring buyers to withhold a portion of the sale price when a foreign person sells U.S. real estate. The withheld money goes to the IRS and is credited against the seller’s actual tax bill.
How much is FIRPTA withholding?
The default rate is 15 percent of the amount realized, which usually means the total sale price plus any debt the buyer assumes. A reduced rate may be available with an IRS withholding certificate.
Can a foreign seller avoid FIRPTA withholding?
Some sellers qualify for exemptions, such as certain sales of properties priced at $300,000 or less to buyers who will live there. Eligibility depends on specific conditions, so confirm before assuming an exemption applies.
Do I get my FIRPTA withholding back?
If the withholding exceeds your actual U.S. tax liability on the sale, you can claim a refund by filing a U.S. nonresident tax return. Refunds take time, so plan your finances for the gap.
Do I need a Social Security Number to sell property in the U.S.?
Not necessarily. Sellers without an SSN can apply for an Individual Taxpayer Identification Number (ITIN) using IRS Form W-7. Start the application early, since processing can take several weeks.
Does FIRPTA apply to state taxes too?
No. FIRPTA is federal. Some states impose their own withholding or transfer requirements on nonresident sellers, so check the rules for the state where the property is located.
Who files Form 8288?
Typically, the buyer or the closing agent files Form 8288 and the associated Form 8288-A with the IRS after closing. Sellers should confirm who is responsible in their purchase agreement.
Should I hire a professional for a foreign property sale?
Given the tax, legal, and timing complexity, most foreign sellers benefit from working with a U.S. tax advisor, a licensed real estate attorney, and an experienced agent who can provide accurate pricing.