Foreclosure Property Valuation: Special Considerations for Distressed Assets
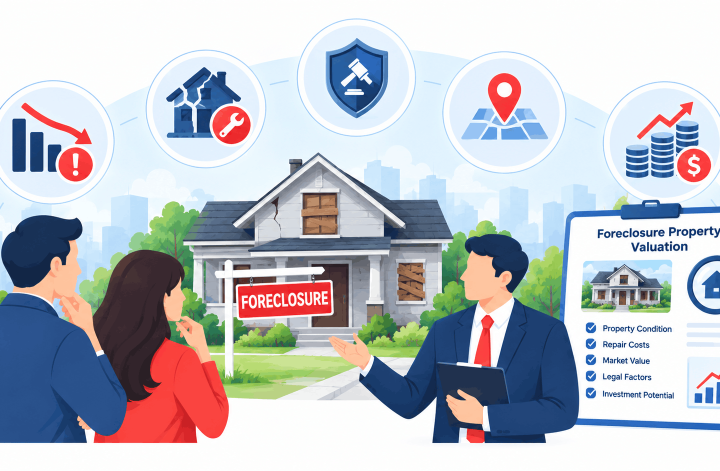
Foreclosure property valuation is the process of estimating what a distressed home is worth when it has been taken back by a lender, sold at auction, or is being marketed as a bank-owned (REO) property. These homes often look like bargains on paper, but their true value depends on factors that standard pricing methods do not fully capture: condition unknowns, title complications, limited access, and the motivations of the seller. Getting the number right matters for buyers deciding what to offer and for lenders or sellers deciding what to list for.
This guide explains how foreclosure and REO valuation differs from conventional pricing, which adjustments matter most, and how to avoid paying too much for a property that only looks inexpensive.
What Makes a Foreclosure Different
A conventional home is typically priced by comparing it to similar homes that recently sold in good condition under ordinary circumstances. Foreclosures break that pattern in several ways. The seller is often a lender that wants to recover its loss rather than maximize its return. The property may have sat vacant for months, and vacancy tends to accelerate deterioration. The owner may have stopped paying utilities, leaving pipes, appliances, and systems at risk. And the sale may come with limited disclosure, meaning the buyer knows less than they would in a standard transaction.
These factors mean that a foreclosure’s sale price can differ meaningfully from what the same home would fetch if it were move-in ready and fully disclosed.
Foreclosure, REO, and Short Sales
Several terms describe distressed properties, and they carry different implications:
- Pre-foreclosure: The owner has fallen behind on payments, but the lender has not yet taken the property. The owner may still sell or refinance.
- Auction (foreclosure sale): The property is sold at a public auction, often through a courthouse or trustee process, sometimes with limited inspection rights.
- REO (real estate owned): The lender has taken title after an unsuccessful auction and now markets the property directly, usually through an asset manager or listing agent.
- Short sale: The owner sells for less than the mortgage balance, with the lender’s approval. The seller is not yet foreclosed, but the sale is still shaped by lender terms.
Each category involves different timelines, disclosure levels, and negotiation dynamics, which affects how a valuation should be built.
The Core Valuation Approach
Foreclosure valuation still starts with the same foundation as any residential appraisal or pricing analysis: comparable sales, adjusted for differences in size, location, and features. The difference lies in how aggressively the analyst adjusts for condition and how carefully they separate the distressed sale from the market.
Step One: Establish the Market Value of a Comparable Home in Good Condition
Begin by estimating what the property would sell for if it were repaired and in typical condition. Analysts look at recently sold homes within a reasonable distance, with similar square footage, bedroom and bathroom counts, lot size, and age. Sales in the past three to six months carry the most weight in most markets, though slower markets may require a longer window.
Be cautious about using other foreclosure sales as comparables for the “good condition” baseline. Distressed sales can pull averages down and create a false sense of how a repaired home would trade.
Step Two: Estimate Repair and Rehabilitation Costs
Once a baseline value is established, the analyst estimates what it will cost to bring the home to that condition. This is where foreclosures require the most scrutiny. Repair estimates should cover:
- Roof condition and any water intrusion
- Foundation, structural, and grading issues
- Plumbing, including water heater and supply lines
- Electrical systems and panel capacity
- HVAC equipment, which may need replacement after long vacancy
- Interior damage such as flooring, drywall, cabinets, and fixtures
- Exterior issues such as siding, windows, and landscaping
- Mold, pest damage, or hazardous materials
Repair estimates should include a contingency. Experienced investors often add 10 to 20 percent to initial estimates because hidden damage tends to appear once work begins.
Step Three: Calculate the Net Value
A simplified valuation for a distressed property follows this structure:
Estimated Repaired Value minus Repair Costs minus Holding Costs minus Transaction Costs = Maximum Justified Price
Holding costs include property taxes, insurance, utilities, and any ongoing maintenance while the property is owned. Transaction costs include closing fees, title work, and selling costs if the buyer plans to resell.
Special Considerations That Affect Foreclosure Pricing
Several issues are unique to distressed properties and can significantly shift the valuation.
Title and Lien Risk
Foreclosures can involve tax liens, mechanics’ liens, HOA liens, or other encumbrances. Some liens survive a foreclosure sale, while others are extinguished, depending on jurisdiction and the type of sale. Buyers should obtain a full title search and, where appropriate, title insurance, and should factor any unresolved claims into their price.
Occupancy and Possession
A property may still be occupied by a former owner or tenant after the sale. Removing occupants can take time and legal action, and that delay carries costs. In some cases, a buyer may need to budget for relocation assistance or eviction proceedings, depending on local law.
Disclosure Limits
Many REO properties are sold “as is,” and lenders often provide limited disclosures. Buyers should not assume that the absence of a disclosure means the absence of a problem. A professional inspection is more important than usual in these transactions, and inspection contingencies are worth negotiating when the sale terms allow it.
Utility and Systems Status
Utilities are frequently shut off during vacancy, which can hide problems and cause damage. A home that has sat without heat through a winter may have burst pipes or compromised systems. When utilities are off, buyers should ask whether the property can be safely tested before purchase.
Deferred Maintenance
Vacant homes age faster than occupied ones. Lawns die, gutters clog, moisture accumulates, and pests move in. Deferred maintenance often hides beneath surface appearance, so a home that looks acceptable from the curb may need significant work inside.
Comparing Foreclosure and Traditional Valuations
The table below illustrates how two similar homes can produce different pricing conclusions.
| Factor | Traditional Listing | REO Property |
| Estimated repaired value | $320,000 | $320,000 |
| Condition | Well maintained | Vacant, needs repairs |
| Estimated repair cost | $0 | $45,000 |
| Holding costs (6 months) | $0 | $7,500 |
| Contingency (15 percent of repairs) | $0 | $6,750 |
| Maximum justified price | $320,000 | $260,750 |
| Typical asking price | $325,000 | $265,000 |
The REO property may appear to be a strong deal at $265,000, but the buyer’s realistic maximum is closer to $260,000 after accounting for repairs and holding costs. The difference is not a flaw in the market. It reflects the real expense of bringing the home to a sellable or livable state.
Pricing Strategies for Lenders and Sellers
Lenders and asset managers who own REO properties face their own valuation questions. Pricing too high can keep a property on the market for months, adding carrying costs and deterioration. Pricing too low can leave money on the table and invite quick offers that may not reflect the property’s full potential.
Effective REO pricing typically includes:
- An accurate as-is value, based on current condition
- A repaired value, to show buyers the potential after investment
- Documentation of known issues, to reduce surprises
- A realistic timeline, since vacant properties attract fewer buyers over time
- Competitive positioning against similar REO listings and conventional comparables
Lenders should also recognize that a property’s list price influences buyer expectations. An overpriced REO can become “stale” and face repeated price cuts, which can ultimately reduce net proceeds.
Practical Examples
Example 1: A Vacant Three-Bedroom Home
A three-bedroom house in a stable neighborhood has a repaired value of $280,000. The property has been vacant for eight months, and the inspection reveals a roof that needs replacing, outdated electrical panels, and water damage in the basement. Repair estimates total $52,000, with a contingency of about $7,800. Holding costs over the expected renovation period add roughly $9,000. The buyer’s maximum justified price is approximately $211,000, well below the repaired value and well below what a move-in ready version would command.
Example 2: An Auction Purchase
A buyer bids on a property at a courthouse auction, where the only inspection available is an exterior walk-through. The buyer estimates a repaired value of $190,000 and repair costs of $40,000, but the interior is unknown. After accounting for a title review that reveals an outstanding tax lien, the buyer reduces the maximum bid to account for the lien payoff and the risk of unseen damage. Because the risks are higher and information is limited, the buyer sets a conservative ceiling rather than bidding up to the theoretical maximum.
Actionable Steps for Buyers
- Run a title search before making any offer, and budget for any liens you discover.
- Build a repair budget from a professional inspection, not from a drive-by estimate.
- Add a contingency of 10 to 20 percent to initial repair estimates.
- Confirm whether the property is occupied and what it will take to gain possession.
- Find out whether utilities can be safely turned on for inspection.
- Compare the price against recent sales of repaired homes, not just other distressed sales.
- Set a maximum price before you bid, and stick to it.
Actionable Steps for Sellers and Lenders
- Order a current as-is valuation and a repaired value estimate.
- Disclose known issues clearly, which can reduce renegotiation after inspection.
- Price competitively against both REO and conventional listings in the area.
- Address basic safety and access issues, such as securing the property and restoring utilities if feasible.
- Revisit pricing at regular intervals, especially if the property remains unsold.
Common Mistakes in Foreclosure Valuation
- Treating the list price as the market value. Asking prices for REO properties are starting points, and final sales may differ.
- Using distressed sales as the only comparables. This can understate a repaired home’s value.
- Underestimating repairs. Hidden damage is common in vacant homes.
- Ignoring holding costs. Taxes, insurance, and utilities add up quickly over a long renovation.
- Skipping the title search. Unresolved liens can transfer costs to the new owner.
- Bidding emotionally at auction. Competitive pressure can push prices beyond what the property justifies.
Working With a Professional Pricing Specialist
Distressed properties benefit from careful, experienced analysis. Certified pricing professionals, including those who hold the C-REPS designation through the National Association of BPO Professionals (NABPOP), are trained to evaluate market evidence and adjust for the conditions that make foreclosures different. C-REPS professionals are licensed agents and brokers rather than appraisers, so they bring a market-facing perspective on what buyers are currently willing to pay in a given area.
When choosing a pricing professional for a distressed property, ask how they separated distressed sales from the market baseline, how they estimated repairs, and what assumptions they made about holding costs and timing. Clear answers signal a thorough process.
Frequently Asked Questions
What is foreclosure property valuation?
Foreclosure property valuation is the process of estimating the value of a home that has been foreclosed, is in pre-foreclosure, or is owned by a lender. It adjusts standard pricing methods for condition, repair costs, title risk, and the circumstances of the sale.
How is an REO property priced?
REO properties are typically priced using a repaired value estimate, minus the cost of repairs, holding costs, and a reasonable margin. Lenders often also consider an as-is value and recent comparable sales of similar homes in good condition.
Are foreclosures always a good deal?
No. Foreclosures can offer lower prices, but repairs, delays, liens, and limited disclosure can make them more expensive than they appear. The discount should be measured against the full cost of ownership, not just the purchase price.
What is the difference between REO and a foreclosure auction?
An REO property is one the lender has already taken back, usually after an auction fails to find a buyer. A foreclosure auction is a public sale where the property is sold before the lender takes title, and buyers often have limited inspection access.
Can I inspect a foreclosure before buying?
It depends on the sale type. Bank-owned REO properties often allow inspections, though access may be limited. Auction purchases frequently offer little or no interior access, which makes thorough due diligence more difficult.
What repairs should I budget for in a distressed home?
Common budget items include roof, foundation, plumbing, electrical, HVAC, interior finishes, and exterior maintenance. Vacant homes often need additional work due to moisture, pests, and deferred maintenance.
How do liens affect a foreclosure purchase?
Liens can remain attached to a property after a sale, depending on jurisdiction and the type of foreclosure. A title search helps identify them so the buyer can factor the cost into their offer or require payoff before closing.
Why would a lender price an REO property below market?
Lenders aim to recover losses and reduce carrying costs. Vacant properties deteriorate and attract fewer buyers over time, so pricing competitively can speed up a sale and limit additional expenses.