AI Machine Learning Real Estate Valuation: Future Trends
Property valuation has always been part science and part judgment. For decades, that balance rested on comparable sales, appraiser experience, and a feel for the local market. Today, artificial intelligence and machine learning are changing how values are estimated, how quickly they update, and how much data sits behind each number. For homeowners, buyers, and investors, understanding these shifts helps you make better decisions about pricing, financing, and timing.
This guide covers where AI-driven valuation stands, where it is heading, what it still gets wrong, and how to use these tools alongside professional guidance.
How AI Is Changing Real Estate Valuation
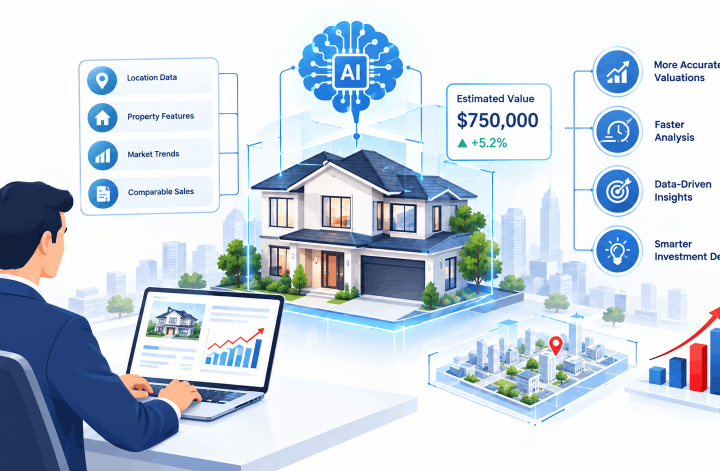
Traditional valuation relies on a limited set of recent sales, a visual inspection, and the appraiser’s judgment. AI-based valuation models work differently. They ingest large volumes of data, including past transactions, tax records, listing histories, neighborhood amenities, school boundaries, flood zone maps, and economic indicators, then look for patterns that humans might miss.
The Core Technologies Behind Automated Valuation
Several technologies sit under the umbrella of AI valuation:
- Automated valuation models (AVMs): Statistical and machine learning systems that estimate a property’s value from data without a site visit.
- Gradient boosting and neural networks: Algorithms that learn complex, nonlinear relationships between property features and sale prices.
- Computer vision: Systems that analyze listing photos, satellite imagery, or street-level views to assess condition, curb appeal, and renovation status.
- Natural language processing: Tools that read listing descriptions, inspection reports, and public records to extract details that structured data often misses.
- Time-series forecasting: Models that project how values may move based on interest rates, employment trends, and inventory levels.
Each of these tools adds a different kind of signal. The strongest systems combine several of them.
Why Speed and Scale Matter
One practical advantage of machine learning is frequency. A traditional appraisal is a snapshot taken at one moment. An AI model can update estimates weekly or even daily as new sales and listings enter the market. For a seller deciding when to list, or an investor tracking a portfolio, that refresh rate is valuable.
Where AI Valuation Is Heading
The next several years will likely bring changes in five areas.
1. Hybrid Human and Machine Valuation
The most credible future is not one where algorithms replace professionals. It is one where models do the heavy lifting on data and experts interpret the results. An agent or appraiser can review an automated estimate, flag what the model cannot see (a recent kitchen remodel, a drainage problem, a noisy highway that changed the block), and adjust accordingly.
2. Better Handling of Unique Properties
Early AVMs performed well on standard homes in dense markets with many sales. They struggled with unusual properties, rural land, historic homes, and neighborhoods with few transactions. Newer approaches, including models that borrow strength from similar areas and incorporate more detailed property attributes, are narrowing that gap. Even so, a one-of-a-kind property will usually need human review.
3. Explainable Valuation
Regulators, lenders, and consumers increasingly want to know why a model produced a given number. Explainability tools now show which factors pushed an estimate up or down, such as square footage, recent comparable sales, or proximity to transit. Expect this transparency to become a standard expectation rather than an optional feature.
4. Real-Time Market Signals
Valuation tools are beginning to incorporate faster inputs: mortgage rate changes, days on market, price reductions, and local inventory shifts. This means estimates may move more responsively to conditions, which is useful for sellers pricing in a shifting market but also means a figure from last month may already be outdated.
5. Tighter Data Quality Standards
Machine learning is only as good as its inputs. Incomplete public records, inconsistent property data, and errors in square footage or bedroom counts can all skew results. The industry is moving toward cleaner data pipelines and better verification, which should improve accuracy over time.
What AI Valuation Still Gets Wrong
Understanding limitations is just as important as understanding strengths.
- Condition is hard to see in data. A home with original 1980s wiring and a home with a new roof may look identical in a database.
- Local nuance can be missed. A street that flooded last spring, a planned highway expansion, or a well-regarded school that changed boundaries may not appear in the training data.
- Thin markets produce wide ranges. When few homes sell in an area, models have less to learn from and estimates can swing significantly.
- Bias can creep in. If historical data reflects past discrimination or uneven investment, models can reproduce those patterns unless developers actively test and correct for them.
- Recent changes lag. Renovations, additions, and improvements are often not recorded promptly, so the model may not know about them.
For these reasons, an automated estimate is best treated as a starting point, not a final answer.
Traditional Appraisal vs. AI Valuation vs. Certified Agent Pricing
Each approach serves a different purpose. The table below compares them in general terms.
| Factor | Traditional Appraisal | AI Valuation Model | Certified Agent Pricing (C-REPS) |
| Primary input | Site visit, comparable sales, appraiser judgment | Large datasets, property records, market patterns | Local market activity, buyer behavior, property condition |
| Speed | Days to weeks | Seconds to minutes | Typically days, with ongoing market monitoring |
| Strength | Formal documentation, lender-recognized | Scale, frequency, consistency | Real-market knowledge and negotiation insight |
| Weakness | Can be slow and costly | Struggles with condition and unusual properties | Depends on the individual’s training and ethics |
| Best use | Mortgage and legal requirements | Quick estimates and monitoring | Setting a list price or evaluating an offer |
Note that an appraisal is generally required for mortgage lending, while an agent’s pricing opinion is a marketing and negotiation tool. Each serves a different purpose.
What This Means for Home Sellers
If you are preparing to sell, you will likely encounter several automated estimates before you list. These numbers often appear on property websites and can influence expectations, sometimes significantly.
Here is a practical approach:
- Check several estimates. Different models use different data, so their results may vary.
- Ask why the numbers differ. Recent renovations, lot size, and condition can explain gaps.
- Get a professional opinion. A certified agent can evaluate what buyers in your specific neighborhood are actually willing to pay today.
- Document improvements. Keep receipts and permits for upgrades. Records help both human and automated valuations reflect your home accurately.
- Price for the market, not the algorithm. An estimate is informative, but the sale price is set by what buyers will pay.
Sellers who overprice based on an inflated online estimate often sit on the market longer, which can ultimately lower the final sale price.
What This Means for Home Buyers
Buyers benefit from AI tools when they use them for research. Automated estimates can help you screen listings quickly and spot neighborhoods where prices may be out of line with recent trends.
Keep these points in mind:
- An estimate is not an offer. Use it to frame your research, not to set your maximum bid.
- Lenders typically require a formal appraisal. If the appraisal comes in below the contract price, you may need to renegotiate or cover the gap.
- Ask your agent for a comparative market analysis based on recent local sales and active listings.
- Pay attention to what an estimate cannot see: condition, layout, neighborhood changes, and future development plans.
Practical Examples
Example 1: The renovated bungalow. A homeowner updated the kitchen and bathrooms but did not report the work. The automated estimate used the original floor plan and older condition data, producing a figure well below the home’s market potential. A certified agent reviewed the renovation details, compared recent sales of similarly updated homes, and recommended a list price that reflected the improvements.
Example 2: The buyer’s surprise. A buyer saw a strong online estimate for a townhouse and offered near that number. The lender’s appraisal came in lower because two comparable sales in the complex were much less recent and had been priced differently. The buyer, with agent guidance, negotiated a revised price instead of waiving the appraisal contingency.
Example 3: The rural property. An owner with five acres and a detached workshop received an automated estimate that ignored the acreage and outbuilding. The agent gathered sales of comparable rural properties and adjusted the valuation to account for land and improvements.
Actionable Tips for Getting the Most Accurate Value
- Keep a home improvement log with dates, costs, and contractor details.
- Gather documentation such as permits, warranties, and inspection reports.
- Note recent changes to the neighborhood, like new construction, transit access, or zoning updates.
- Compare at least three sources before drawing conclusions.
- Talk to a local professional who can interpret data in context.
Frequently Asked Questions
How accurate are AI home valuations?
Accuracy varies widely by location, property type, and data quality. Models tend to perform best in active markets with many recent sales and standard homes. Unusual properties and thin markets usually produce wider margins of error, so treat any automated figure as an estimate.
Can AI replace appraisers and real estate agents?
Not in the near term. AI handles data processing well but cannot inspect a property, understand local context in full detail, or negotiate. The most effective approach combines automated tools with trained professionals who can verify and interpret results.
Why do different websites show different home values?
Each platform uses its own data sources, algorithms, and update schedules. Some include off-market data or different property attributes. Differences are normal, and comparing them can reveal useful information about the home.
Will AI valuation make home prices more transparent?
It can improve transparency by making estimates more accessible and explainable. However, transparency depends on data quality and how openly platforms share their methods. Consumers should still verify important numbers with recent local sales.
Are online home estimates reliable enough to set a listing price?
They can inform a pricing discussion but should not be the sole basis for a list price. A comparative market analysis from a certified professional, based on recent local sales and current buyer demand, is more reliable for setting a competitive price.
How often should I check my home’s estimated value?
If you are planning to sell in the next year, checking quarterly can help you track trends. For long-term owners, an annual review is usually enough. Major market shifts or renovations are good reasons to check sooner.
What data should I provide to improve an automated estimate?
Share accurate square footage, a list of recent upgrades with dates, and any known condition issues. Many platforms allow owners to correct property details. More accurate inputs generally lead to more accurate outputs.
Do certified agents use AI tools too?
Many do. Certified professionals often use automated estimates as one input among several. Their added value lies in local market knowledge, property walkthroughs, and the judgment needed to adjust for factors data cannot capture.